
Next Gen Supply Chain Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
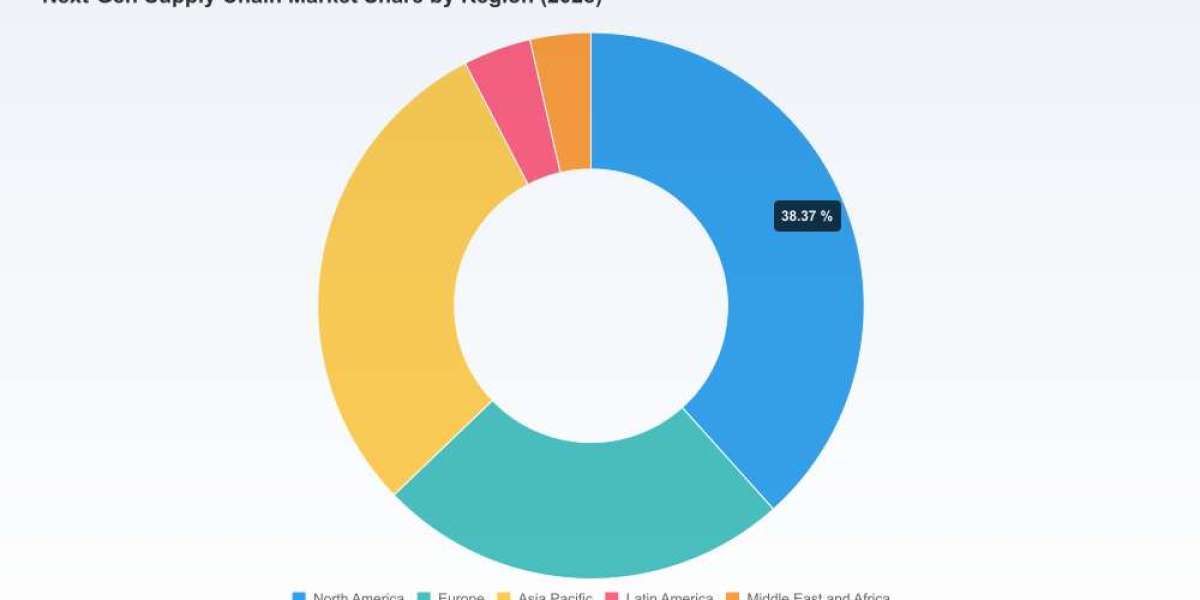
PW Consulting’s Next Gen Supply Chain Market report (base year 2025) synthesizes five years of historical market behavior and a seven-year forecast to deliver a pragmatic playbook for enterprise leaders preparing decisions in 2026. At the headline level, the global next‑generation supply chain market reached USD 62,450 Million in 2025 and is projected to exceed USD 132,962 Million by 2032, growing at a compound annual growth rate (CAGR) of 11.4% over the forecast period. Market concentration remains low to moderate (CR3: 18.5%; CR5: 28.3%), underscoring a highly fragmented ecosystem where platform incumbents, specialized robotics vendors, and a long tail of niche innovators compete and collaborate.
Worldwide Orthopaedic Cushions Market
Why this report matters for 2026 strategy
Decision clarity amid complexity: The pace of technology adoption—especially AI/ML, robotics, and pervasive connectivity—creates option-rich but risk-heavy paths. This report converts noise into prioritized investment themes and capability milestones so executives can set a 12–36 month roadmap tied to measurable outcomes.
Worldwide Route-based Vibration Analyzers MarketCapital allocation for resilience: With geopolitical volatility and reshoring pressures driving multi‑regional footprint decisions, CFOs and supply chain leaders need defensible capital plans. Our forecast and scenario analyses quantify the trade-offs between redundancy, agility, and cost-to-serve without overrelying on vendor promises.
Worldwide Hearing Instruments MarketOperationalizing AI and agentic systems: As 70% of executives now rank next‑gen supply chain among their top three tech priorities and transformation momentum increased to ~72% in 2025, the pressing question is not whether to adopt but how to implement responsibly. The report provides concrete guardrails for data architecture, compute sizing, and phased model deployment—essential inputs for 2026 pilots and procurement cycles.
What the report contains — practical, execution-focused content
This is not an abstract industry paper. PW Consulting’s report is structured as an implementation-first toolkit for leaders who must move from strategy to execution in 2026. Key deliverables include:
Market sizing and validated forecasts (2020–2032), with scenario variants tied to geopolitics, energy constraints, and regulatory adoption curves.
Investment playbooks with ROI models and TCO templates for cloud vs. on‑prem AI infrastructure, including recommendations for balancing compute, energy, and latency requirements for digital twins and real‑time orchestration.
Vendor due‑diligence frameworks and a scoring methodology that assesses technology fit, execution risk, partnership elasticity, and product roadmaps—designed for RFP and shortlisting processes.
Use‑case deep dives (e.g., concurrent planning, demand sensing, autonomous fulfillment, supplier orchestration) with stepwise implementation templates, KPIs, and org-change checklists.
Compliance and data governance playbook addressing emerging regulations (notably EU’s Digital Product Passport) and cross‑border data flows—crucial for manufacturers and retailers planning 2026 product and supply chain launches.
Workforce transition and capability maps: pragmatic guidance on reskilling, center-of-excellence design, and change metrics to avoid capability gaps when adopting automation and agentic tools.
Macro dynamics shaping 2026 choices
Three structural forces dominate the strategic landscape for 2026:
Regulatory and product‑digitization mandates. The Digital Product Passport and similar governance initiatives convert physical items into data-rich assets. This drives a minimum baseline for traceability and increases the value of integrated master data management across supplier networks.
Compute and energy constraints. AI workloads are materially changing infrastructure economics—rack power densities and data center electricity consumption are rising rapidly—creating a new constraint set for companies planning real‑time optimization and digital twins. These realities must be factored into procurement and site-selection decisions for compute-intensive pilots in 2026.
Geopolitical volatility and multi‑regional resilience. Shifting trade policies and geopolitical risk profiles are prompting organizations to re-evaluate sourcing strategies, embrace diversified supplier bases, and in many cases accelerate reshoring. Our scenarios detail the cost‑benefit thresholds at which reconfiguration makes sense operationally and financially.
Competitive landscape — how to think about vendors in 2026
The market’s moderate concentration means no single vendor will be a universal winner. Instead, winning enterprise strategies will orchestrate an ecosystem of platform providers, specialized robotics and intralogistics vendors, and logistics technology specialists. Key archetypes and examples include:
Enterprise suite and orchestration platforms: Leaders such as SAP SE and Oracle provide end‑to‑end planning and orchestration capabilities and are moving aggressively into AI agent features and supplier onboarding automation. These platforms appeal to enterprises seeking integrated roadmaps and broad functional scope.
AI-native planning and real‑time orchestration: Companies like Blue Yonder and Kinaxis specialize in responsive planning and scenario modeling. Their strength lies in rapid what‑if analysis and concurrent planning that supports real‑time resilience.
Logistics and execution specialists: Manhattan Associates and Descartes Systems Group deliver focused execution capabilities in warehousing, transportation, and compliance—critical for companies prioritizing operational rigor.
Intralogistics and robotics innovators: Dematic, SSI Schaefer, Vanderlande, Swisslog, Daifuku, TGW, GreyOrange, Locus Robotics, and Hai Robotics represent a highly competitive sub-market for physical automation. Their solutions are the primary drivers of fulfillment productivity and are increasingly integrated with higher-layer orchestration to deliver end‑to‑end velocity gains.
Network and procurement specialists: E2open and GEP focus on networked visibility and procurement intelligence—areas that unlock supplier-level optimization and strategic sourcing advantages when combined with predictive analytics.
Given the diversity of specialist capabilities, our vendor analysis recommends a mixed-sourcing approach: anchor with a broad‑capability platform where it reduces integration risk, and complement with best‑of‑breed robotics and execution vendors where differentiated operational outcomes are required. Importantly, the report’s vendor scorecards and integration risk matrices are available for download to support 2026 procurement cycles.
Recent market signals worth watching (Q1–Q2 2026)
Industry events and recognition continue to shape adoption: awards and focused conferences are accelerating practical knowledge exchange and raising the bar for execution-oriented projects.
Infrastructure suppliers are scaling AI-optimized hardware: announcements from data‑center and server vendors highlight how compute supply chains are adapting to AI-driven demand—an operational factor that will dictate pilot cadence and total cost for compute-heavy initiatives.
Major software vendors continue to add agentic and supplier orchestration capabilities—features that materially change supplier onboarding, exception handling, and automated decision flows.
Strategic recommendations for 2026
Use 2026 to convert experimentation into durable advantage. Our top recommendations:
Prioritize a portfolio approach. Allocate spend across foundational data/compute investments, targeted automation pilots with clear KPIs, and ecosystem plays (supplier relationships, logistics partners) that reduce single‑point failures.
Design for energy and compute realism. Align AI ambitions with real infrastructure costs and lead times—embed energy constraints in pilot sizing and choose architectures that permit burst scalability without permanent overprovisioning.
Make compliance a feature, not a tax. Integrate product passport and traceability requirements into core data models now to avoid retrofitting during scaling phases.
Match vendor selection to the change curve. For short-term operational uplift, favor vendors with rapid time-to-value and low integration burden; for strategic transformation, prioritize platforms with clear API ecosystems and partner networks.
How to use this report in your 2026 planning cycle
Leaders should use the report to inform three concrete actions this year:
Finalize 2026 pilot portfolios with clearly defined exit criteria and scale triggers based on our ROI templates.
Run a vendor shortlisting sprint using the report’s scorecards to reduce procurement timelines and crystallize integration scopes.
Reassess data center and energy commitments through the lens of projected AI workload growth—adjust capital plans to avoid stranded compute or cooling capacity.
Closing note — why PW Consulting’s analysis is distinctive
Our Next Gen Supply Chain Market report blends quantitative forecasting (2020–2032) with explicit operational toolkits and vendor intelligence designed for immediate use in board and procurement settings. We surface the strategic inflection points enterprises face in 2026—where to accelerate, where to hedge, and where to partner—while preserving the granular subsegment tables and vendor scorecards for report subscribers. For executives who need to translate ambition into executable programs this year, the report provides the evidence base and the tactical templates to act decisively.
Access and next steps
For access to the full dataset, segmented market models, vendor scorecards, and downloadable playbooks, please visit the PW Consulting Next Gen Supply Chain Market report landing page. The public summary intentionally omits detailed subsegment breakouts to preserve the actionable intelligence contained in the full report and to ensure readers have the context needed to implement the recommendations effectively.
For detailed analysis of this topic, please visit the official page:Next Gen Supply Chain Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com