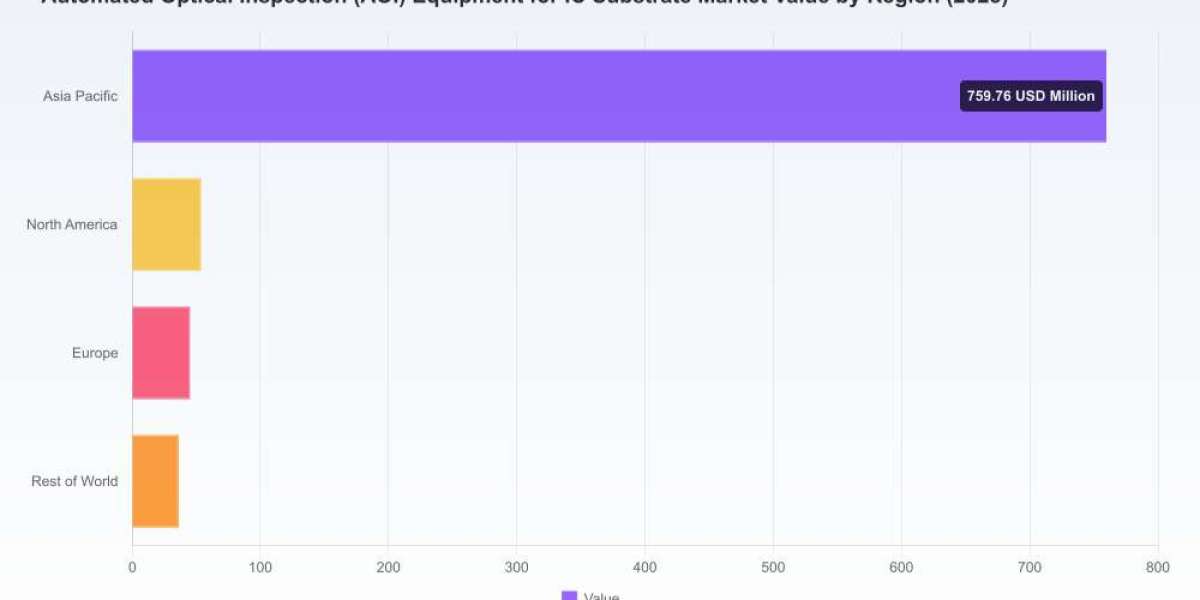

Worldwide Automated Optical Inspection (AOI) Equipment for IC Substrate Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s newest market research briefing on Worldwide Automated Optical Inspection (AOI) Equipment for IC Substrates provides an executive-grade synthesis of what procurement, operations, and R&D leaders must account for as they finalize 2026 budgets and multi-year roadmaps. The segment has shown durable growth through the last cycle — expanding from roughly USD 510 million in 2020 to about USD 895 million in our 2025 base year — and is projected to cross the USD 1 billion threshold in 2026, with a compounded expansion that drives it toward roughly USD 2.0 billion by 2032 (2026–2032 CAGR: approximately 12.18%). These headline dynamics create a window of strategic choices: accelerate capability acquisition now, or stage investments to manage regulatory and supply-side uncertainty. This briefing explains the tradeoffs and structures the decisions senior teams must make in 2026.
Worldwide Drum Funnel Market
Why this market matters now
IC substrate complexity is increasing — driven by high-density interconnects, fine-line/space requirements, glass-core and panel-level processes, and the proliferation of fan-out and multi-die modules. AOI has moved from being a quality-control convenience to a critical production gate for yield turnaround, process feedback, and qualification of advanced packaging nodes. The market’s rapid projected trajectory (doubling over the 2026–2032 forecast horizon at a mid-teens effective growth rate) means that near-term vendor choices materially affect unit economics, capacity ramp timelines, and yield trajectories for substrate shops and advanced packaging fabs.
Worldwide Wound Healing Assay Kits Market
At the same time, 2026 introduces non-market constraints that shape procurement strategy: export control regimes, tariff overlays, and multi-quarter lead times for high-resolution imaging components. These externalities affect not only what equipment you can buy, but how long it will take to integrate and qualify it — and how much total landed cost will be for a new AOI platform.
Worldwide Step Profiler Market
What PW Consulting’s report delivers (practical, implementation-focused)
- Forward-looking market sizing and a granular forecast model covering 2026–2032, designed to be dropped into CapEx and capacity-planning templates.
- Scenario-based demand simulations that reflect regulatory interventions, tariff regimes, and component-constrained supply chains, enabling stress-testing of procurement calendars and ROI thresholds.
- Vendor benchmarking and scorecards that combine technology fit, roadmap alignment, installed-base evidence, and implementation risk — distilled into decision matrices suitable for procurement committees.
- Implementation playbooks: RFP language, factory acceptance test (FAT) checklists, qualification sequences, and a calendar for pilot-to-full-rate transitions tailored to substrate production lines.
- Supply-chain mitigation strategies: alternative sourcing paths for cameras/optics, component-level replacement options, and contractual protections (lead-time guarantees, penalty clauses, escrowed firmware/diagnostic tools).
- Regulatory/compliance playbook: practical licensing guides, classification checkpoints, and product design mitigations to minimize export-control exposure.
- CapEx and TCO modeling templates that incorporate tariffs, duty scenarios, and extended lead-time buffers to produce realistic payback and IRR calculations.
- A concise executive risk register and action-priority plan for 90/180/360-day horizons to convert insights into board-level decisions.
Competitive landscape — who matters and why
The AOI competitive map for IC substrates combines global platform leaders with regional specialists that excel on particular process steps. Our analysis highlights high-concentration dynamics at the top: the market exhibits material concentration among the leading vendors (CR3 and CR5 metrics indicate cluster-driven market power), but a set of focused suppliers continues to capture specialized niches in inner-layer inspection, glass and panel-level packaging, and automated optical repair (AOR).
- KLA Corporation (Orbotech) — With flagship product families tailored to advanced substrate production, their platforms emphasize fine-feature imaging, multi-axis metrology, and throughput-optimized inspection workflows. KLA’s solutions are often the de facto choice when integrating inspection across high-density FC-BGA and glass-core process flows.
- Camtek Ltd. — A strong contender for mixed PCB and substrate environments; their Phoenix family is positioned for operations that need a tight mix of flexibility and high-end inspection capability at scale.
- CIMS — Focused on ultra-high-precision AOI and AVI systems that extend metrology into troublesome sub-5-micron regimes; appealing to substrate fabricators pushing aggressive line/space geometries.
- GigaVis — Notable for inner-layer inspection and AOR-focused equipment; has traction with IC-substrate manufacturers seeking improved defect localization earlier in the build process.
- MACHVISION Inc. & Intekplus — Regional leaders with strong engineering ties to Taiwan and Korea substrate ecosystems respectively, offering high-resolution defect detection and local service/response advantages.
- Chroma ATE Inc. — An increasingly important player on panel-level and glass-substrate AOI, demonstrated by recent showcases of sub-micron-capable BLiS™ solutions that address through-glass-via (TGV), RDL, and overlay metrology.
- Machine Vision Products (MVP) — Supplies a broad set of AOI systems for microelectronics and high-reliability applications, adding diversity to OEM choices for specialized lines.
These dynamics create a two-track supplier environment: large OEMs that offer end-to-end platform maturity and regional or niche suppliers that deliver faster feature innovation and service responsiveness. Our full report provides vendor-level scoring, procurement playbooks, and suggested split strategies for incumbent replacement and new-line capacity.
Regulatory and supply-chain headwinds to model into 2026 plans
- U.S. export control regimes (BIS classifications and expanded foreign-direct-product rules) now capture certain high-performance imaging and metrology modules. Expect licensing workflows and potential delivery delays when sourcing platforms destined for restricted geographies; compliance-driven redesigns may be necessary to remove controlled subassemblies.
- Section 232 tariffs and related trade actions have increased effective acquisition costs: affected systems can see single-digit to low-double-digit percentage impacts on landed cost unless embedded within a domestic-buildout justification. This materially alters payback calculations for cross-border procurement.
- Component scarcity persists for high-resolution cameras and specialized optics — our market intelligence finds typical lead times of 6–9 months for key subcomponents. Equipment delivery schedules must therefore be planned with extended buffers; consider staggered purchase orders or consignment strategies to protect launches.
- Expanded export-control classifications for laser modules and high-speed imaging assemblies are prompting vendors to review product architectures and supply chains. Buyers should demand component-level transparency and pre-shipment classification letters as part of contract negotiation.
Recommendations for 2026 decision-makers
- Prioritize capacity-critical lines for early AOI acquisition. If your production roadmap has high-density substrate ramps this year, accelerate procurement windows to avoid the 6–9 month camera/optics bottleneck.
- Adopt a hybrid vendor strategy: pair a Tier-1 OEM for anchor systems with niche suppliers for specialized inner-layer or glass-substrate inspection tasks. This reduces single-vendor risk and leverages best-of-breed capabilities.
- Build export-control and tariff scenarios into your financial models. Re-run TCO under multiple duty and licensing-delay assumptions to understand realistic payback ranges.
- Insert contractual clauses that require vendors to disclose supply-chain provenance for controlled subassemblies, and to provide alternative BOMs or modular configurations that can be reclassified if necessary.
- Invest in cross-training for internal metrology and inspection teams so vendor handovers require less on-site vendor time — a practical hedge against service and travel restrictions.
- Use pilot deployments to validate both defect coverage and cycle-time impacts; avoid “big bang” rollouts without staged qualification mapped to yields and downstream rework capacity.
- Negotiate staged payment terms tied to performance milestones (throughput, detection sensitivity, false-call rates) and include spare-parts kits on contract to reduce downtime exposure.
How to use the PW Consulting forecast in your 2026 planning cycle
Our forecast and scenario suite are structured to be operational from day one: plug the 2026–2032 demand vectors into your CapEx plan, align procurement tranches with your pilot/scale milestones, and overlay regulatory scenarios to identify critical decision gates. PW Consulting’s vendor scorecards and contract templates allow procurement teams to move faster while preserving negotiation leverage.
We deliberately present this briefing at a strategic level to help executive teams quickly assimilate the landscape. The full report contains the underlying models, vendor-share estimates, and region/application splits that enable transaction-level decisions. For teams preparing procurement approvals, engineering validation plans, or compliance roadmaps in 2026, that granular intelligence — combined with our actionable playbooks — is the difference between a smooth capacity ramp and a costly program delay.
PW Consulting will continue updating market surveillance through 2026 as regulatory and supply-chain conditions evolve (notable recent vendor deployments and demonstrations include Chroma ATE’s BLiS™ panel-level showcase in March 2026 and KLA’s Orbotech product highlights at CPCA 2025). For access to the complete dataset, vendor scorecards, and the downloadable CapEx/TCO templates, please visit our report gateway to obtain the full Worldwide AOI Equipment for IC Substrate Market study and supporting Excel models.
For detailed analysis of this topic, please visit the official page:Worldwide Automated Optical Inspection (AOI) Equipment for IC Substrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com