
Worldwide Intelligent Well Completion Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
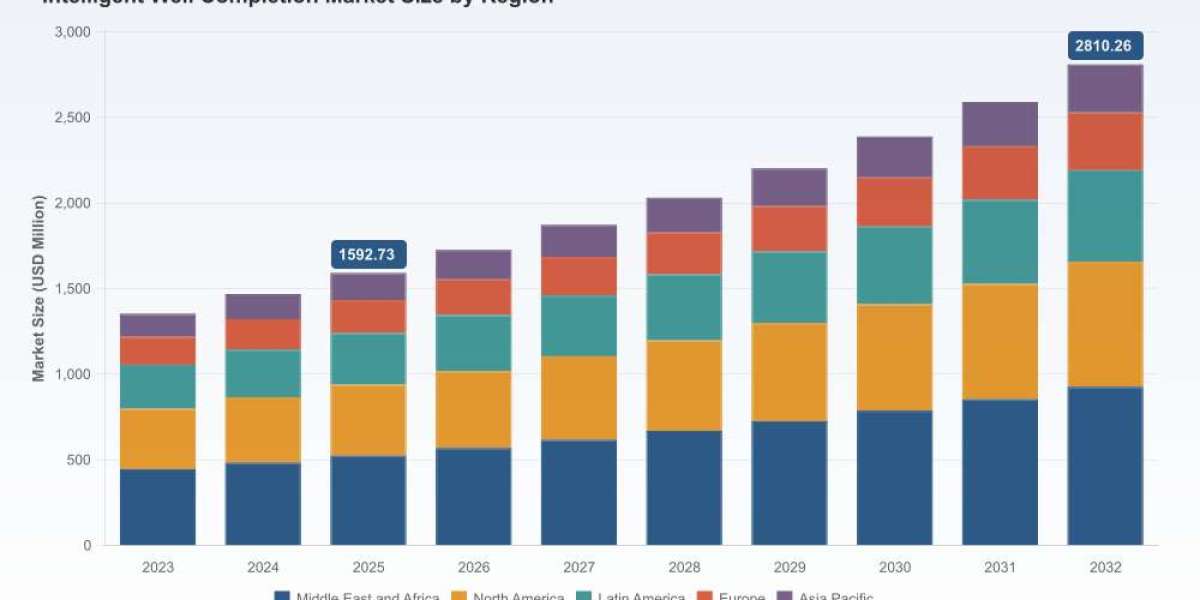
PW Consulting’s latest market study on Worldwide Intelligent Well Completions (base year 2025; historical 2020–2025; forecast 2026–2032) delivers a focused, decision-grade view of a market that is re-accelerating into a new cycle of technology-driven expansion. The market registered steady expansion through the mid-2020s and reached approximately USD 1.59 billion in 2025. Under our central forecast — driven by continued deepwater activity, increasing electrification of downhole systems, and greater adoption of distributed sensing and software orchestration — the market is expected to grow at a compound annual growth rate (CAGR) of 8.45% over the 2026–2032 forecast window, approaching roughly USD 2.81 billion by 2032. The market’s competitive structure remains moderately concentrated (CR3 ~58.5%; CR5 ~76.1%), with several large integrated service providers shaping technology roadmaps, while specialist suppliers and software integrators capture differentiated value.
Worldwide Pediatric Oxygen Masks Market
Why this report matters for decisions in 2026
- Capital allocation: Our forward forecasts and scenario stress-tests translate technology adoption timelines into explicit CAPEX and OPEX implications, enabling CFOs to size multi-year program investments and prioritize digital completion pilots versus large-scale rollouts.
- Procurement and supply chain resilience: The report quantifies sensitivity of completion system costs to raw material and tariff shocks, equipping procurement teams with hedging strategies, localization thresholds, and contract clauses to protect margins under volatile steel and aluminum prices.
- Go-to-market & partner selection: Operators and OEMs can use our vendor benchmarking to short-list partners for electrified completions, fiber-optic sensing, and wet-mate systems based on performance profiles, reliability track records, and deployment scalability.
- M&A and JV screening: With a concentrated supplier landscape and a clear technical differentiation axis (electric vs. hydraulic systems; embedded software/services), our valuations and market-share scenarios support disciplined corporate development actions in 2026.
- Regulatory and standards readiness: The study maps emerging standardization initiatives and API-level changes that materially influence qualification timelines, testing programs, and compliance costs for new product introductions.
Data-driven context: growth profile and structural signals
The intelligent well completion market is moving from pilot-heavy adoption to broader commercialization in targeted applications. After progressive growth during 2020–2025, the total market was estimated at ~USD 1.59 billion in 2025. At a modeled CAGR of 8.45% through 2032, the market enlarges to roughly USD 2.81 billion under our base-case scenario. This trajectory is underpinned by a confluence of demand-side drivers (deepwater program restarts, multi-zone reservoir optimization, electrification of completions, and higher value placed on digital reservoir insight) and supply-side forces (standardization, vendor consolidation, and the maturation of downhole telemetry and all-electric actuation).
Silicon Nitride Heating Element Market
Several structural signals in our analysis deserve attention: service providers that offer vertically integrated combinations of sensors, flow-control hardware, and cloud-native operations software capture disproportionate value; capital intensity remains elevated due to long lead times and qualification cycles for downhole hardware; and supply-chain exposure to commodity price swings and tariff regimes has become a measurable line item in bid mathematics.
Worldwide Carbon Source Laser Acupuncture Market
Competitive landscape: who matters and why
The market’s leading players continue to be a mix of global integrated service companies and focused component and systems specialists. Key firms profiled in the study include SLB (Schlumberger), Halliburton, Baker Hughes, Weatherford, and NOV — all with headquarters in Houston and with comprehensive portfolios spanning sensors, interval control valves, wet-mate connectors, and system integration capabilities. These incumbents are complemented by technology-focused suppliers such as Tendeka (inflow control), Packers Plus (multi-stage fracturing and zonal control), Welltec (downhole robotics and intervention), Expro (hands-free running and offshore systems), plus regional and specialty vendors that provide niche components or services.
Each major competitor exhibits a distinct strategic play:
- SLB: Strong in permanent downhole gauges and integrated completions, leveraging telemetry platforms and global service execution capability.
- Halliburton: Differentiated by modular SmartWell systems and recent large-scale deepwater contract awards; strong field execution and project delivery capabilities.
- Baker Hughes: Emphasizes all‑electric architectures and electronic monitoring suites aimed at reducing hydraulic complexity and improving reliability.
- Specialists (Tendeka, Packers Plus, Welltec, Expro): Win where focused device performance, reduced cycle time, or offshore systems expertise are decisive.
Recent commercial developments tracked in our primary research underscore the near-term market cadence: multi-well ultra-deepwater contracts awarded to major service providers and high-profile multi-zone deployments in the Middle East validating complex zonal-control architectures. These transactions crystallize demand pipelines for 2026 and beyond, while also serving as informative comparators for counterparty credit and execution risk analysis.
Dynamics, headwinds and operational levers
Our dynamics section synthesizes regulatory progress, raw-material price volatility, and standardization movements into practical operational implications:
- Standards and qualification: API updates and industry-led standardization efforts are shortening qualification uncertainty for electric completions and intelligent control valves but are also imposing new testing and documentation requirements that can extend product time-to-market unless addressed proactively.
- Commodity & tariff exposure: Sharp rises in steel and aluminum prices and extensions of tariff measures materially increase hardware costs. Equipment manufacturers and operators must plan for cost pass-through, renegotiation of long‑lead contracts, or localized sourcing to preserve margins.
- Technology adoption curve: Operators are increasingly prioritizing systems that enable real-time production steering and reservoir optimization. Electrification and fiber-optics are accelerating, but legacy hydraulic inventories remain a near-term constraint; migration strategies must therefore balance retrofit paths with new-build specifications.
- Commercial risks: Concentration among top suppliers creates both execution reliability and supplier-power risk. Our vendor risk scoring helps buyers construct redundant sourcing strategies and contractual protections.
What the PW Consulting report delivers — practical components
This research is structured to be immediately actionable for strategy, procurement, and operations teams. Highlights include:
- Comprehensive market-sizing and scenario-based forecast models (2026–2032) with sensitivity to material price shocks, tariff outcomes, and adoption pace of electrified systems.
- Vendor benchmarking and capability matrices covering hardware, sensing, telemetry, and software/service integration; each supplier profile includes execution risk, reliability evidence, and commercial positioning.
- Techno-commercial playbooks for electrified vs. hydraulic completions, fiber-optic deployment, and wet‑mate architectures, including qualification checklists and lifecycle cost models.
- Supply chain and procurement playbook: lead-time analysis, sourcing thresholds, contract clauses for price escalation, and localization decision trees.
- M&A and partnership screening toolkit: playbook for identifying tuck-in targets, technology-licensing opportunities, and JV structures to accelerate market entry or scale.
- Regulatory impact assessment: direct line items and timelines associated with relevant API and industry standard updates, and recommended compliance roadmaps.
- Appendices with primary interview transcripts, proprietary deployment case studies, and the full underlying data model (accessible for licensed clients).
How to use this intelligence in 2026 — recommended actions
- Run near-term CAPEX and OPEX scenarios that incorporate a 4–40% potential hardware cost escalation band driven by tariff and commodity exposure; use our sensitivity templates to prioritize projects with positive IRR under stress.
- Accelerate pilot programs for all-electric completions where reliability evidence exists, and plan a three-tier migration for fleets with legacy hydraulic inventories.
- Negotiate long-lead supply agreements with indexed escalation caps or secure option structures to manage price volatility while preserving optionality.
- Re-assess vendor counterparty exposure using the CR3/CR5 concentration context provided; build contingency sourcing with specialist suppliers to reduce single‑vendor risk on critical elements.
- Embed regulatory-readiness tasks into product development timelines to avoid rework and certification delays once new API or industry standards are enforced.
- For deal teams: use our valuation scenarios and market-share projections to size potential acquisitions that accelerate software integration, sensing competence, or regional execution capacity.
Closing: the strategic value proposition
This PW Consulting briefing synthesizes the commercial, technical, and regulatory vectors shaping intelligent well completions as operators and service providers plan 2026 programs. The study balances quantitative forecasting with executable guidance: it tells you where demand will be, why it will materialize, which vendors are best positioned to capture value, and how to structure programs and contracts to de-risk cost and delivery exposures.
For executives seeking the full model, granular segmentation, and the vendor scorecards that underpin our recommendations, PW Consulting provides licensed access to the complete Worldwide Intelligent Well Completion Market report, along with tailored advisory engagements to operationalize the findings for your 2026 planning cycle. Visit our report page to request the full dataset, scenario workbooks, and an executive briefing tailored to your portfolio.
For detailed analysis of this topic, please visit the official page:Worldwide Intelligent Well Completion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com





