
Worldwide Specialty Ink Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Specialty Ink Market distills actionable intelligence for executives, procurement leaders, and R&D heads planning for 2026 and beyond. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report combines rigorous quantitative modeling with front-line qualitative insight to translate industry noise—raw material volatility, regulatory shifts, and geopolitics—into a set of pragmatic strategic options. The global market is projected to continue healthy expansion through the forecast window, supported by a 5.24% compound annual growth rate (CAGR) and a robust increase in absolute market value between the base year and 2032.
Roasted Salted Mixed Nuts Market
Market Snapshot: What the Numbers Mean for Strategy
Our analysis shows a marketplace that is growing steadily but unevenly across product technologies and end-use channels. The headline metrics—base year 2025 market sizing and the 5.24% CAGR across the 2026–2032 forecast—frame the opportunity: specialty inks remain a mid-single-digit growth market with pockets of accelerated demand tied to digitalization, packaging evolution, and functional inks for electronics and security. Concentration metrics indicate a moderately consolidated industry (CR3 and CR5 levels that reflect that leading suppliers account for a meaningful share of revenue), implying both pricing power among incumbents and substantive opportunity for focused challengers with differentiated technology or routing logistics.
Gluten Free Oat Flour Market
Key Macro Drivers and Near-Term Dynamics
Raw material dynamics: Pigment, monomer, and specialty-resin costs are the single most immediate operational pressure on margins in 2026. Our interviews with supply-chain managers and primary-source intelligence indicate that pigment shortages and feedstock cost volatility are driving manufacturer responses—including list-price increases and surcharges—while compressing OEM procurement cycles.
On-Premises Electronic Laboratory Notebooks (ELN) MarketGeopolitical and logistics shocks: Disruptions to chemical feedstock flows tied to regional conflicts have elevated transportation and insurance costs, extended lead times, and catalyzed supplier-level force majeure events in early 2026. Several major suppliers have already announced portfolio-wide price adjustments that reflect these structural and transient risks.
Regulatory tightening: Evolving regulatory scrutiny—most notably on pigments and per‑ and polyfluoroalkyl substances (PFAS)—is influencing formulation pathways and compliance roadmaps. Policy developments such as draft risk-management initiatives for specific pigment chemistries and national approaches to PFAS require manufacturers to accelerate substitution programs and invest in regulatory science.
Technology and performance demand: Growth in digital printing, UV/LED curing, conductive and functional inks for electronics, plus low-migration formulations for food packaging, continues to re-shape product development priorities. The shift creates higher value-per-unit opportunities but also lifts R&D and regulatory compliance costs.
Segmentation: Trends to Watch (without the granular figures)
Rather than presenting a laundry list of segment shares, the report emphasizes directional trends that should guide strategic choices:
Type innovation: Energy-curable and functional inks are pulling investment because they align with fast-turn, high-throughput print processes and enable new applications (e.g., printed electronics). The industrialization of UV/LED systems and advances in resin chemistry make these segments a prime battleground for margin-rich innovation.
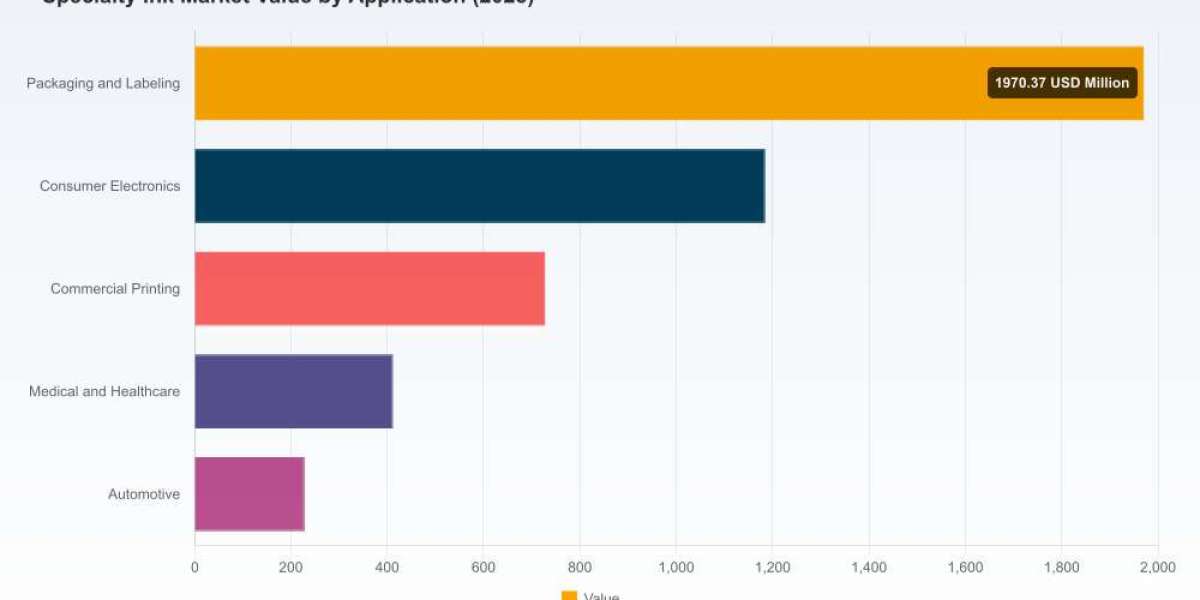
Application migration: Packaging and labeling continue to be the largest demand centers by value, driven by e-commerce, brand differentiation, and regulatory pressure on recyclability and food contact safety. Medical, electronics, and automotive applications are growing faster on a percentage basis, driven by functionality demands (biocompatibility, conductivity, heat resistance).
Regional dynamics: Growth patterns differ by macro-region due to varying end-market maturities, regulatory environments, and cost structures. Supply-chain resilience and proximity to feedstocks and customers will be decisive for plant siting and distribution strategies.
Competitive Landscape: Who Matters and Why
The market is anchored by established global players with broad portfolios and deep application expertise. Our competitive analysis synthesizes public disclosures, primary interviews, and recent market actions to help buyers and partners prioritize engagement.
Sun Chemical (DIC Corporation): A portfolio leader that spans digital, UV-curable, and functional inks. Recent moves include commercialization of higher-speed UV lines aimed at press-level productivity improvements, and price adjustments reflecting feedstock and logistics pressures. Expect continued emphasis on scale plus energy‑curable product performance.
Flint Group: Focused on packaging and pressroom technologies, Flint’s recent pricing actions underscore how raw‑material inflation affects contract negotiations and customer cost pass-through. Their deep flexo and gravure expertise positions them to influence packaging conversion trends.
Siegwerk & Hubergroup: European specialists that combine sustainability-anchored formulations and low‑migration capability. These firms are prominent where food-contact compliance and circularity requirements are most advanced.
Toyo Ink and Sakata INX: Japanese innovators that emphasize solvent-light and toluene-free systems; Toyo’s recent third-party certification for mineral-oil-free deinkability and capacity investments in India indicate strategic focus on both sustainability credentials and emerging‑market scale.
Regional and specialty challengers (INX, Nazdar, Marabu, Avient, Fujifilm Ink Solutions, Wikoff, Zeller+Gmelin, T&K TOKA): These firms compete on customization, service intensity, and niche technical capability. They are often preferred partners for short‑run, high-mix production or where regulatory dossiers are complex.
Consolidation activity, joint ventures, and targeted private‑equity investment continue to reshape competitive dynamics. Leading firms are balancing price responses with targeted R&D to defend premium positions while smaller players are doubling down on formulation agility and local service excellence.
Recent Industry Events That Matter for 2026
Price actions by major suppliers in early 2026 reflect a broader pattern of margin recovery efforts in the face of feedstock inflation and logistics challenges. Procurement organizations should expect multi-stage contract negotiations and contingency clauses tied to energy and raw-material indices.
Technology and certification wins—such as mineral‑oil‑free deinkability certifications and capacity expansions—signal where sustainability and regulatory compliance are translating into competitive differentiation and new volume opportunities.
Product introductions for high-speed presses and energy‑curable systems validate the industry’s shift toward throughput-optimized formulations that drive total-cost-of-ownership benefits to converters and brand owners.
What’s Inside the PW Consulting Report (Practical, Executable Content)
This isn’t a desk-study. The report provides hands-on decision support that procurement directors, R&D heads, and corporate strategists can use in 2026:
Scenario-based financial modeling: Fast‑track decision templates show how price increases, feedstock surges, or regulatory compliance costs affect EBIT and cash flow under multiple scenarios.
Supplier-risk heat maps: A methodology to prioritize supplier audits, dual‑sourcing candidates, and logistics resilience investments—aligned to your procurement levers.
Regulatory playbook: A compendium of compliance pathways for high-risk chemistries, including substitution matrices, testing protocols, and lobbying/engagement approaches tailored to North American and European regulatory regimes.
Go‑to‑market and R&D roadmaps: Tactical plans for launching energy‑curable or low-migration products, including recommended validation steps, certification sequences, and sample commercial contracts.
Commercial negotiation scripts: Language and indexation clauses procurement should use to manage pass-through risk, short-term surcharges, and long-term supply agreements.
Eight Strategic Imperatives for 2026
Recalibrate cost-to-serve: Introduce dynamic pricing collars and index-based pass‑throughs tied to pigments and energy indices.
Accelerate substitution R&D: Prioritize alternatives to at‑risk chemistries and certify them against expected regulatory thresholds.
Dual-source strategically: Use geography- and technology-aware dual‑sourcing for high-risk SKUs to reduce single-point failures.
Invest in digital traceability: Implement lot‑level tracking and sustainability claims reporting to meet buyer and regulator expectations.
Align product strategy with print-platform evolution: Match formulations to the installed base of digital and energy‑curable presses in target markets.
Monetize service: Offer technical support packages, in-line color management, and test‑to‑spec services as higher-margin offerings.
Lobby smart and proactively: Coordinate industry consortia to shape feasible compliance timelines and testing protocols.
Scenario‑proof capex: Defer or modularize capacity investments where demand uncertainty is highest; accelerate where certification and incumbent displacement provide clear payback.
How PW Consulting’s Intelligence Lowers 2026 Execution Risk
We combine bottom‑up SKU modeling, supplier balance‑sheet stress tests, and forward-looking regulatory analysis so leaders can make trade-offs explicitly rather than reactively. The report’s scenario suite quantifies how a 3–7% sustained raw‑material shock or a sudden regulatory burden would alter supplier economics, available margin, and feasible price pass-through. For M&A teams, the concentration metrics and competitive profiles isolate acquisition targets that offer either fill‑in capabilities or access to differentiated technologies.
Next Steps
PW Consulting’s Worldwide Specialty Ink Market report is designed as a working tool for 2026 planning cycles. If your 2026 budget, sourcing strategy, or product roadmap depends on reliable forecasts, regulatory roadmaps, or supplier stress testing, the full report contains the detailed datasets, regional and application breakouts, and executable templates you will need. For executives who require tailored briefings, PW Consulting also offers executive workshops that map the report’s scenarios to your specific SKU, supplier, and channel footprints.
To obtain the full dataset, segment-level analysis, and downloadable modeling templates, please visit our Worldwide Specialty Ink Market report page or contact your PW Consulting account lead for a confidential briefing. The summary above is intended to demonstrate the report’s strategic depth; the full intelligence package contains the granular, source-verified detail needed for immediate implementation.
For detailed analysis of this topic, please visit the official page:Worldwide Specialty Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com