
Borehole Camera Market 2026: Strategic Imperatives from PW Consulting’s Deep-Dive Analysis
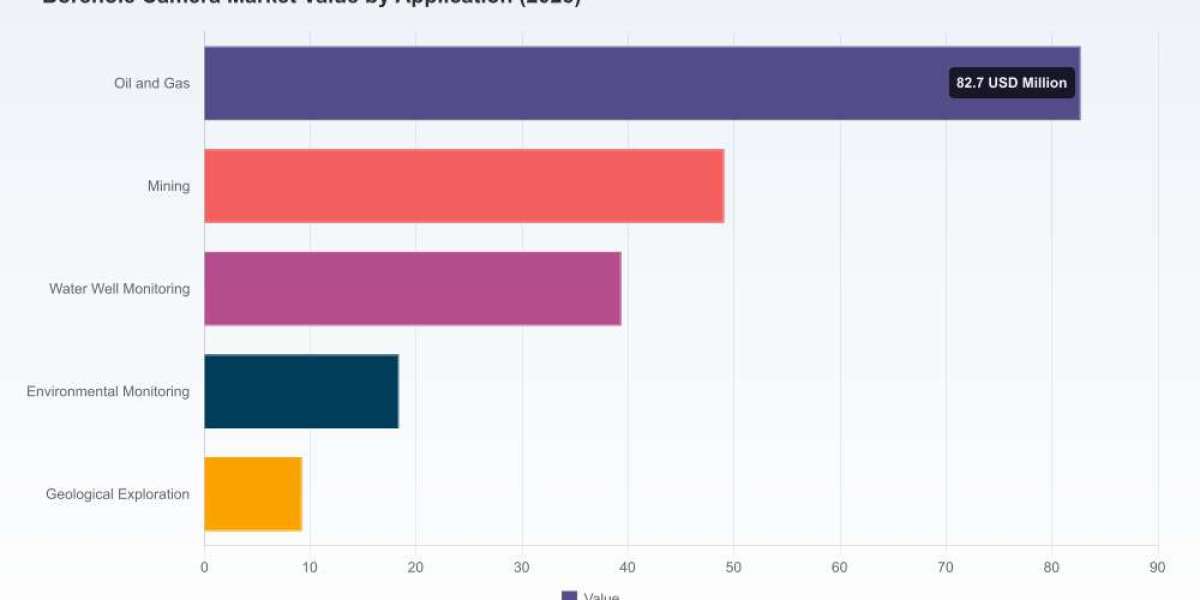
PW Consulting’s latest market research on the Borehole Camera Market—anchored on a 2025 base year and a 2026–2032 forecast horizon—delivers a pragmatic roadmap for executives planning capital allocation, product strategy, and M&A activity in 2026. The market is sizable and expanding: our top-line model shows the industry moving from an estimated USD 198.75 Million in 2025 toward a substantially larger market by 2032, tracking at a compound annual growth rate of approximately 5.85% through the forecast period. For leaders who need to convert market signals into executable actions, this report synthesizes quantitative forecasting with field-proven decision frameworks, while reserving detailed subsegment matrices for secure access to the full dataset.
Worldwide Steam Dried Fishmeal Market
What the Report Contains — Practical, Transaction-Ready Intelligence
Integrated market model: A time-series revenue model (2020–2025 historical; 2026–2032 forecast) with an embedded scenario-builder that lets users stress-test assumptions (price erosion, unit adoption, service revenues) and export results into CapEx/OpEx planning templates.
Car High Frequency Speaker MarketCommercial playbooks: Vendor assessment matrices, procurement checklists, tender evaluation scorecards, and supply-chain due-diligence templates tailored for public utilities, mining operators, and environmental consultancies.
Tubeless Road Bike Tyres MarketCompetitive intelligence: Confidential profiles of the leading hardware and solution suppliers, including manufacturing footprints, service capabilities, go-to-market models, and recent strategic moves that alter capacity and distribution dynamics.
Technology roadmaps and ROI frameworks: Comparative analysis of imaging modalities (optical HD, thermal, rotary/360 systems, ROV-adapted rigs), data management architectures, and lifecycle cost models that quantify total cost of ownership across deployment profiles.
Regulatory and compliance appendix: Country- and state-level guidance pointers that influence deployment cadence—particularly relevant for environmental and groundwater applications where visual in-situ inspection is an evidentiary requirement.
M&A and partnership heatmap: Identification of consolidation vectors, likely acquisition targets by capability, and partnership archetypes for OEMs, integrators, and service providers.
Why This Matters for 2026 Decision-Making
Two features of the current cycle make 2026 a pivotal year: (1) steady market expansion with compound growth that supports both organic growth and acquisitive strategies, and (2) accelerating demand for higher-fidelity imaging and data integration across multiple end-markets. These dynamics create a narrow window for shaping competitive advantage.
Prioritize clarity on ROI thresholds. Our scenario analysis shows that modest improvements in image analytics and uptime can drive outsized operational benefits for end-users—translating into procurement budgets becoming more favorable to integrated hardware-plus-software offerings.
Time pilots to gain data advantage. We recommend initiating technical pilots in H1 2026 that align product telemetry outputs with customer SCADA and GIS systems. A six- to twelve-month pilot furnishes the data needed to convert pilots into longer-term service contracts.
Use concentration dynamics to guide M&A prudence. With a market characterized by moderate concentration (our CR3 and CR5 metrics indicate meaningful leader shares but room for challengers), strategic acquisitions will be most effective when aimed at capability gaps—software analytics, field-service networks, or specialized depth-capable hardware—rather than simply expanding overlapping product lines.
Competitive Landscape — Who Moves First Wins
The competitive field blends legacy specialist manufacturers, vertically integrated service providers, and adaptive robotics firms. Executives should watch for three types of plays: capability consolidation by traditional OEMs, aggressive market entry by lower-cost manufacturers leveraging trade-show channel activation, and cross-domain extension by ROV and robotics vendors.
Laval Underground Surveys: A long-established player with deep domain credibility in groundwater and geotechnical inspection systems. A notable acquisition in 2023 expanded its installed base and manufacturing scale—creating an incumbent advantage in service coverage and after-sales spare parts. Strategy implication: buyers should expect bundled service offerings and improved lead times from large incumbents, but also potential price compression for commoditized SKUs.
Allegheny Instruments (GeoVISION): Known for a spectrum of customizable borehole video systems, this supplier competes on modularity and fit-for-purpose engineering for monitoring wells and narrow-bore applications. Strategy implication: firms seeking specialized solutions or OEM partnerships will find value in suppliers that emphasize configurability and depth-rated engineering.
Chongqing Gold Mechanical & Electrical: An example of rising suppliers expanding visibility through trade-show participation and international channel development. Strategy implication: established buyers should re-evaluate vendor qualification protocols to balance cost, serviceability, and IP safeguards as new entrants scale exports.
Well-Vu and Deep Trekker: Represent the convergence of digital consoles and robotics with borehole inspection use cases—bringing 4K imaging, operator ergonomics, and remote vehicle platforms into the arena. Strategy implication: platform plays that combine hardware with analytics and remote operation capabilities are likely to capture premium service contracts in safety-critical environments.
Technology Trends That Define Winners and Losers
Through 2032, product differentiation pivots on three axes: imaging fidelity and depth capability; data interoperability and analytics; and field service economics.
Imaging: Advances in high-resolution optics, low-light sensors, and thermal imaging improve defect detection and reduce repeat inspections. Procurement teams should require imaging performance curves and on-site validation protocols rather than raw resolution claims.
Data: The premium is on systems that convert imagery into actionable intelligence—automated pipe-joint detection, sediment quantification, or corrosion indexing—and provide clean export hooks into asset-management systems.
Serviceability: Total cost of ownership is dictated by mean-time-to-repair, modularity of field kits, and the availability of local service technicians. Design for maintainability is no longer optional for players seeking to compete on lifecycle economics.
Regulatory Context and Operational Compliance
Regulatory frameworks increasingly reference the use of downhole visual inspection as a component of environmental and well-management practice. For example, leading authorities recognize borehole video cameras as a means to document interior borehole conditions during assessments, and some states call for documented verification prior to well-sealing activities.
Operational implication: Operators should embed camera-based inspection protocols into permit compliance workflows and contract language. Evidence-grade imagery—timestamped, geolocated, and retained in auditable storage—will be a procurement requirement in many jurisdictions.
Risk mitigation: Establish an internal regulatory playbook, and validate vendor documentation processes as part of supplier qualification to avoid late-stage compliance friction.
How Leading Buyers Should Act in 2026
Segment procurement into three buckets: proof-of-concept, vendor-managed service agreements, and capital acquisitions. Match vendor incentives to deployment risk and technical uncertainty.
Make interoperability a contract KPI. Demand open APIs and standardized output formats to prevent vendor lock-in and to enable cross-system analytics.
Prioritize field trials that integrate hardware, connectivity, and analytics. The path from pilot to enterprise rollout is shortened when trial success criteria focus on operational KPIs (inspection time, repeat rate, and remedial action detection rate) rather than purely technical performance metrics.
Consider bolt-on acquisitions to accelerate capability—software analytics, local service networks, or specialized depth-capable camera modules—rather than greenfield builds when time-to-market is critical.
Using the Dataset — Where to Find the Hidden Details
We deliberately provide high-level market sizing and growth metrics in this overview to guide executive prioritization. The full report and interactive workbook contain the granular segmentation tables, regional and application splits, vendor revenue estimates, and downloadable financial models that most commercial teams ask for when making 2026 investment decisions. These deliverables include:
Scenario-ready Excel model with adjustable ASP, unit mix, and service revenue levers.
Confidential vendor scorecards and sourcing risk heatmaps.
Regulatory annex with jurisdictional checklists that map to documentation and evidence requirements.
Closing Recommendation
For companies planning procurement cycles, product launches, or strategic transactions in 2026, the imperative is clear: act with an integrated outlook that couples high-fidelity field data with commercial agility. The Borehole Camera Market’s projected expansion creates opportunities for differentiated products and service business models—but the advantage will accrue to firms that convert imagery into operational outcomes, secure regulatory evidence chains, and design for lifecycle economics.
To receive the full report, the interactive model, and a customized briefing that translates market signals into a 90‑day action plan for your business, please contact PW Consulting’s industry team. Our dataset is structured to be both a planning tool and a transaction playbook for 2026 and beyond.
For detailed analysis of this topic, please visit the official page:Borehole Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com