
Worldwide Automotive Pneumatic Valve Market — Strategic Preview for 2026
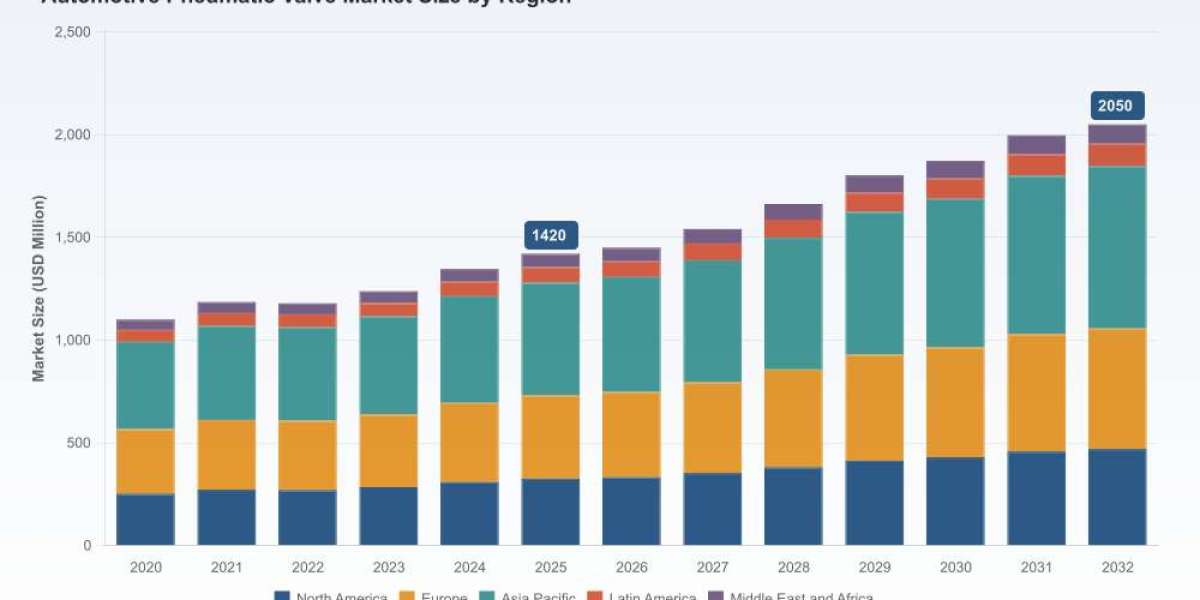
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic briefing drawn from our newly released Worldwide Automotive Pneumatic Valve Market report (base year 2025). The automotive pneumatic valve sector has stabilized after pandemic-era volatility and is entering a phase of steady expansion driven by factory automation, regulatory-driven product re-engineering, and selective consolidation across vendors. Our modeling places the market at USD 1,420 Million in 2025 and forecasts a trajectory to approximately USD 2,050 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.42% across the 2026–2032 forecast window.
Fire Caulks Market
Why this report matters for 2026 decision-making
Timing for capital allocation: With a predictable mid-single-digit CAGR and a clear post-2025 growth runway, procurement and R&D capital can be staged rather than front-loaded. Organizations planning program investments in 2026 should align multi-year budgets with the market’s steady expansion profile to avoid both underinvestment in automation upgrades and overexposure to legacy physical-platform risks.
Angle Beam Transducer MarketRegulatory-driven product cycles: Emissions and safety standards effective from 2025–2026 are reshaping valve requirements. The need for lighter, higher-precision valve assemblies and integrated monitoring for particulate and air-management systems creates a finite window for suppliers to qualify next-generation designs into vehicle platforms slated for production in 2027–2029. Companies that accelerate validation cycles in 2026 will gain privileged design-in opportunities.
Worldwide Post Insulators MarketSupply-chain and material strategy: Raw material volatility (aluminum, stainless and carbon steels) is an ongoing input cost factor. Our actionable scenarios show how hedging, alternative-material substitution, and modular design can protect margin without compromising compliance — strategies that procurement leaders should finalize in early 2026.
M&A and partnership posture: Market concentration metrics indicate meaningful scale advantages among the incumbent top vendors. Buyers and private-equity players should view 2026 as a year to position for bolt-on acquisitions or strategic partnerships to secure modular valve platforms and control-electronics integration capabilities.
Market dynamics and enabling forces
Automation and factory digitization: Manufacturers are accelerating adoption of modular valve terminals, fieldbus-enabled valve I/O, and compact platforms that reduce footprint and commissioning time. These advances shorten line-changeover cycles and directly reduce unit costs in high-volume automotive assemblies.
Regulatory pressure and product re-engineering: The implementation of tighter emission standards in major markets compels both lighter designs and built-in sensing for air management in braking and heavy-duty applications. This trend catalyzes demand not only for new valve content on vehicles but for complementary sensing and diagnostic features.
Consolidation and platform plays: The sector shows increasing strategic activity—product launches, targeted acquisitions, and cross-vendor automation partnerships. These moves are concentrating product portfolios around modular, software-capable valve systems and expanding aftermarket and service offerings.
Materials and cost discipline: As material prices fluctuate, opportunities for design optimization — including hybrid-material architectures and value-engineering of internal flow paths — will be key levers for suppliers to protect margins while meeting OEM weight and durability targets.
Competitive landscape — what leaders are doing
Our competitive analytics profile the strategies of established system suppliers and niche specialists. Incumbents combine product breadth with deep OEM program relationships; specialist players compete on speed, customization and cost. Notable industry moves over the past 24 months illustrate two practical trajectories:
Platform innovation: Vendors are launching modular valve terminals that function as compact I/O hubs to integrate pneumatic control with automation stacks. These platforms accelerate line integration and reduce commissioning complexity, providing an operational advantage to OEMs and Tier‑1 integrators.
Portfolio consolidation: Strategic acquisitions in adjacent compressed-air treatment and pneumatic components are creating broader product suites that can be offered as bundled solutions to vehicle manufacturers and industrial integrators.
Representative vendors profiled in our report include global system players with long-standing OEM channels as well as agile manufacturers focused on customization for vehicle subsystems. Each supplier profile in the full report includes capability maps, program wins, technology roadmaps, and commercial terms benchmarking to support negotiation and sourcing strategies.
Recent market signals (selected)
Product introductions that prioritize modularity and I/O integration for manufacturing automation indicate that line-side value capture is accelerating.
Strategic acquisitions expanding compressed-air and valve portfolios signal a preference for integrated solution offerings rather than single-component supply relationships.
Partnerships between pneumatic component manufacturers and automation platform providers demonstrate an ecosystem approach to shorten design cycles and speed validation into production lines.
Actionable insights and recommendations for 2026
Prioritize qualification of lightweight, sensor-enabled valve variants now: OEMs and Tier suppliers planning program launches in 2027–2029 must complete component qualification and supplier audits in 2026. Delay risks missing vehicle program windows and losing share to qualified incumbents.
Lock in strategic supply agreements with flexibility clauses: Given continued raw material fluctuations, contracts should combine price-protection elements with escalation triggers tied to transparent material indices, preserving cost predictability without sacrificing supply security.
Invest selectively in modular platforms and software integration: Capital directed toward fieldbus-enabled valve terminals and diagnostic-ready assemblies yields operational savings on commissioning and aftermarket service over the mid-term.
Reassess M&A and partnership targets: Buyers should focus on targets that add software-enabled control, compressed-air treatment, or rapid-prototyping capabilities. Sell-side players should highlight recurring-service economics and validated OEM programs to maximize valuation.
Design-for-compliance playbook: R&D organizations should adopt a materials-and-weight reduction checklist tied to emissions compliance scenarios. Cross-functional teams (powertrain, braking, and vehicle-systems) need to converge on valve functional requirements during 2026 to avoid rework costs.
Report contents — what you gain from the full study
Our full report is structured to support both strategic and tactical decision-makers. Key deliverables include:
Market sizing and forecast (2026–2032) with scenario analysis and sensitivity testing to inform budget planning.
Demand-driver decomposition and adoption timelines for new valve architectures, including wear-out cycles, retrofit potential and factory-integration impact.
Comprehensive supplier benchmarking: technology roadmaps, program-level supply exposure, and commercial negotiation playbooks.
Supply-chain risk mapping with mitigation levers: alternative materials, dual-sourcing paths, and supplier near-shoring scenarios.
Regulatory impact assessment that translates Euro/Vendor emissions mandates into component-level engineering and compliance requirements.
M&A and partnership scouting dossiers identifying targets and archetypes most likely to accelerate time-to-market for modular, sensor-enabled valve solutions.
Practical implementation tools: procurement scorecards, supplier RFP templates, and a three‑year action plan for product and process leaders.
Key metrics that frame strategic trade-offs
To ground recommendations, the report consolidates headline metrics: a stable mid-single-digit growth rate (CAGR 5.42% for 2026–2032), an observable progression in absolute market size from the 2025 base year, and concentration dynamics that favor scale but leave niches for specialist suppliers. These metrics should be used as the baseline for portfolio optimization, procurement timing and M&A valuation models.
Next steps — how to use this intelligence in your 2026 planning cycle
For OEMs: Integrate valve-system qualification milestones into vehicle program schedules now; prioritize design-in for lightweight, sensorized assemblies to avoid late-stage rework.
For Tier suppliers: Accelerate platform modularization and software integration efforts to capture line-side savings and strengthen OEM lock-in.
For investors and corporate development teams: Use our vendor scorecards and M&A archetypes to identify targets that close capability gaps in modular valve platforms or expand compressed-air service footprints.
Closing perspective
The automotive pneumatic valve market is transitioning from component commoditization to system-level integration. The period around 2026 represents a hinge point: organizations that act now — aligning procurement, R&D, and M&A — will convert predictable mid-term market growth into sustainable competitive advantage. Our full report provides the granular segmentation, vendor-level intelligence, and deal-ready tools necessary to operationalize the strategies outlined above. For the detailed segmentation, vendor financials, and step-by-step implementation templates, access the complete Worldwide Automotive Pneumatic Valve Market report.
For detailed analysis of this topic, please visit the official page:Worldwide Automotive Pneumatic Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com