
Saddle Chairs Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive preview
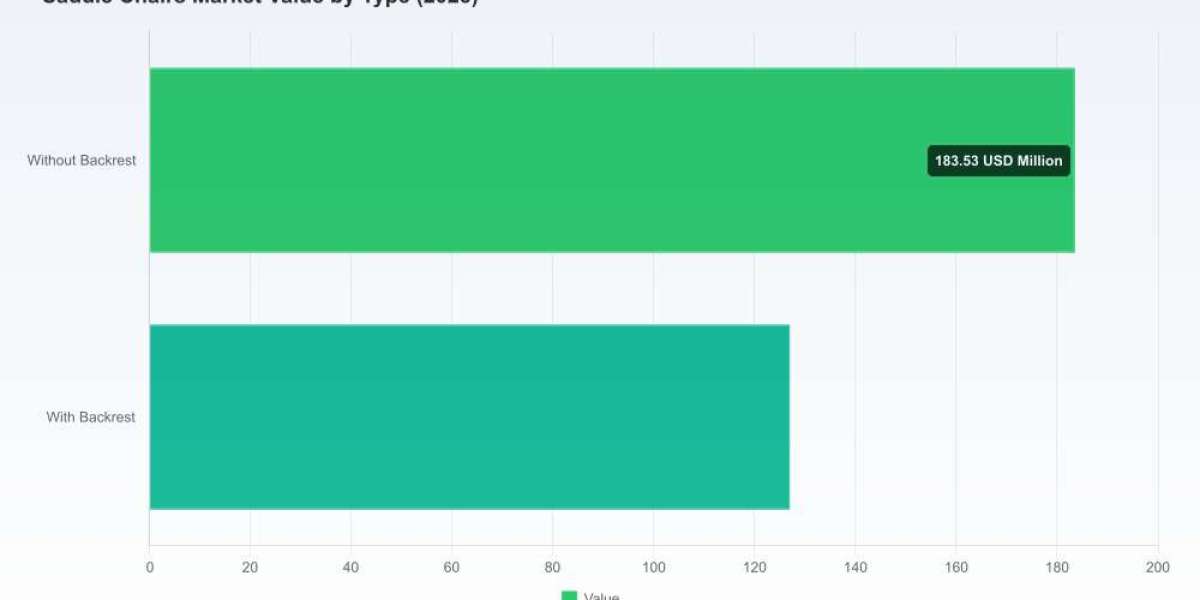
PW Consulting’s latest Saddle Chairs Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) distills the commercially relevant trends that will determine winners and losers over the next investment cycle. The global market has progressed from approximately USD 245.2 Million in 2020 to USD 310.5 Million in 2025, and our model projects continued expansion at a compound annual growth rate (CAGR) of roughly 5.85% across the forecast window, culminating in a materially larger market by 2032. For executives planning capital allocation, product roadmaps, procurement strategies, or early M&A moves in 2026, the patterns summarized here are actionable — while the detailed segment-level datapoints that underpin our scenario work remain available in the full report.
Discoidal Capacitor Market
Why saddle chairs deserve boardroom attention in 2026
Workplace transformation is structural, not cyclical. Hybrid schedules and standing-desk adoption have elevated demand for "active sitting" solutions that bridge seated and standing postures. Saddle chairs occupy a unique ergonomic niche as a complement to sit-stand systems.
Reusable Transport Pack MarketHealthcare and professional services continue to prioritize clinician ergonomics. Dentistry, laboratory work, and certain medical roles demand mobility, patient-proximate postures, and durable, cleanable designs — attributes where saddle chairs frequently outperform generic stools.
Flubendazole MarketIndustrial and technical environments require configurable, ESD-capable seating. Buyers in production and laboratory settings are increasingly sourcing specialty seating tailored to safety and process requirements.
Cost-of-health arguments are moving from HR pilots to procurement criteria: lower musculoskeletal claims, improved productivity, and space efficiency form a compelling TCO case when comparing seating options.
Market dynamics shaping 2026 strategies
Supply-side volatility: In early 2026 the industry confronted polyurethane foam shortages that temporarily pressured cushion lead times and input costs. Procurement teams and product planners must assume recurring raw-material disruptions when stress-testing margins and supplier options.
Regulatory fundamentals: Saddle seating falls under general furniture safety and materials standards; while there were no category‑specific recalls in 2025–2026, compliance and testing are non-negotiable, particularly for healthcare and export markets.
Product innovation and modularity: Differentiation increasingly occurs through adjustability, split-seat ergonomics, ESD-safe variants, and upholstery systems that support infection-control protocols.
Channel evolution: The buyer set spans facilities procurement, dental chains, occupational-health buyers, and direct-to-consumer wellness buyers. Successful players reconcile B2B sales cycles with D2C brand-building and digital education.
Consolidation risk and concentration signals: Market concentration metrics indicate moderate fragmentation. This means larger incumbents can scale distribution advantages, but targeted niche plays remain accessible to agile specialists.
Competitive landscape — strategic positioning of leading players
The category comprises a mix of heritage specialists, ergonomic incumbents, and newer furniture brands. Below is a synthesis of the strategic postures of core competitors covered in our analysis:
Salli Systems (Finland) — Known for split-seat innovation and a strong posture‑health narrative. Salli’s technical differentiation and clinical endorsements give it credibility in healthcare and ergonomics-focused corporate accounts.
Score BV (Netherlands) — Factory-controlled manufacturing with a full product range for offices, factories, and dental clinics. Score’s strength lies in vertical integration and rapid customization for professional buyers.
HÅG (Flokk, Norway) — Leverages iconic design heritage (Capisco lineage) to target dynamic‑sitting use cases in offices and sit-stand environments; brand equity enables premium pricing.
Humanscale (USA) — Applies an industrial-design approach to saddle stools, emphasizing natural movement and ergonomics for office and healthcare customers; enjoys strong design-channel relationships.
Bambach Saddle Seat (Australia) — The original saddle-seat specialist with broad acceptance in dental and professional contexts; its clinical positioning supports stronger penetration in specialist channels.
Treston (Finland) — Targets industrial customers with robust, adjustable, and ESD-ready chairs; benefits from engineered durability and compliance credentials.
Branch Furniture (USA) — Combines design partnerships and sustainable-material positioning to capture modern office and WFH buyers seeking active sitting complements for standing desks.
ProNorth Medical (Canada) — Recent product launches underscore an aggressive push into clinician-focused solutions; the company’s October 2024 saddle stool release signals targeted innovation in medical ergonomics.
RGP Dental (USA) — Specialized dental ergonomics and anatomic design focus make it a go‑to supplier for dental chains and ergonomic consultants.
Recent content and product activity — for example a Score blog (September 2025) advising dental practice layouts and ProNorth’s 2024 launch — reflect how vendors are using content and product refreshes to nudge procurement decisions in professional channels.
What the PW Consulting report delivers (practical, executable content)
Top-down market sizing and scenario-based forecasts (macroeconomic and demand-side sensitivity runs) to inform budgeting, capex, and revenue targets.
Competitive intelligence dossiers: positioning maps, pricing-band heuristics, go-to-market playbooks, and channel economics for leading and challenger firms.
Procurement and supplier‑risk playbook: supplier scorecards, raw-material contingency plans, and contract clauses designed to mitigate foam and component shortages.
Product and portfolio strategy templates: modular architecture options, optionality matrices (backrest, split-seat, ESD, upholstery), and margins-by-configuration modeling.
Regulatory and compliance checklist tailored to healthcare, dental, industrial, and export-context requirements.
Commercial expansion roadmaps for entering adjacent channels (e.g., from dental to clinical labs, or from office to industrial): partner profiles, pilot designs, and KPI dashboards.
Investor and M&A primer: valuation considerations for bolt-on acquisitions, roll-up strategies, and integration playbooks that preserve product innovation.
Strategic actions for 2026 — a recommended playbook
Pursue material diversification: qualify alternative cushion materials and dual-sourcing for foam components to guard gross margins against input-price shocks.
Fast-track clinical endorsements and case studies: quantified TCO and health-outcome evidence accelerates procurement adoption in healthcare and professional service buyers.
Design for modularity: build configurable platforms that allow low-cost optioning (with/without backrest, ESD variants, split-seat modules) to reduce SKUs while addressing multiple segments.
Hybrid go-to-market: combine professional channels (distributors, dental/medical dealers) with targeted D2C education campaigns to capture corporate wellness budgets and ergonomic consumers.
Price and contract agility: implement shorter price-commitment windows and input‑cost pass‑through clauses for large orders to reduce margin leakage during commodity volatility.
Operational resilience: evaluate nearshoring and localized final-assembly cells for industrial and healthcare customers where lead time and compliance matter.
Brand and content investments: use evidence-based content to educate procurement and clinicians; thought leadership accelerates trust in a field that is often skeptical of ergonomic claims.
Pursue tuck-ins to fill channel or capability gaps: small acquisitions that add certification labs, upholstery capacity, or regional distribution can quickly improve competitive positioning.
Consequences of inaction
Delaying decisive action in 2026 risks margin compression from raw-material swings, slower commercial traction as competitors lock key channel partnerships, and missed opportunities where clinical endorsements convert into multi-year procurement agreements. Given the market’s moderate fragmentation, late entrants will face higher customer-acquisition costs and may be limited to lower-margin niches.
How PW Consulting’s research can accelerate your 2026 decisions
The full report provides the granular segmentation, per‑region and per‑application dynamics, and the underlying financial models that drive the strategic recommendations summarized here. We deliberately present a high‑value executive preview to guide immediate decision-making while preserving the actionable segment-level intelligence for report subscribers. Accessing the complete dataset will enable you to stress‑test forecasts against your internal plans, prioritize SKUs for development, and model procurement scenarios under various raw‑material and demand shocks.
Next steps
For procurement and product leaders: request the supplier‑risk annex and materials-sensitivity model to recalibrate 2026 sourcing and pricing plans.
For commercial and BD leaders: obtain the channel-play and use-case playbooks to pilot targeted healthcare and industrial accounts in Q1–Q2 2026.
For corporate strategy and investors: review the M&A primer and consolidation scenarios to evaluate roll-up or partnership opportunities that scale distribution and testing capabilities.
To obtain the full Saddle Chairs Market report and the underlying spreadsheets, contact PW Consulting or visit our report page for subscription options and a sample methodology appendix. The deeper intelligence there contains the exact regional and application splits, scenario workups, and vendor scorecards needed to operationalize the 2026 plays outlined above.
For detailed analysis of this topic, please visit the official page:Saddle Chairs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com