
Etifoxine Hydrochloride Market — Strategic Outlook for 2026 Decision-Makers
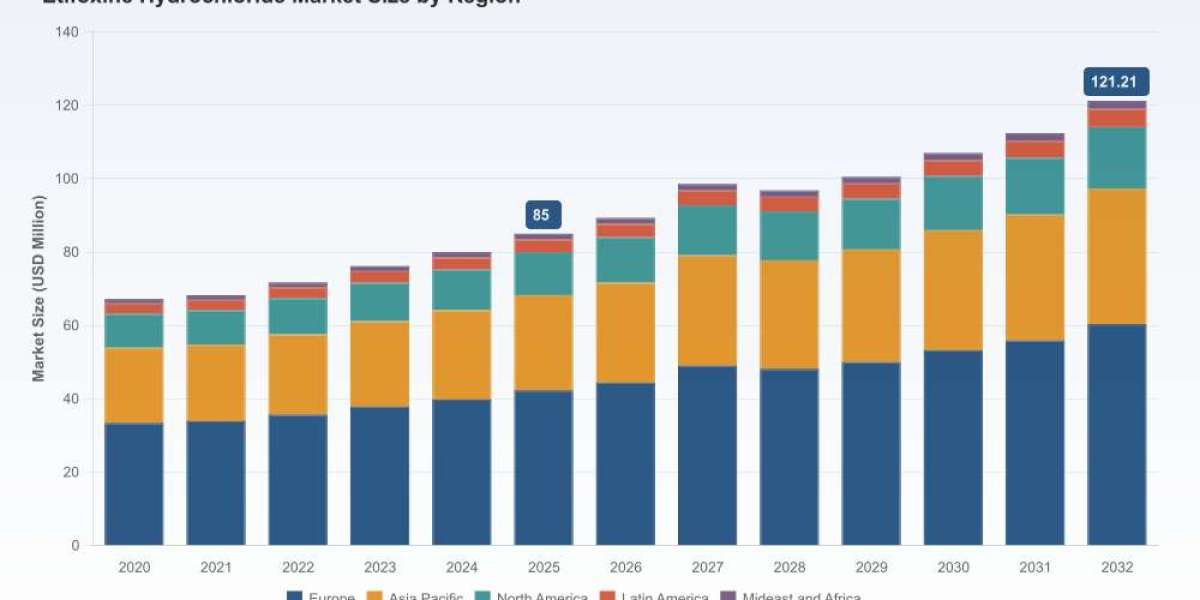
PW Consulting’s latest Etifoxine Hydrochloride Market study is designed as a decision-grade briefing for executives, business development teams, regulatory strategists and investors preparing to act in 2026. Built on a 2020–2025 historical baseline and forward-modeled through 2032, the report synthesizes commercial, clinical and regulatory signals into a compact strategic playbook. At the headline level, the market has grown from roughly USD 67.2 million in 2020 to USD 85.0 million in 2025 and is projected to expand to approximately USD 121.2 million by 2032 — a compound annual growth rate (CAGR) of 5.2% across the forecast window. These macro dynamics frame a market that is mature in certain geographies, but still responsive to product life‑cycle initiatives, regulatory developments and route-to-market shifts.
Worldwide Biomass Refining Market
Why this report matters in 2026
Precision for action: 2026 will be a year when safety labeling, generics entry and clinical repositioning converge to determine commercial outcomes. Our report translates those intersecting forces into prioritised actions (regulatory, clinical, manufacturing and commercial) that can be executed within a 12–18 month horizon.
Worldwide Split AR Glasses MarketRisk-adjusted growth planning: a steady mid-single-digit CAGR masks heterogeneous opportunity and risk across markets and formulations. We provide scenario modelling that converts the headline 5.2% CAGR into actionable revenue and margin implications under conservative, base and aggressive assumptions — enabling CFOs and business unit leaders to stress-test investment cases.
Medical Pure Water System MarketTactical sourcing and supply‑chain playbooks: the market structure presents short‑term supplier leverage and long‑term commoditisation risks. Our supply-side analysis highlights where to secure API capacity, when to pursue forward integration, and how to stage inventory commitments to protect margin while keeping nimbleness for market shifts.
What’s inside the report (practical, executable content)
Market sizing and forward forecast: a transparent model spanning 2020–2032 with scenario levers for pricing, regulatory shocks and clinical readouts.
Commercial playbooks: go-to-market options for originators, branded generics and pure-play generic manufacturers, each with KT (key tasks), resourcing templates, and expected payback timelines.
Regulatory and safety intelligence: implications of recent and historical regulatory decisions for labeling, risk mitigation and market access strategies.
Supply and manufacturing analysis: API and finished-dose capacity maps, qualifying criteria for CDMOs, and a procurement timeline for securing long‑lead ingredients.
Clinical and lifecycle opportunities: prioritized indications, trial design recommendations, and value-capture strategies for repurposing or adjunctive use cases.
Deal and valuation playbook: valuation sensitivities, licensing term templates and an M&A readiness checklist tailored for companies seeking to acquire or divest etifoxine assets.
Dashboards and templates: ready-to-use trackers for post‑marketing surveillance, tender participation, and channel performance.
Competitive landscape — how to read the field in 2026
The market exhibits moderate concentration: the top three players capture less than half of global turnover while the top five approach just under three-fifths, indicating a competitive environment where scale matters but niche strategies can still win. In practical terms, this structure generates opportunities for both well-capitalised regional champions and agile challengers that can exploit local regulatory or distribution advantages.
Biocodex (France) — As the originator marketer of the branded product in multiple countries, Biocodex remains the reference for clinical differentiation and risk communication. Their established brand positioning can be leveraged in markets where clinical familiarity matters to prescribers; at the same time, originator holders must actively manage lifecycle erosion where generics are enabled.
Sun Pharmaceutical Industries Ltd. (India) — Recent regulatory approvals to manufacture and market etifoxine capsules and the initiation of active post‑marketing surveillance exemplify a dual strategy: scale local production and generate safety data to support wider commercialization. For competitors, Sun Pharma’s moves underline the importance of monitoring approvals and post‑market commitments that can accelerate generic adoption in price‑sensitive markets.
Metrochem API & Global Calcium (India) — Supply players in the API space are a strategic lever. Their ability to provide reliable API supply at competitive cost influences both margins and market entry timing. For brand holders, securing API partnerships or long-term offtake agreements can be a defensive tool; for generics players, flexible API sourcing accelerates entry.
Nizhpharm (Russia) — The launch of a first local generic illustrates how national regulatory pathways and local manufacturing can quickly re‑shape market dynamics. Localised generics often compete on availability and price, making geographic strategy and distribution partnerships critical for incumbent brands.
Regulatory and clinical dynamics shaping strategy
Three regulatory and clinical vectors will be particularly influential for 2026 planning:
Safety-driven labeling constraints: European regulatory precedent has reaffirmed etifoxine’s therapeutic role for anxiety disorders while imposing contraindications tied to serious skin reactions and hepatic injury. These constraints influence formulary positioning, local label claims and communication strategies to prescribers.
Market access gaps: Etifoxine is not approved or marketed in some large jurisdictions. Absent US FDA authorization, strategies that rely on broad global roll‑out must be calibrated to jurisdictions where regulatory pathways are accessible and reimbursement mechanisms are aligned.
Clinical repositioning upside: New trials — including those starting to evaluate etifoxine for prevention of chemotherapy‑induced peripheral neuropathy — create potential to expand clinical indications. Early investment in high‑quality, indication‑specific evidence can materially shift commercial prospects and justify premium pricing in targeted uses.
Actionable 2026 playbook — priority moves for executives
Immediate (0–6 months): Conduct accelerated due diligence on API supply; establish or renew contracts with multiple qualified suppliers to limit single‑source risk. Launch a regulatory watch on pending approvals in priority markets and prepare a label risk‑management plan that addresses the known contraindications.
Near term (6–12 months): If you are an originator or a branded manufacturer, deploy targeted post‑marketing studies and real‑world evidence projects to shore up safety perceptions and support differentiated positioning. Generic manufacturers should sequence launches to align with tender cycles and local reimbursement windows.
Medium term (12–24 months): Prioritise clinical programs with the highest ROI — for example, trials that address new indications or demonstrate additive benefits in combination therapies. For players considering inorganic growth, pursue acquisitions that either expand geographic reach or bolt on API/manufacturing capabilities to compress time‑to‑market.
Ongoing governance: Implement a competitor surveillance dashboard keyed to regulatory approvals, product launches and pricing changes. Use scenario planning to model the financial impact of generics entry, label constraints, and successful indication expansion against the 5.2% CAGR baseline.
Use cases — who should read this report
Corporate strategy teams evaluating whether to enter or exit the etifoxine space.
Business development teams sizing licensing or acquisition targets and negotiating term sheets.
Regulatory and pharmacovigilance leads planning label strategy and safety communications.
Manufacturers and CDMOs assessing capacity investments and API sourcing strategies.
Investors and PE firms performing diligence on assets exposed to the neuropsychiatry therapeutic area.
What we intentionally withheld — and why
To preserve the report’s role as the primary commercial product, this briefing omits granular regional and application share tables, detailed pricing matrices, and the full segmentation tables that underpin the model. Those segmentation details (by geography, dosage form and therapeutic use), unit economics and market concentration tables are included in the full report and the downloadable model — they are the levers you will need to convert strategic intent into executable investment plans. This “trailer” approach is intentional: we provide the strategic context, signal the key inflection points, and invite firms to access the full dataset and model to operationalise decisions with confidence.
How to use the PW Consulting report to win in 2026
Start with the modelling workbook: recalibrate your internal forecasts against the report’s base-case and downside scenarios.
Adopt the tactical checklists: use our supplier qualification and post‑marketing surveillance templates as working documents in contract negotiations and safety program planning.
Integrate regulatory intelligence into commercial timelines: line up submissions, label negotiation and launch sequencing to minimise erosion and capture early-adopter share where new indications appear.
Use the valuation sensitivity tables to inform M&A and licensing bids, ensuring bid discipline in a market with moderate concentration and active generic threats.
PW Consulting’s Etifoxine Hydrochloride Market report is engineered to convert macro trends into executable plans for 2026. If your team is facing decisions about manufacturing scale‑up, geographic prioritisation, regulatory engagement or clinical investment, this study provides the data, diagnostics and decision templates required to act with clarity and speed. For full access to the segmented datasets, pricing matrices, regional breakdowns and downloadable financial model, please visit the report page and download the complete package.
For detailed analysis of this topic, please visit the official page:Etifoxine Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com