
Carboxymethyl Tamarind Gum (CMT) Market: Strategic Signals for 2026 — A PW Consulting Preview
As PW Consulting releases its comprehensive market study on Carboxymethyl Tamarind Gum (CMT), this executive preview is designed to deliver the high-value strategic takeaways that senior executives, procurement leads, and corporate strategists need to act decisively in 2026. Drawing on a detailed historical window (2020–2025) and forward-looking forecasts through 2032, the report blends supply-chain forensics, technology-readiness assessment, and competitive intelligence to convert market visibility into executable options.
DTF Pigment Ink Market
Why CMT matters now
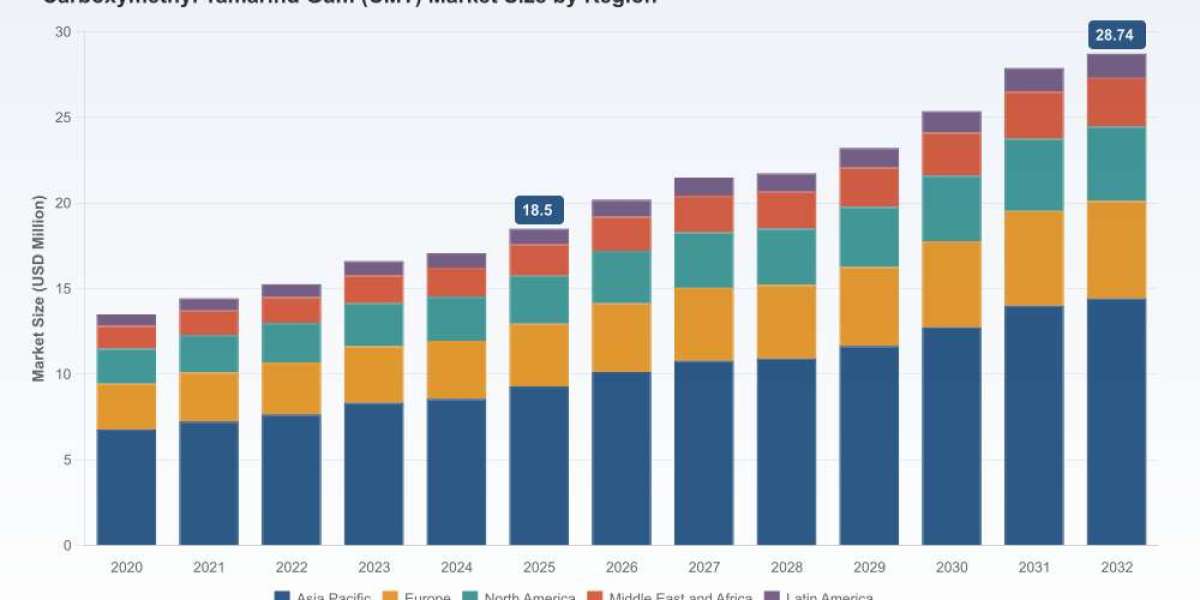
CMT — a chemically modified derivative of tamarind kernel powder — occupies an uncommon convergence point between commodity agricultural supply chains and specialty polymer chemistry. Over the past half-decade the global CMT market has expanded steadily from USD 13.5 Million in 2020 to USD 18.5 Million in 2025, and our model projects continued growth across the 2026–2032 forecast window, reaching roughly USD 28.7 Million by 2032 at a compound annual growth rate of 6.49%. That trajectory reflects both widening industrial demand (textile auxiliaries, paper, adhesives, oil & gas, explosives/mining and emerging personal-care formulations) and incremental value capture through grade differentiation and formulation know-how.
High-Temperature Phenolic Vinyl Ester Resin Market
What the 2026 decision-maker needs to know — top-line dynamics
- Raw-materials architecture: India remains the primary upstream basin for tamarind kernel feedstock, producing on the order of hundreds of thousands of tonnes of tamarind annually. That availability underpins global CMT supply but also concentrates sourcing risk geographically and seasonally.
- Regulatory and compliance environment: Tamarind kernel powder and its derivatives enjoy favorable recognition in major regulatory jurisdictions for non-food industrial uses, a factor that lowers entry friction for formulation changes and cross-border trade. Nevertheless, new product registrations and customer-specific certifications are increasingly table stakes for premium segments.
- Manufacturing complexity: CMT production is not simply a milling exercise — it requires controlled chemical modification (etherification under alkaline conditions) and stringent process controls to deliver reproducible viscosity, charge density, and solubility performance. Manufacturers that combine feedstock security with reproducible chemistry hold a durable technical advantage.
- Demand pull vs. formulation push: Demand is being shaped equally by traditional uses (textile printing thickeners, paper sizing) and by formulators seeking bio-derived, cold-water soluble thickeners for cosmetics and industrial adhesives. This bifurcation creates two commercial plays: volume-focused commodity supply and margin-rich specialty grades.
Competitive landscape — capabilities that matter
The CMT value chain today blends vertically integrated manufacturers, specialty gum houses, and global distributors. Core capabilities that distinguish winners in 2026 include feedstock control, grade customization, stable rheology at target solids, and global regulatory/compliance reach.
Plant-derived Cyclic Peptide Market
- Manufacturing & customization leaders: Manufacturers with deep tamarind processing heritage and laboratory-to-batch translation — exemplified by firms that provide multiple CMT grades with defined cold/hot solubility and pH stability — are positioned to capture both standard and customized contracts. These suppliers can support textile mills, paper converters, and formulators with tailored viscosity profiles and filterability characteristics.
- Quality & specification specialists: Players offering high-viscosity, tightly specified grades with internationally recognizable QC regimes enable formulators to reduce trial cycles and speed time-to-market for new dye systems and adhesive formulations.
- Distribution & market breadth: Global distributors and trading houses that combine logistics reach with regulatory documentation enable smaller producers to access export markets while supporting industrial buyers with flexible lot sizes and just-in-time deliveries.
Our company profiles in the full report map these capabilities against commercial reach, R&D intensity, and customer-service levels. For executives building 2026 supplier roadmaps, the key question is not simply "who produces CMT?" but "who can guarantee consistent rheology and regulatory paperwork while scaling with your demand?"
Segment-level signal without spoilers — where growth originates
Within the CMT market there are observable trajectories that have strategic implications, but this preview intentionally omits granular split data to preserve the report’s value as an operational tool. Directionally, expect:
- Steady base demand from textile and paper applications, buoyed by initiatives to improve wash-off properties and color yield in reactive dye processes.
- Premiumization in grades tailored for personal-care and pharmaceutical adjuvant uses, where cold-water solubility, microbial stability, and sensory neutrality command price premiums.
- Specialty demand spikes tied to industrial niches (e.g., certain drilling-fluid and adhesive formulations) where polymer performance under extremes of pH and temperature matters.
To access the precise segmentation, CAGR-by-application mapping, and regional demand curves that underpin procurement and capex models, the full PW Consulting report provides proprietary tables and decision-ready datasets.
Supply-chain and price risk — what to model in 2026
- Seasonality and concentration: With raw material sourcing concentrated in a limited number of agricultural regions, buyers should model seasonal availability and logistics congestion as a first-order risk to continuity of supply.
- Quality delta risk: Not all CMT is interchangeable. Differences in degree of substitution, particle-size distribution, and residual ash or protein content generate formulation sensitivity. Relying solely on commodity pricing without specification parity can increase scrap and rework costs.
- Regulatory tightening: While current classifications favor industrial use, emerging markets and downstream industries are increasingly requiring supplier transparency, traceability, and certification (e.g., GMP for pharma-adjacent uses). Upgrading supplier qualification systems is a necessary 2026 investment.
- Alternative ingredients: Synthetic and other natural hydrocolloids compete for formulators’ wallet share. The negotiation lever in 2026 will be demonstrating CMT’s unique combination of cold-water solubility and rheological stability at competitive cost-in-use.
Strategic playbook — recommended actions for 2026
Based on cross-functional interviews, supply audits, and our quantitative scenario work, PW Consulting recommends a prioritized set of moves for market participants:
- Buyers — secure tiered supply and spec-based contracts: Move from single-source to multi-tiered agreements that combine a primary long-term supplier with validated secondary suppliers. Contracts should be specification-based (viscosity, solubility, microbial limits) rather than only commodity-weighted.
- Producers — invest in grade differentiation and traceability: Leaders will invest in laboratory-to-manufacturing scale-up and in digital traceability (batch-level quality records) to win premium segments. Consider premium grade playbooks for cosmetics and pharmaceutical supply chains.
- Investors — prioritize technical defensibility: Look for firms with proprietary process controls, robust QC data, and customer lock-in through formulated solutions rather than undifferentiated powder supply.
- Private-label formulators & specialty chemical houses: Source CMT as part of systems — pair it with charge-balancing surfactants or crosslink modifiers to create higher-margin finished goods and reduce direct competition on raw CMT price.
- M&A & partnerships: Tactical acquisitions that secure feedstock or laboratory capabilities can compress time-to-market for new grades. Strategic distribution partnerships help in markets where compliance paperwork and customs handling are barriers.
Practical deliverables inside the full PW Consulting report
For teams preparing 2026 budgets and strategic roadmaps, the full report goes beyond narrative and provides operationally usable content, including:
- Supplier scorecards with audited attribute weightings (quality, lead time, certification readiness).
- Procurement playbooks for transitioning grades and establishing dual-sourcing pipelines.
- Capex decision matrices for capacity expansion with payback timelines under multiple demand scenarios.
- Formulation-risk heatmaps showing where CMT substitution materially changes product performance and compliance exposure.
- Commercial due-diligence dossiers on the industry’s active manufacturers and global distributors, mapping capabilities to target applications.
These resources are designed to be plugged into 2026 planning cycles with minimal translation—a core premise of PW Consulting’s mandate to turn market intelligence into executable moves.
Competitive snapshot: what to watch among suppliers
The market is populated by established manufacturers, regionally strong specialists, and global distributors. Select capability highlights that inform supplier selection:
- Manufacturers with technical depth offer clearly differentiated grades (e.g., high-viscosity grades for synthetic-fiber printing or low-viscosity, high-solubility grades for cold-process cosmetics).
- Regional producers with tamarind processing know-how can offer cost advantages but may require logistics and certification upgrades to serve premium export customers.
- Global distributors provide reach and lot-size flexibility but vary substantially on quality assurance practices; buyers should insist on batch-level documentation when entering long-term contracts.
Our competitive profiles balance public company disclosures, supplier audits, and customer interviews to identify whom to watch for partnership, supply security, or potential M&A targets.
Conclusion — how PW Consulting’s findings shape 2026 choices
For corporate leaders, the central strategic choice in 2026 is whether to treat CMT as a sourced commodity that must be cost-managed or as a strategic input that can be productized into higher-margin offerings. PW Consulting’s forecast shows durable growth and clear pockets of premium demand; the operational levers that capture that upside are supplier qualification, grade-specific R&D, and supply-chain resilience investments.
This preview is intended to surface the decision architecture and priority actions. For the full suite of quantitative tables, segmentation detail, supplier rankings, and transactional playbooks that translate this analysis into executable plans, request the complete Carboxymethyl Tamarind Gum (CMT) Market report from PW Consulting. Our full report delivers the granular data and scenario-ready models that procurement, product, and corporate development teams will need to lock in advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page:Carboxymethyl Tamarind Gum (CMT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com