
Marine Electric Motor Market: A 2026 Strategic Briefing from PW Consulting
As the maritime industry accelerates its low-carbon transition, electric propulsion and on-board electrification are moving from niche trials to boardroom priorities. PW Consulting’s latest Marine Electric Motor Market report — built on historical performance (2020–2025) and forward-looking modelling for 2026–2032 — synthesizes market-scale forecasts, regulatory inflection points, supplier dynamics, and operational playbooks that executives will need to set strategy and allocate capital in 2026.
Semi-solid Aluminum Alloy Market
Why this report matters for 2026 decision-makers
Clear sizing and trajectory: Our baseline benchmarking shows the dock-to-deck market for marine electric motors expanding from a 2025 base to a materially larger market through 2032, driven by both newbuild electrification and retrofit demand. The model yields a forecast CAGR of 12.25% across 2026–2032, reflecting accelerated adoption under recent regulatory and commercial drivers.
Worldwide Submersible Mixers MarketTiming and capital planning: Shipping CFOs and shipyard planners must reconcile multi-year procurement lead times with tightening component supply and evolving standards. The report translates market growth into practical procurement windows and phased capex scenarios calibrated to 2027 regulatory milestones.
Worldwide Isolation and Control Valve MarketRisk-informed supplier selection: With market concentration metrics showing a moderate level of supplier consolidation (CR3 ~38.5%; CR5 ~52.15%), buyers face a trade-off between partnering with scaled incumbents and engaging agile challengers. Our supplier risk matrix and negotiation playbook help buyers manage single-supplier exposure, MOQ constraints, and aftermarket guarantees.
Regulation-to-revenue alignment: IMO policy shifts and SEEMP enhancements are changing the economics of electrification. The report converts regulatory timelines into demand triggers for propulsion-grade motors, auxiliaries, and hybrid systems so commercial leaders can align fleet strategy with compliance-driven retrofit windows.
Key market signals and what they mean operationally
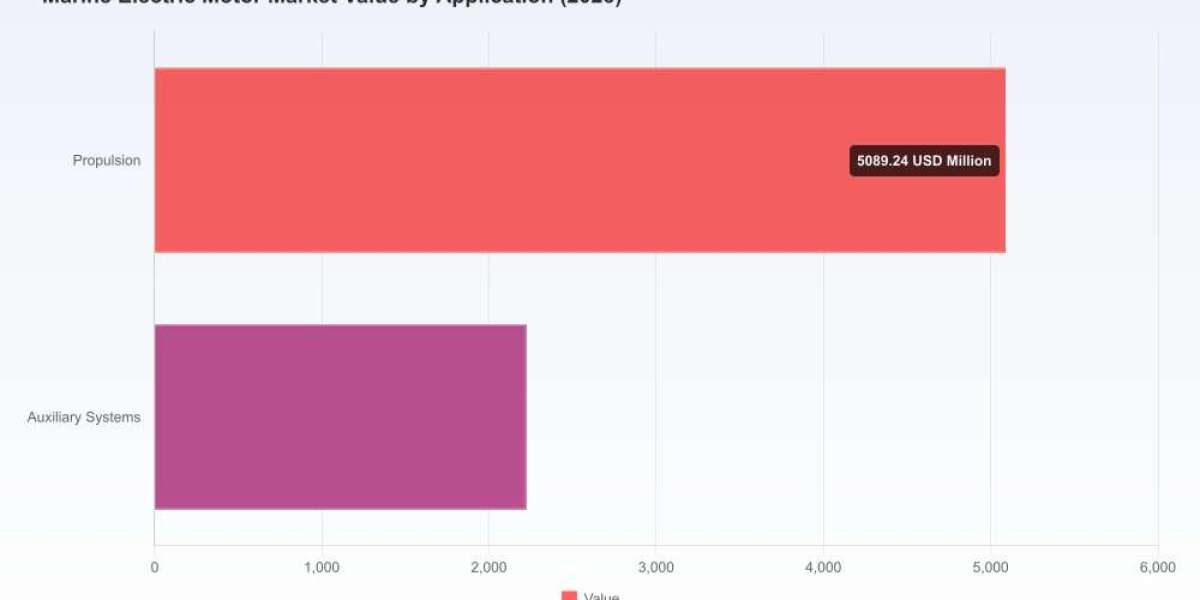
Strong expansion, but differentiated opportunity: The marine electric motor market is no longer a marginal growth story — it is scaling. Our top-line projection shows meaningful growth beyond 2025, creating material opportunity across system suppliers, integrators, and service providers. However, growth is not uniform: propulsion systems, high-power integrated drives, and lightweight outboards present distinct value chains and operational requirements.
Supply-side pinch points: Critical material concentrations — notably rare earth elements used in permanent magnets and accelerated copper demand for electrification infrastructure — create procurement volatility. The report outlines four practical hedging strategies, from long-term offtake contracts and magnet redesign to inventory pooling and qualified-substitute qualification programs.
Regulatory accelerants: The IMO’s recent policy actions create hard deadlines that will catalyze capital expenditure and retrofit cycles beginning in the 2027 timeframe. PW Consulting’s regulatory impact module quantifies likely demand inflection windows and translates them into retrofit-capacity requirements for yards and tier-1 integrators.
Technology and cost trajectories: Advances in motor topology (e.g., permanent magnet and synchronous machines), thermal management, and system-level integration are driving power density improvements and efficiency gains. The report maps technology-readiness levels to TCO outcomes—helping procurement and engineering teams compare lifecycle energy, maintenance, and retrofit implications.
What’s inside the report: practical, executable content
Forecast models and scenario suites: Stated-base and alternate scenarios with demand curves and sensitivity tests around regulatory adoption, raw-material price shocks, and capital-cost improvements.
Executive decision matrices: Quick-reference frameworks to prioritize retrofit vs newbuild investments, with recommended timelines keyed to fleet type and operational profile.
Supplier due-diligence playbook: A structured RFP and scorecard template covering technical fit, production capacity, lifecycle support, certification readiness, and supply chain resilience.
Total Cost of Ownership (TCO) templates: Pre-built models that integrate energy costs, fuel-offset assumptions, maintenance regimes, and residual-value scenarios for electrified systems.
Integration and commissioning checklist: Practical steps and risk mitigations for system integration, testing, and class approval to shorten time-to-service for retrofits and new builds.
Strategic partnerships and go-to-market playbooks: Commercial structures for OEMs, shipyards, and energy providers to accelerate adoption, including leasing, power-as-a-service, and warranty bundling models.
Competitive landscape: leaders, challengers, and where differentiation matters
The market features a blend of established multisector engineering groups, specialized marine electrification firms, and nimble startups. PW Consulting’s competitive analysis synthesizes public positioning, product roadmaps, and commercial strengths to highlight where partnerships, consolidation, or targeted competition are most likely.
Global industrial OEMs: Companies such as ABB (Zurich), Siemens (Munich), WEG (Brazil), and Nidec (Japan) combine scale, integration capabilities, and a broad service footprint. Their value lies in turnkey propulsion systems for larger commercial and offshore vessels and in-situ maintenance networks that appeal to operators seeking minimized operational risk.
Specialist marine OEMs: Players like Ingeteam’s Indar brand (Spain), Torqeedo (Germany), and TECO-Westinghouse (USA) bring deep domain expertise and product portfolios tailored to marine resilience and specific power bands. These suppliers are often first movers on application-specific innovations and provide compelling value for fleets prioritizing proven marine-rated hardware.
Scale-up challengers and innovators: Evoy (Norway), ePropulsion (China/global), Elco Motor Yachts (USA) and others are pushing compact, high-efficiency designs for leisure and small commercial boats. Their innovation cycles and market agility make them attractive partners for fleet electrification pilots and sector-specific rollouts.
Market signals from trade shows and launches: Recent product showcases across 2025–2026 underscore accelerating product pipeline activity — from high-power inboard concepts exhibited at global expos to new outboard families aimed at 2026 commercial launches. These developments point to intensifying competition in the high-efficiency, lightweight segments.
Strategic implications for suppliers and buyers
For suppliers: Scale and integration matter, but differentiation will come from systems integration, aftermarket services, and supply-chain control of critical inputs. Suppliers should prioritize modular architectures, standardized interfaces, and service contracts to capture recurring revenue as fleets electrify.
For buyers/operators: Procurement strategies must evolve beyond price. A balanced supplier portfolio — mixing scaled incumbents for mission-critical assets and nimble innovators for rapid-deployment use cases — will reduce operational risk while capturing performance gains. PW Consulting provides a supplier-selection matrix to operationalize this approach.
For financiers and investors: The market’s expansion and concentration metrics create differentiated investment opportunities across manufacturing, battery and power electronics integration, and aftermarket service platforms. Risk-adjusted returns will favor assets with defensible technical IP and strong service moats.
Risk management: what to hedge, and how
Raw material exposure: The concentration of rare earth production and projected copper market tightness mean procurement teams should implement multi-pronged hedges—contractual, technical (magnet and topology redesign), and inventory—to reduce single-point vulnerabilities.
Regulatory compliance: With IMO policy changes creating hard triggers in the 2027 timeframe, operators should adopt a compliance-first sequencing for vessels above regulatory thresholds. Our playbook includes an actionable itinerary for SEEMP alignment and class approval sequences to avoid operational disruptions.
Operational integration risk: Electrification is a systems problem. Adequate testing regimes, commissioning oversight, and digital telemetry for early detection of degradation are essential. The report’s commissioning checklist and performance baselines reduce retrofit failure modes and unplanned downtime.
How PW Consulting’s report supports your 2026 agenda
Executives face compressed decision windows in 2026: capital allocation, supplier commitments, and retrofit scheduling must be synchronized to regulatory timelines, material availability, and fleet economics. PW Consulting’s Marine Electric Motor Market report provides not only the forecast that frames these choices but also the tactical toolset — scenario models, procurement scorecards, TCO templates, and integration playbooks — to execute with confidence.
We intentionally present a deep strategic aperture while preserving granular subsegment datasets for clients. If your team needs the detailed regional, power band, and application-level analytics, including downloadable excel models and supplier-specific scorecards, access the full report and accompanying client toolkit on PW Consulting’s website or contact your account lead to schedule a briefing.
In short: the marine electric motor market is transitioning from momentum to mainstream. Companies that align procurement discipline, technological strategy, and regulatory-first roadmaps in 2026 will turn structural industry change into competitive advantage.
For detailed analysis of this topic, please visit the official page:Marine Electric Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com