
Turbine Inlet Air Cooling (TIAC) Market — Strategic Imperatives for 2026
As global power systems navigate higher ambient temperatures, tighter operating margins and increasingly volatile fuel and commodity markets, Turbine Inlet Air Cooling (TIAC) has moved from niche retrofit to a core performance lever for gas-turbine operators, independent power producers and industrial consumers. PW Consulting’s latest market research shows the TIAC market expanding rapidly through 2025 into 2026 and beyond: the market grew from the high hundreds of USD Million in 2020 to just over USD 1.07 billion in 2025, is forecast to surpass USD 1.21 billion in 2026 and to approach USD 1.77 billion by 2032, representing a projected CAGR of 7.35% across the 2026–2032 forecast window. For C-suite leaders and asset owners making strategic capital and operational choices in 2026, TIAC is no longer optional — it is a quantified value-driver that requires an integrated investment and procurement strategy.
Infrared Metalens Market
Why TIAC demands executive attention in 2026
- Immediate impact on asset economics — TIAC delivers measurable power augmentation and efficiency benefits that translate into revenue upside during peak load hours and improved dispatch economics over a plant’s operating cycle.
- Timing-sensitive capex — procurement lead times, supply-chain constraints and commodity cost volatility mean that the timing of TIAC investments materially affects installed cost and payback profiles.
- Technology differentiation — evaporative, fogging, mechanical chillers, indirect exchangers and hybrid approaches offer different performance, water, footprint and lifecycle cost trade-offs that must be matched to local ambient and operational constraints.
- Regulatory and standards momentum — industry associations and standard-setting bodies continue to codify best practices for turbine cooling, increasing the importance of compliance and documented performance guarantees.
- M&A and partnership signals — vendor consolidation and strategic acquisitions are accelerating; acquirers and partners should be selective about technology, service capability and aftermarket offerings.
What PW Consulting’s TIAC report contains (practical, decision-ready deliverables)
- Market sizing and forward-looking forecast (2026–2032) with scenario layers for temperature trajectories, fuel prices and load profiles to stress-test payback horizons.
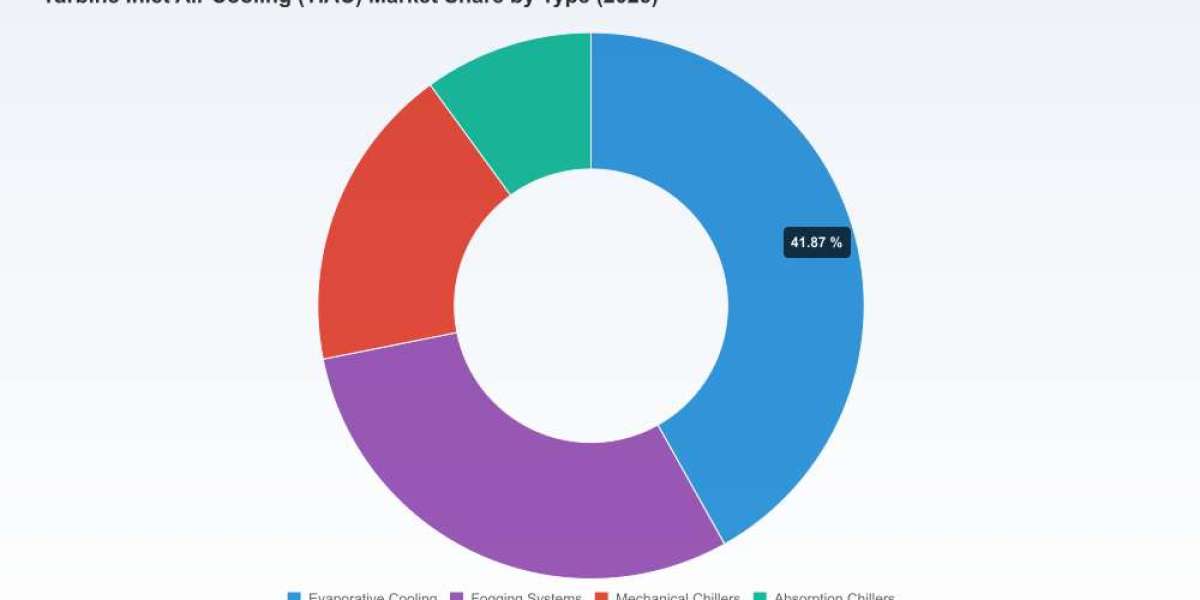
- Technology assessment: comparative techno-economic models for evaporative cooling, fogging/wet compression, mechanical chillers, absorption chillers and hybrid configurations, including sensitivity to water cost and ambient humidity.
- Procurement playbook: RFx templates, scope definition checklists, installation risk matrices and service-level agreement (SLA) frameworks tailored to TIAC projects.
- Vendor benchmarking and vendor due-diligence scorecards that evaluate performance, delivery track record, IP, product modularity, spare-parts maturity and service network readiness.
- Project-level total cost of ownership (TCO) calculators and financial templates (capex/opex, net present value, IRR) for plant-level and fleet-level rollouts.
- Case studies and deployment blueprints that document measured uplift, water/energy trade-offs and commissioning lessons learned across representative climates.
- Regulatory and materials risk assessment, including impacts of commodity cost inflation on uptime, margins and supplier viability.
- Strategic M&A checklist and integration playbook for investors seeking inorganic exposure to TIAC technologies and service platforms.
Market dynamics and strategic takeaways
Demand is being driven by a confluence of operational and macro factors: hotter ambient conditions have increased derating risk for gas turbines, competitive power markets have increased the value of incremental megawatts during peak hours, and grid operators are placing a premium on flexible, dispatchable capacity. Those drivers are counterbalanced by rising input costs for equipment manufacture and increasing scrutiny on water usage and environmental impacts.
Cermet Saw Blade Market
From a structural perspective, the TIAC market is neither highly fragmented nor fully consolidated — a handful of established suppliers lead on technical depth and system integration, while specialised players compete on niche technologies and service models. This structure creates white-space opportunities for differentiated offerings: system modularity, performance guarantees backed by data analytics, thermal energy storage integration, and low-water-footprint solutions command premium positioning.
Lithium Brushless Drill Market
Competitive landscape — what the leading vendors signal for buyers and investors
- Stellar Energy — Known for turnkey TIAC systems with thermal energy storage options that materially improve power output. Their recent acquisition by a major HVAC/energy systems player (completed in early 2026) signals strategic consolidation and the growing importance of hybrid offerings that combine chilling with storage and digital controls. For buyers, ownership by a larger platform increases warranty and lifecycle support potential; for acquirers, it signals where scale and service integration are valued.
- ARANER — Specialises in indirect cooling using heat-exchanger-based approaches and pays particular attention to condensate handling and system reliability. Their engineering-focused profile makes them a preferred partner for sites prioritising water conservation and controlled cooling performance.
- Mee Industries — A market leader in high-pressure fogging and wet-compression solutions; recent industry recognition and thought leadership material demonstrate both product maturity and market traction. Fogging systems can offer rapid, cost-effective augmentation in suitable environments and should be evaluated as a first-cost efficient option where water supply and ambient conditions permit.
- Johnson Controls — Leverages packaged mechanical chiller platforms and containerised systems for fast deployment and proven HVAC heritage. Their product set is attractive for buyers seeking standardized, manufacturer-backed mechanical solutions with predictable commissioning timelines.
- SPX Cooling Technologies, Munters, Camfil, Caldwell Energy — These firms represent specialised capabilities across evaporative cooling, fogging, filtration and system integration. Their presence underscores the fragmented technology stack within TIAC and highlights the importance of supplier integration capability for turnkey outcomes.
Recent vendor developments reinforce these market dynamics: award recognition for fogging technologies and association-level endorsements continue to validate performance claims; strategic acquisitions are consolidating capability stacks and expanding service footprints. These signals should influence vendor shortlists and negotiation posture in 2026.
Recommended 2026 strategic playbook (actionable steps)
- Prioritise pilots before fleet rollouts — run 6–12 month field pilots in representative ambient conditions to validate uplift, water consumption and control integration.
- Adopt a hybrid evaluation framework — benchmark evaporative/fogging, mechanical chillers and indirect cooling against a common set of KPIs (power uplift per degree, water use intensity, installed footprint, lifecycle O&M).
- Lock in long-lead components early — mitigate commodity-driven cost pressure by prioritising procurement windows and negotiating indexation clauses for steel/aluminum-sensitive items.
- Design for modularity and serviceability — favour containerised and modular systems that reduce on-site civil scope and accelerate commissioning.
- Negotiate performance-based contracts — structure EPC and service agreements with measured performance guarantees, shared-savings models or availability-based fees to align vendor incentives.
- Plan for water resilience — where water scarcity or regulation is a concern, prioritise low-water and indirect-cooling solutions and include water-risk clauses in procurement contracts.
- Prepare an M&A watchlist — target vendors with proven thermal storage integration, strong digital controls and a recurring-service revenue profile for acquisition or partnership.
- Integrate TIAC impacts into dispatch economics — update short- and long-term dispatch models to reflect TIAC-enabled capacity and efficiency changes so ranking and bidding strategies capture the incremental value.
How PW Consulting’s intelligence supports 2026 decision-making
Our TIAC report is structured to move executives from strategic intention to executable decisions. We combine market forecasts and scenario planning with project-level financial models, a vendor scorecard library, RFx templates and implementation blueprints. Critically, the report’s sensitivity analyses isolate the variables that matter most to payback and risk (ambient humidity, fuel price, water cost and commodity inflation) so that procurement and operational choices are evidence-based rather than anecdotal.
In keeping with our “trailer” approach, this brief sketches the contours of opportunity and risk without disclosing granular company- or subsegment-specific revenue splits. PW Consulting’s full report contains the complete regional, technology and application breakdowns, detailed vendor revenue and market-share tables, downloadable financial models and the full list of sources and assumptions — all of which are essential for transaction-grade decision-making.
Next steps — decisive actions for 2026
- Download the full report or contact PW Consulting for a tailored briefing to get the complete subsegment data, vendor scorecards and the TIAC TCO models you need to finalise 2026 capex and M&A plans.
- Initiate a cross-functional TIAC task force (operations, engineering, treasury and procurement) to convert insights into an investment roadmap within the current budget cycle.
- Schedule vendor proof-of-concept engagements now — lead times and competitive dynamics mean that pilot slots and factory acceptance test windows are filling for 2026 deployments.
PW Consulting’s TIAC market intelligence equips executives with the market context, practical tools and vendor insight to make confident 2026 decisions. For the full dataset, proprietary models and the actionable annexes referenced above, please access the complete report through our official release portal.
For detailed analysis of this topic, please visit the official page:Turbine Inlet Air Cooling (TIAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com