
Baical Skullcap Extract Market 2026: Strategic Imperatives from PW Consulting’s New Sector Brief
PW Consulting’s latest industry brief on the Baical Skullcap Extract market synthesizes five years of historical data and a seven‑year forecast to deliver actionable intelligence for corporate strategists, procurement leaders, and investment teams planning for 2026 and beyond. The global market reached USD 645.5 Million in our base year (2025) and—under a baseline scenario—is expected to expand at a compound annual growth rate (CAGR) of 6.45% through 2032, crossing the high‑single‑hundred million mark by the end of the forecast horizon. This release is a strategic “trailer”: it demonstrates the analytical depth that underpins PW Consulting’s full report while reserving segment‑level tables and primary‑data annexes for subscribers and paying clients.
Antibiotic Free Meat Market
Why this brief matters for 2026 decision cycles
Strategic timing: 2026 is a pivot year for many players in botanical ingredients. Macro demand drivers—expanding nutraceutical lines, renewed pharmaceutical interest in bioactive flavonoids, and premiumization in cosmetics—intersect with supply‑side shocks that materially affect margin envelopes and sourcing strategies. The market’s steady headline CAGR masks important short‑term volatility that can create both opportunity and downside for firms that move early.
Debonding and Cleaning All-In-One Machine MarketRisk concentration: The market exhibits a mid‑tier concentration where the top three players control a meaningful share of commercial supply and the top five approach majority influence. That structure creates clear competitive advantages for vertically integrated producers and exposes buyers to supplier consolidation dynamics that can compress availability windows for high‑purity grades.
Worldwide Solid Potassium Hydroxide MarketOperational choices become strategic choices: Procurement decisions in 2026—whether to lock multi‑year raw material contracts, build finishing capacity closer to end markets, or pursue toll‑manufacturing partnerships—will determine P&L outcomes over the next market cycle. This brief highlights the structural levers that shift bargaining power between upstream farms, extractors, and brand‑owners.
What the PW Consulting report delivers (practical, transaction‑ready outputs)
Supply‑chain maps and supplier due diligence playbooks: end‑to‑end flow charts from cultivation zones through extraction and finishing, with a layered risk framework for crop, processing, and trade policy exposures.
Price‑and‑margin modeling templates: dynamic models that stress test raw‑material shocks, extraction yield improvements, and quality‑mix changes to quantify margin sensitivity across business models (toll, contract manufacturing, proprietary finished goods).
Regulatory and compliance roadmaps: practical checklists for dossiers and certifications relevant to pharmaceuticals, nutraceuticals, cosmetics, and food applications—useful for global market entry and product relaunches.
Formulation and product‑innovation briefs: evidence‑based guidance on high‑purity versus full‑spectrum positioning, suggested co‑ingredients, and stability/compatibility considerations for manufacturers developing finished formulations.
M&A and JV screening filters: prioritization criteria and red‑flag matrices to support bolt‑on acquisition scouting, partnership structuring, and integration planning with real‑world case templates.
Key market dynamics: what is shaping supply and demand
Raw material geography and climate risk: Cultivation of Scutellaria baicalensis remains concentrated in core Chinese provinces, and climatic volatility—droughts, unseasonal rains—has increased supply variability. PW Consulting’s scenario analysis quantifies how yield swings translate into finished‑product availability under different inventory and processing buffers.
Policy and trade sensitivity: Agricultural policy changes and export regulations in producing countries can rapidly alter spot availability. The report provides a decision tree for supply‑risk mitigation, including alternative sourcing corridors and contractual mechanisms to hedge export‑driven interruptions.
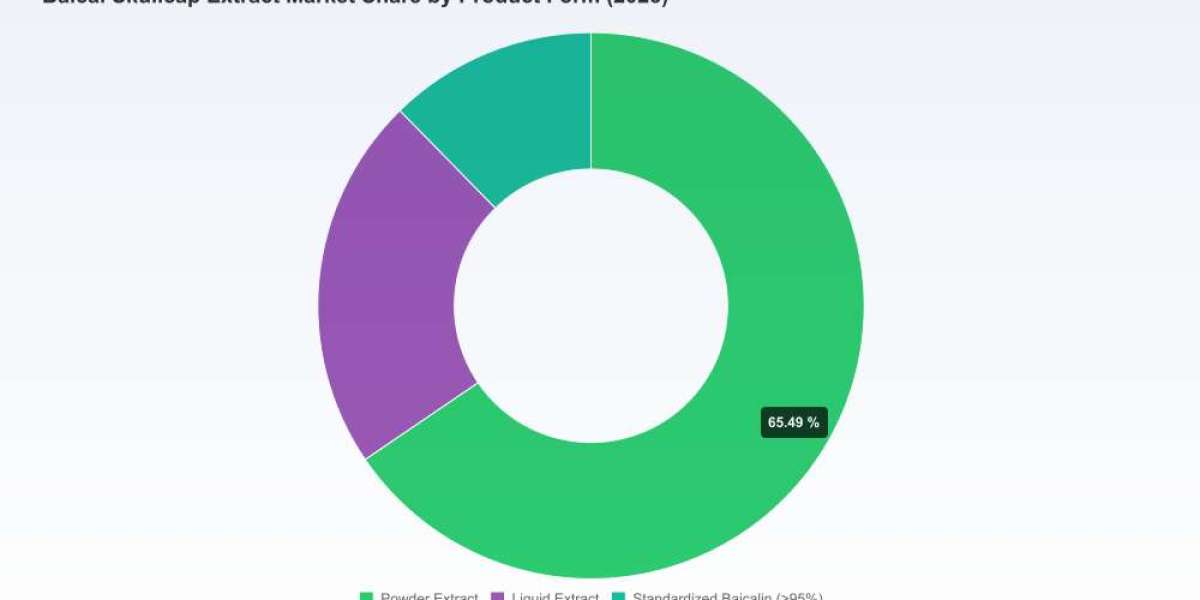
Product quality segmentation: Market demand is bifurcating between commodity powder extract volumes and premiumized standardized high‑purity fractions used in regulated applications. This creates margin stratification and an opportunity for companies that can assure repeatable high‑purity production at scale.
Consolidation vs. fragmentation: With a competitive landscape where the leading few command a significant share and a long tail of regional suppliers serving local demand, buyers are negotiating between reliability and cost. The full report decomposes the value chain to show where integration or diversification provides the most durable advantage.
Competitive landscape — what leading suppliers are doing
PW Consulting’s analysis profiles established manufacturers, niche specialists, and North American bulk suppliers to reveal the strategic plays that define commercial success. Examples include:
Manufacturers with deep extraction capability and regulatory pedigree that leverage GMP and international ISO accreditations to supply pharmaceutical and veterinary customers. These firms’ scale, proprietary extraction patents, and compliance certifications make them preferred partners for regulated demand streams.
Quality‑focused suppliers that emphasize seasonal sourcing from premium root harvests and deliver a spectrum of standardized strengths tailored for nutraceuticals and cosmetics—these players monetize traceability and COA transparency through premium pricing and private‑label programs.
Small‑to‑medium extraction houses and specialty biotech firms that specialize in high‑purity fractions and contract R&D for novel formulations. Their value sits in technical differentiation and flexibility for small‑batch or custom projects.
Importers and U.S.‑based distributors that combine year‑round availability claims with compliance checks (organic, Kosher, Halal) to serve formula houses and finished‑goods brands requiring consistent supply chains with western QA frameworks.
PW Consulting’s profiles also include operational insights—capex intensity of high‑purity extraction, typical lead times by product form, and contract terms to expect from different supplier archetypes. Importantly, the brief contrasts these competitive positions against concentration metrics that show the landscape is neither fully consolidated nor atomized: scale matters, but nimble specialists retain critical niches.
Practical recommendations for corporate leaders in 2026
Procurement and sourcing: Begin 2026 by stress‑testing existing supplier contracts under two downside scenarios—crop failure and policy restrictions. Immediately develop secondary sourcing lists and an inventory policy calibrated to a 6–12 month supply cushion for critical grades.
Product and portfolio strategy: For brand teams, differentiate between mass‑market formulations and premiumized, high‑purity SKUs. The willingness of end consumers to pay depends on both proven efficacy claims and traceability—invest in third‑party testing and transparent supply narratives.
M&A and partnerships: Target acquisition and JV candidates that provide either upstream feedstock control or proprietary extraction technology; these are the two fastest ways to de‑risk margin compression and secure higher‑purity supply.
Regulatory preparedness: Maintain a proactive compliance calendar—especially for markets with heightened scrutiny of herbal combination products. The report includes a regulatory readiness checklist tailored to North America, Europe, and key APAC jurisdictions.
FAQ and reputational considerations
Safety and public perception: Historical product safety incidents involving combination herbal formulations have influenced regulatory and consumer vigilance. PW Consulting’s FAQ section in the full report summarizes the antecedent cases, public health actions, and best practices for pharmacovigilance and consumer communication to protect brand equity.
Traceability questions: The briefing outlines a pragmatic path from farm‑level verification to lot‑level COAs, balancing cost against risk reduction for different classes of end products.
How to use the full PW Consulting report
The document behind this press briefing contains full quantitative annexes, sensitivity models, supplier scorecards, and commercial due‑diligence templates that executives can operationalize immediately. We intentionally withhold granular segment revenue tables and region/application splits in this public summary to protect proprietary market constructs that subscribers receive. If your 2026 plan requires line‑item forecasts, supplier threat matrices, or an M&A short‑list, the complete report provides those deliverables with client‑ready charts and editable financial models.
Next steps
For procurement teams: request the supplier scorecard module and a tailored risk simulation for your purchase profile.
For R&D and product teams: commission the formulation brief that maps purity grades to application outcomes and regulatory pathways.
For corporate development: engage PW Consulting for a rapid target screen and deal thesis for upstream integration or strategic partnerships in the supply chain.
PW Consulting’s Baical Skullcap Extract market brief is intentionally concise here—rich in strategic insight but selective in public disclosures. Contact us to access the full dataset, proprietary models, and tactical playbooks that will help your organization convert 2026 uncertainty into competitive advantage.
For detailed analysis of this topic, please visit the official page:Baical Skullcap Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com