
5 Sulfoisophthalic Acid Monosodium Salt Market: Strategic Preview for 2026 Decision Makers
PW Consulting’s latest market intelligence on the 5 sulfoisophthalic acid monosodium salt (5‑SSIPA/NaSIP) market provides an essential, action‑oriented briefing for corporate strategy, procurement, and R&D leaders preparing plans for 2026 and beyond. This briefing distills the report’s most consequential signals — the market’s health, structural constraints, regulatory inflections, and vendor strategies — while intentionally withholding granular segment figures so that senior decision makers are guided to the full report for executable detail.
Solenoid Valves for Automotive Market
Macro snapshot: stable growth, recovery complete, runway to 2032
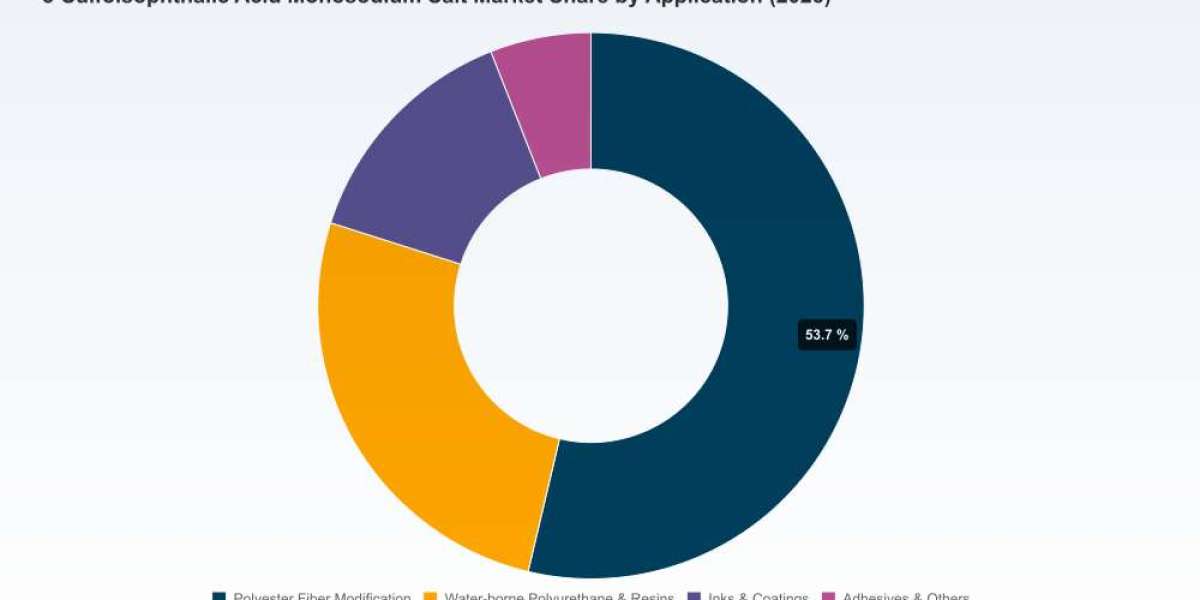
After a period of volatility in the early 2020s, the NaSIP market has re‑anchored. On a consolidated basis the market reached approximately USD 397.26 Million in our base year (2025) and is expected to grow at a compound annual growth rate (CAGR) of 5.15% through the forecast window. By the end of the forecast horizon the market is projected to exceed USD 560 Million, reflecting steady demand expansion driven by polymer modification and waterborne coating formulations. The historical series (2020—2025) shows a resilient recovery trajectory that underpins the confidence in mid‑single‑digit growth for the coming strategic planning cycle.
Worldwide 3D Polyamides Market
Why this matters for 2026 strategic planning
- Investment timing: the market’s steady CAGR signals that incremental capacity and capability investments should be paced to address predictable mid‑term demand rather than expecting immediate step‑change growth.
- Procurement design: with a moderate level of supplier concentration (CR3 ~48.5%; CR5 ~62.3%), buyers must balance supplier consolidation benefits against single‑source risk, especially where specialty grades and regulatory approvals are differentiators.
- Product and R&D roadmaps: applications that drive demand — notably polymer modifiers and waterborne chemistries — favor higher purity and function‑specific grades; 2026 product roadmaps should prioritize formulations that exploit NaSIP’s sulfonate functionality for dyeability, dispersion and adhesion.
- Regulatory and market access: the inclusion of monosodium 5‑sulfoisophthalate in the U.S. FDA inventory for food contact substances creates near‑term commercial opportunities in adhesives and flexible packaging, subject to application‑level approvals and supply chain traceability.
Market dynamics & supply chain realities
Two structural dynamics bear repeating for corporate leaders: feedstock/process risk and grade‑driven differentiation. Technically, production is built around sulfonation followed by hydrolysis, neutralization and controlled crystallization — a sequence that makes upstream sulfonation capacity, alkali availability and energy inputs critical cost and continuity levers. The typical neutralization step at elevated temperature (roughly in the low‑to‑mid 90s°C range per patent literature) means plants must manage thermal control and corrosion‑resistant materials, which favors incumbent producers with established process know‑how.
Worldwide Cerebral Folate Deficiency Market
On the product side, market demand bifurcates around industrial grades and high‑purity grades. Industrial applications (e.g., modified saturated polyesters, general resins) tolerate broader impurity bands and larger packaging/logistics footprints, while high‑purity material is essential for specialty polyester copolymers, waterborne polyurethane dispersions, and applications with stringent regulatory pathways (including some food contact uses). This grade split creates margin dispersion: producers able to certify and consistently supply ≥99% material command premium pricing and require targeted quality systems and analytics.
Regulatory signal: food contact listing and its strategic implication
An important regulatory inflection is the listing of monosodium 5‑sulfoisophthalate in the U.S. FDA’s Inventory of Food Contact Substances. While the listing does not automatically green‑light every food packaging application, it reduces the regulatory friction for adhesives and coatings manufacturers that source NaSIP for indirect food contact applications. For 2026, companies in adhesives, flexible packaging and coating supply chains should: (1) audit formulations and supply chains against FDA listing scopes, (2) prepare dossiers and application‑specific migration data where needed, and (3) consider supplier qualification metrics that explicitly confirm compliance, traceability, and change‑control practices.
Competitive landscape — what to watch in 2026
The supply base features a mix of regional manufacturers and specialty chemical producers. Key suppliers include players with established high‑purity offerings and multi‑channel distribution, alongside regional producers serving local end‑markets. Competitive attributes that distinguish winners are technical service capability, reliable high‑purity production, regulatory approvals, and logistics footprint for water‑sensitive lead times.
- FutureFuel Corporation (U.S.): Positions itself as a high‑purity monomer supplier for polyester and polyamide value chains, with product forms and packaging options tailored for both lab‑to‑commercial scale customers. Strategically, FutureFuel is attractive for buyers that need technical collaboration on polymer synthesis and small‑lot high‑purity supply.
- GO YEN CHEMICAL (GYC Group, Taiwan): Offers ≥99% material and has targeted use cases including cationic dyeable polyester and FDA‑approved adhesive channels. GYC’s combination of high‑purity product and regulatory positioning makes it a preferred partner for customers pursuing food‑contact and premium textile dyeability projects.
- Maruti Chemicals (India): Regional supplier offering high‑purity crystalline NaSIP with strong relevance to printing ink and textile resin markets. Maruti’s cost and geographic advantage make it a logical fit for high‑volume industrial applications in adjacent regional markets.
- Chung Hwa Chemical (Taiwan): Focuses on aqueous polyester resins and PU dispersions, highlighting capability in amine‑free, waterborne systems — a theme aligned with sustainability trends. Chung Hwa’s specialization signals partnership value for formulators shifting toward low‑VOC aqueous systems.
From a competitive intensity perspective, the market’s CR3 and CR5 metrics (approximately 48.5% and 62.3%, respectively) indicate moderate concentration: a handful of firms meaningfully influence supply and pricing yet there remains room for regional entrants and downstream customers to negotiate. This structure favors strategic contracting (multi‑tiered agreements, volume options, and quality penalties) rather than simple spot purchasing or race‑to‑lowest‑cost sourcing.
What the PW Consulting report delivers to practitioners
Our full report is designed as an operator’s toolkit for 2026 decision cycles. Key deliverables include:
- Verified market sizing and a 2026–2032 forecast with scenario sensitivities and demand drivers by application cluster and region (note: granular split tables are included in the full report but are not excerpted here).
- Supply chain mapping and process risk assessment highlighting bottlenecks (sulfonation capacity, alkali supply, crystallization capacity), with mitigation playbooks.
- Supplier scorecards and an RFP template tailored to grade, regulatory compliance, and lead time metrics — enabling rapid qualification of strategic partners.
- Regulatory matrix detailing food‑contact pathways, documentation checklists, and a migration‑testing roadmap linked to common adhesive and coating formulations.
- Commercial benchmarks and margin modeling: pricing bands by grade, packaging and logistics cost drivers, and a sensitivity model for raw material and energy shocks.
- M&A and JV screening: target profiles, valuation heuristics, and integration checklists where buyers look to secure high‑purity capacity or regional footprint.
- Practical templates — NPV calculators, contract clauses to manage specification drift, and a 90‑day supplier stabilization playbook for rapid scale‑up scenarios.
Six strategic imperatives for 2026
- Prioritize dual‑sourcing for high‑purity grades: secure at least two qualified suppliers for any application where purity drives function or regulatory approval.
- Invest in upstream visibility: require suppliers to share process flow diagrams and key process parameters as part of qualification to reduce process‑shift risk.
- Embed regulatory gating into product roadmaps: if pursuing food contact or high‑value textile markets, align R&D timelines with dossier preparation and supplier traceability upgrades.
- Use long‑form commercial agreements with price adjustment collars: the supply base’s moderate concentration recommends balancing term agreements with flexibility for energy/input‑driven cost swings.
- Consider bolt‑on acquisition or strategic JV in Asia Pacific for capacity and proximity to growth markets — but evaluate integration complexity around quality systems and analytics readiness.
- Leverage sustainability as differentiation: prioritize producers demonstrating low‑impact sulfonation processes and energy‑efficient crystallization to meet buyer ESG thresholds.
Closing perspective
For companies planning 2026 investment, procurement, or product development cycles, NaSIP represents a market with dependable mid‑term growth, meaningful grade‑driven margin pools, and regulatory upside in targeted adhesive and packaging applications. The strategic question is no longer “if” to engage — it is “how” to structure partnerships, investments and product strategies to capture the value without over‑exposing to feedstock and process risks.
PW Consulting’s complete 5 Sulfoisophthalic Acid Monosodium Salt Market report provides the full data, scenario models, supplier benchmarking and executable templates necessary to finalize 2026 capital and commercial plans. For the granular segmentation, supplier scorecards, and the actionable playbooks referenced here, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page:5 Sulfoisophthalic Acid Monosodium Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com