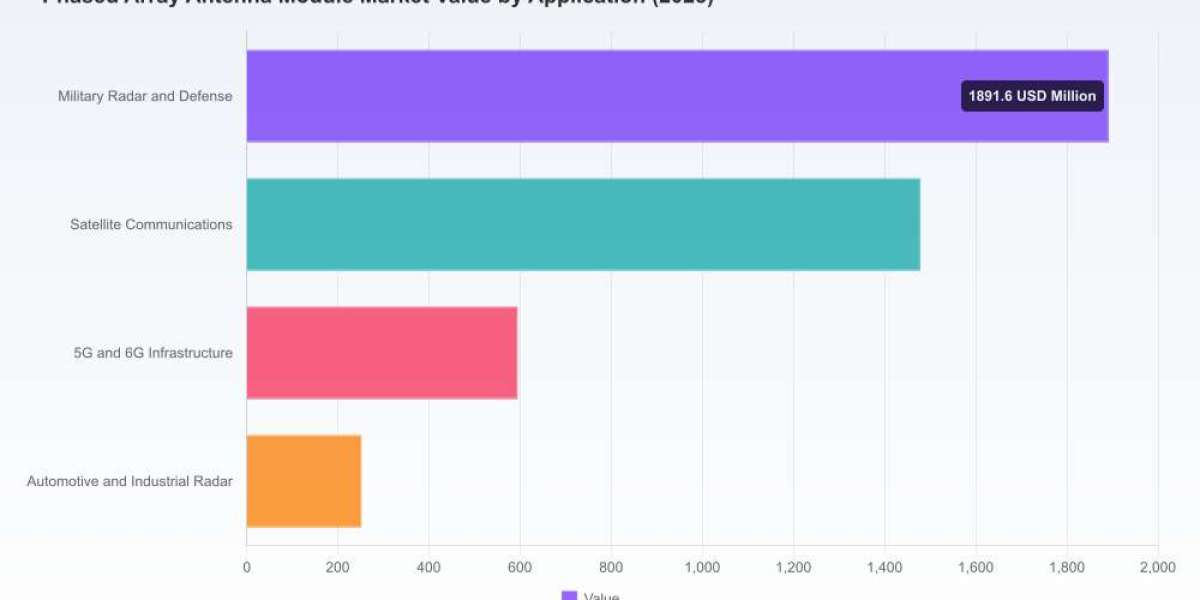

Phased Array Antenna Module Market: Strategic Imperatives for 2026 Decisions
PW Consulting today releases an executive briefing drawn from our forthcoming Phased Array Antenna Module Market research report — an operationally focused intelligence package designed to inform critical commercial, procurement, and investment decisions in 2026. The market is entering a period of rapid expansion driven by defense modernization, satellite broadband proliferation, and the commercialization of advanced RF semiconductors. Our analysis shows the sector scaling from a mid-single‑billion-dollar base in 2025 to a materially larger industry by the end of the decade, with a compound annual growth rate (CAGR) of 17.15% over the forecast period. This briefing highlights the strategic takeaways that senior executives and portfolio managers should weigh now, while reserving the full granularity and segmented forecasts for the full report.
Asphalt Repair Equipment Market
Why 2026 Is a Strategic Inflection Point
Several converging vectors make 2026 a make-or-break year for players across the phased array value chain. First, defense procurement cycles and high‑visibility naval and ground radar programs continue to accelerate modernization efforts, creating predictable demand lanes for active electronically scanned arrays (AESA) and associated transmit/receive (T/R) modules. Second, the rapid maturation of satellite constellations (LEO/MEO/GEO hybrid strategies) has catalyzed renewed investment in electronically steerable antennas for mobile and fixed SATCOM. Third, semiconductor innovation — notably wider adoption of GaN on silicon and higher integration RFICs — is enabling smaller, higher-power density modules that alter product economics and system architectures.
Fully Automatic Block Forming Machine Market
Our market model places the industry at USD 4.22 billion in 2025 (base year), rising to an expected USD 12.77 billion by 2032 under our central forecast scenario. That trajectory underpins a 17.15% CAGR that has large strategic implications: firms that secure supply-chain resilience, accelerate high-volume manufacturability, and demonstrate systems integration capability will capture outsized share as the market scales.
Metrology Calibration Equipment Market
What This Report Gives You: Actionable, Executable Intelligence
- Strategic market sizing and scenario analysis calibrated to program timelines, commodity cycles, and regulatory risk vectors — enabling CFOs and strategy leads to stress-test revenue projections and capital plans.
- Go-to-market playbooks for technology suppliers, OEMs, and system integrators, including product positioning, pricing levers, and tiered channel strategies tailored for defense, SATCOM, telecom infrastructure, and mobility use cases.
- Vendor benchmarking with a practical supplier evaluation framework (technology maturity, manufacturability, systems integration, and export controls) designed for procurement and M&A diligence teams.
- Supply-chain and manufacturing operational guidance covering critical components (GaN/GaAs RFICs, beamformer ICs, ceramics and packaging) and mitigation measures for semiconductor volatility and raw-material constraints.
- Regulatory and geopolitical impact assessments that translate ITAR, EAR, tariffs, and rare‑earth exposure into actionable mitigation pathways for international partnerships and localization strategies.
- Technology roadmaps mapping the migration from passive to highly integrated active architectures, the economics of GaN-on-Si adoption, and the implications of digital beamforming and mmWave scaling across applications.
Competitive Landscape: Who Matters and Why
The market remains moderately concentrated: the top three suppliers command a meaningful share of high-end aerospace and defense demand, and the top five extend that dominance into adjacent commercial and SATCOM segments. This concentration favors incumbent prime contractors with deep systems-integration credentials and established defense relationships, but it simultaneously opens windows for specialized component suppliers and disruptive entrants that can demonstrably lower cost-per-beam or enable new mobile use cases.
Key strategic archetypes we identify in the sector include:
- Prime systems integrators with defense-first portfolios and program-of-record advantage — exemplified by companies offering mature AESA radar systems with modular architectures and large-scale procurement wins.
- Component and semiconductor leaders that drive T/R performance and integration economics via GaN and beamformer IC portfolios, whose roadmaps determine module-level step-changes in size, weight, power and cost.
- Innovative SATCOM-focused OEMs delivering flat-panel electronically steered arrays and metamaterial-based architectures aimed at commercial mobility and enterprise broadband markets.
- Specialized mid‑tier suppliers and regional champions that fill localized production and compliance gaps, often enabling non-US customers to access advanced capabilities while navigating export controls.
Recent market activity reinforces these archetypes. Notable developments include significant contract awards and modernization programs in defense platforms, completion of critical design reviews for next‑generation ground-based AESA systems, and multiple product launches in mobile SATCOM and mmWave modules. These events validate our thesis that capital intensity and technical depth are prerequisites for scale — yet they also spotlight how modularization and cost reduction initiatives are compressing time-to-volume for newer entrants.
Operational Risks: Supply Chain, Regulation, and Geopolitics
For 2026 planning, three operational risks warrant priority attention:
- Semiconductor and component fragility: Reliance on GaN, GaAs, and advanced silicon RFIC ecosystems exposes manufacturers to cyclical supply constraints. Our operational playbook prescribes dual‑sourcing strategies, inventory hedging, and near‑term vertical integration options for critical T/R elements.
- Export controls and compliance complexity: ITAR and EAR remain structural constraints on cross‑border technology flows. Executives must align product roadmaps and partnership models to jurisdictions, incorporate compliance governance into M&A due diligence, and evaluate localized manufacturing to access restricted markets.
- Geopolitical shocks and tariff volatility: Ongoing tensions affecting trade in electronic goods impose margin and program‑delivery risk. Scenario planning that models tariff pass-through, contract re-pricing levers, and alternative supply geographies is essential for procurement resilience.
Technology and Product Strategy: Where to Place Bets
Our technology assessment favors three prioritized investment themes for the next three years:
- High-density GaN adoption at module and chipset levels — a lever for higher power per element and improved thermal performance that accelerates miniaturization and reduces array footprint for mobile platforms.
- Digital beamforming and integrated RF front ends — these architectures unlock multi-band agility and software-defined beam management, creating differentiation in multi-orbit SATCOM and congested spectrum environments.
- Cost-down modular AESA platforms — program success will hinge on repeatable, modular line-replaceable units that reduce lifecycle costs and ease integration across naval, airborne, and ground systems.
Leaders who combine these technical pathways with manufacturability and supply-chain control will be best positioned to win the large volume programs we model in our forecast.
Implications for M&A, Partnerships, and Investors
With market concentration underscoring the importance of scale in defense and SATCOM segments, we expect strategic M&A and supplier consolidation to continue. Investors and corporate strategy teams should prioritize targets that offer one or more of the following:
- Proven GaN T/R IP or differentiated beamformer ICs that materially improve module economics;
- High-quality manufacturing footprint with qualifying processes for defense supply chains and export-compliant production;
- Commercial SATCOM products with validated performance in mobile, Ku/Ka/Ku‑band, or multi-orbit environments that can scale through partnerships with satellite operators.
Joint development agreements, cross-licensing, and localized assembly partnerships will be common tactics to navigate regulatory barriers while projecting capability into restricted markets.
How Executives Should Use This Intelligence in 2026
PW Consulting’s report is purpose-built for decision windows that open in 2026: budget cycles, program bid timelines, and capital allocation reviews. Practical next steps include:
- Incorporating the report’s scenario-based forecasts into three-year rolling financial plans and capex prioritization;
- Executing supplier stress-tests and sourcing contingency plans that align with our supply-chain mitigation playbooks;
- Using the vendor evaluation framework to refine RFP criteria and M&A screening filters, focusing on manufacturability, export compliance, and thermal/power performance;
- Preparing modular product roadmaps that can be accelerated through targeted capex or partnered development to capture early volumes in SATCOM mobility and defense modernization programs.
About the Report and Access
The full Phased Array Antenna Module Market report contains detailed modeled scenarios, a year-by-year market forecast from our 2020 base through 2032, vendor scorecards, a technology adoption curve, and actionable implementation templates for procurement and product teams. To preserve competitive value for subscribers, we intentionally withhold segmented microdata in this briefing; the full breakdowns by application, region, and technology — and the underlying assumptions and sensitivity analyses — are available in the complete report package.
For executives seeking a concise advisory session, PW Consulting offers tailored briefings that map the report’s findings onto your portfolio or program roadmap. These sessions include prioritized implementation roadmaps, custom supplier analytics, and go-to-market acceleration plans aligned to 2026 decision calendars.
Conclusion
The phased array antenna module market is transitioning from a specialist, program-driven domain into a larger, cross-sector growth market where semiconductor innovation, satellite connectivity, and defense recapitalization converge. With a projected CAGR of 17.15% and multibillion-dollar expansion between our 2025 base year and the end of the forecast, firms must act now to secure supply chains, invest selectively in GaN and digital beamforming capabilities, and structure partnerships that mitigate export risk. PW Consulting’s forthcoming report equips leaders with the strategic and operational evidence to translate market growth into durable competitive advantage — the detailed breakdowns and tactical templates are available in the full report for organizations preparing to act in 2026.
For detailed analysis of this topic, please visit the official page:Phased Array Antenna Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com