
Laser Line Dielectric Mirror Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting’s latest market study on Laser Line Dielectric Mirrors delivers a sharply focused, decision-ready briefing for corporate leaders, procurement chiefs, and technology strategists preparing for 2026. The report synthesizes five years of historical performance, a proprietary bottom‑up market model, and forward-looking scenarios across the 2026–2032 forecast window. This release highlights the macro dynamics you must act on now — while reserving the full, segment-level datasets for subscribers and readers who access the report portal.
Worldwide Thermal Inkjet Coder (TIJ) Market
Executive snapshot — market momentum and what it means for 2026
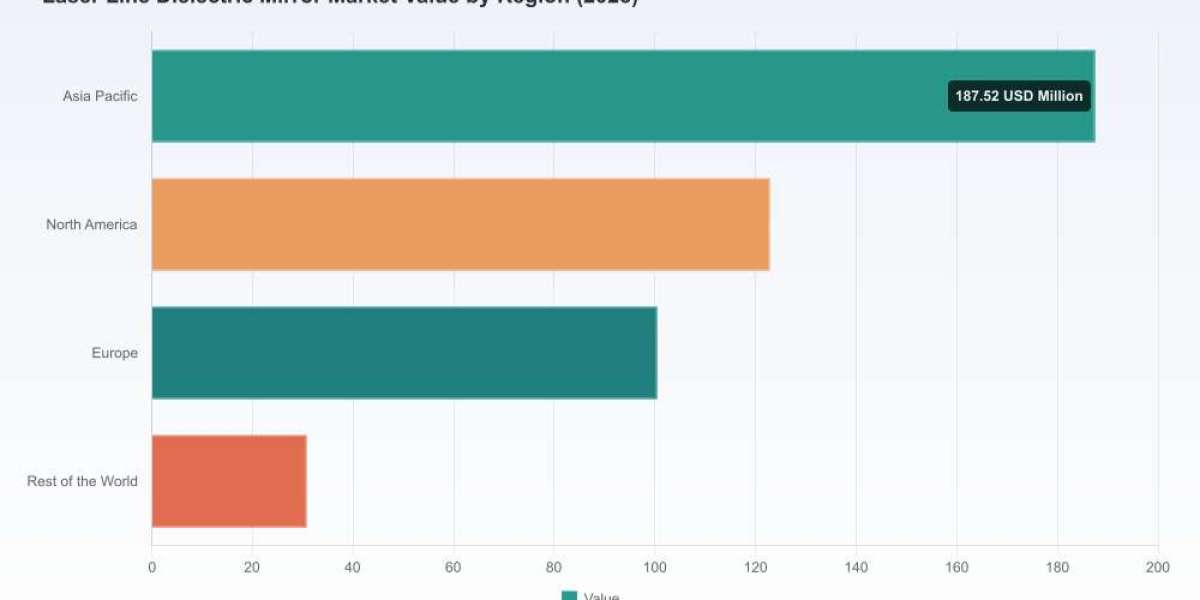
After a steady recovery and expansion through the early 2020s, the global Laser Line Dielectric Mirror market rose substantially by the 2025 base year. Our model shows the market value expanding across the historical window and carrying that momentum into the forecast horizon: the study uses a 2026–2032 compound annual growth rate of 6.25% to project continued, healthy growth driven by higher-power manufacturing lasers, growing medical instrumentation demand, and renewed scientific investment. The combined effect is a market trajectory that reinforces investment and supply‑chain actions in 2026 if companies want to secure competitive advantage rather than reacting to shortages and price volatility.
Behavioral Biometrics Software Market
Why 2026 is an inflection year
- Regulatory shockwaves and material controls: New export controls and tightened restrictions on critical feedstock have already altered availability and lead times for coating and substrate materials. Teams that treat these policy shifts as short-term noise will be caught off-guard.
- Technology differentiation is widening: Advanced coating processes (ion beam sputtering, e‑beam evaporation, and other thin‑film techniques) and specification attributes such as laser-induced damage threshold (LIDT), group delay dispersion for ultrafast lasers, and thermal stability are becoming primary purchase drivers.
- Consolidation without monopoly: Market concentration metrics indicate that while a small group of vendors accounts for a meaningful share of sales, the market remains sufficiently fragmented to enable fast followers and niche specialists to capture profitable pockets.
- Customer expectations: Laser-system integrators, medical OEMs, and scientific buyers increasingly demand shorter lead times, verifiable LIDT data, and integrated qualification packages — shifting value from pure product to product-plus-service.
Strategic actions recommended for 2026 (practical, prioritized)
- Immediate supplier risk assessment: Map single‑source dependencies for substrate and coating materials and prioritize alternative suppliers across regions. Where critical materials are concentrated, negotiate capacity reservations now.
- Invest in coating capability or partnerships: For OEMs with volume exposure to high‑power or ultrafast lasers, onshore investments or strategic partnerships in IBS/e‑beam capacity materially reduce operational risk and improve specification control.
- Redefine procurement KPIs: Move beyond unit price to measure delivered LIDT performance, batch traceability, and qualification lead time. Include these as contract clauses for 2026 renewals.
- Product portfolio segmentation: Adopt a two‑track product strategy — a standardized, rapidly-delivered line for price‑sensitive volumes, and a premium, fully-qualified offering for high LIDT and ultrafast applications.
- Scenario finance planning: Run stress tests on margin assumptions under elevated material costs and 30–90 day supply disruptions; update pricing models accordingly and develop contingency SKUs to maintain service levels.
What the PW Consulting report delivers — practical, actionable content
The study is structured to convert insight into immediate action. Key operational and strategic deliverables included in the report are:
Worldwide AMD Workstations Market
- A transparent, auditable market model (2020–2032) with downloadable workbook supporting bespoke scenario runs.
- Supplier scorecards and comparative technology maps that evaluate coating technologies, substrate options, and LIDT performance across the competitive set.
- Procurement playbook — negotiation templates, lead‑time hedging strategies, and contract clauses tailored to optics sourcing.
- Technology roadmaps and capability heatmaps highlighting where to invest in in‑house coating, where to partner, and where to consolidate purchases for scale.
- M&A and partnership shortlist, informed by capability gaps and concentration analysis — including identified targets for bolt-on acquisitions to accelerate high‑LIDT capacity.
- Three forecast scenarios (base, constrained‑supply, and accelerated‑adoption) with sensitivity analyses designed for CFOs and strategy teams.
Competitive landscape — who matters and why
Our vendor analysis covers the broad spectrum of established global suppliers, specialized niche players, and regional manufacturers. The market exhibits moderate concentration: the three largest firms capture a meaningful portion of the market while the top five approach roughly half of total sales. This structure creates room for both scale incumbents and highly-specialized suppliers to win — depending on capability, lead time, and certification.
Highlighted company capabilities in the report include:
- Multi‑national optics suppliers with broad catalog offerings and global distribution footprints, who compete on standard product range, delivery performance, and brand recognition.
- Specialist coating houses and precision‑optics teams that compete on ultra‑high reflectivity, highest LIDT, and custom spectral profiles for Nd:YAG, Yb:YAG and Ti:sapphire systems.
- Regional manufacturers who deliver cost‑competitive options and rapid custom prototyping but may be exposed to raw material and export regulation risks.
Company profiles in the study include technology positioning, typical product specifications, primary markets served, and recent commercial or product development moves. Recent industry moves underscoring strategic themes include new product catalogues focused on high‑accuracy large mirrors, thin‑film mirror series with enhanced damage resistance, trade‑show demonstrations of high‑repeatability IBS coatings, and supplier excellence awards highlighting improved lead‑time and LIDT performance.
Raw materials and supply chain resilience: operational levers
The report provides a practical assessment of substrate and coating supply chains. Common substrates such as fused silica and Zerodur remain central to high‑performance mirrors, and typical high‑reflectance coatings for common laser lines are implemented with multi‑micron thin‑film stacks. However, regulatory moves restricting exports of key materials have increased procurement complexity and extended lead times for some buyers. The consequence for procurement and operations teams is clear: build sourcing redundancy, qualify substitute substrates where feasible, and accelerate material‑specific testing protocols so qualification timelines don’t become a commercial bottleneck.
Commercial and product design playbook
- Design for manufacturability: engineers should specify tolerances that balance optical performance and manufacturability to shorten iterative design cycles.
- Modular qualification packages: offer tiered testing — standard LIDT and environmental tests for commodity buyers, and extended GDD and pulse‑width specific testing for ultrafast integrators.
- Service differentiation: embed traceability, lot‑level testing data, and rapid replacement guarantees as core differentiators in commercial proposals.
How executives should use this brief in 2026
Senior leaders should use the report to prioritize three actions for 2026: (1) harden the supply base now via dual sourcing and contractual capacity holds where materials concentration presents risk; (2) accelerate capability investments in coating technologies that materially differentiate product performance; and (3) reconfigure commercial terms to capture the value of faster qualification and proven LIDT performance. Failure to operationalize these moves will result in margin erosion and lost share to more proactive rivals.
Next steps and how to access the full intelligence
This briefing is intentionally directional — it reveals the strategic levers and macro trajectories that matter for 2026 but conserves the proprietary, segment‑level datasets, supplier scorecards, and downloadable financial model for report subscribers. For teams preparing 2026 budgets, procurement RFPs, or M&A screens, commissioning the full report or booking a tailored briefing with PW Consulting will provide the granular inputs required to execute confidently.
PW Consulting is scheduling limited expert briefings for enterprise clients and investors in Q4 2025 and Q1 2026. Contact our advisory desk to reserve a session where we walk through the model, customize scenario sensitivities for your business, and deliver a prioritized implementation roadmap.
Strategic clarity matters in 2026 — this study equips leaders with the insight to move first and move decisively. Access the full dataset and supplier matrices on the PW Consulting report portal to convert the macro signal into operational advantage.
For detailed analysis of this topic, please visit the official page:Laser Line Dielectric Mirror Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com