
PW Consulting: Strategic Brief — Hybrid Voice Recognition Systems Market Outlook (2026 Planning Lens)
Executive summary
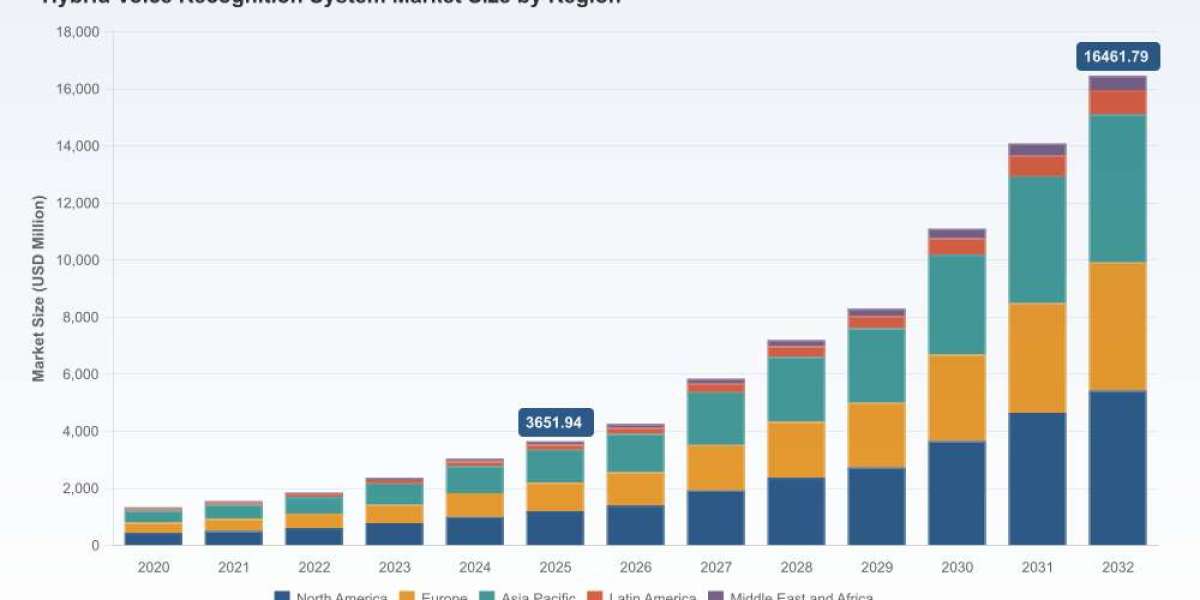
Hybrid voice recognition—architectures that blend on-device/edge processing with cloud intelligence—has moved from niche optimization to strategic backbone for voice-enabled products and services. Our latest market research, anchored on a 2025 base year and projecting through 2032, quantifies a sustained, high-growth trajectory (CAGR 23.95%). The global market expands rapidly from early-decade foundations into a multibillion-dollar opportunity by the end of the forecast horizon, driven by converging forces in automotive, consumer devices, regulated verticals, and cloud-edge infrastructure.
Worldwide Liquid Chocolate Market
For leaders preparing 2026 budgets and roadmaps, this report is built to be decision-grade: it translates macro momentum into executable choices — from procurement and product architecture to partnerships, compliance, and M&A prioritization. The analysis demonstrates why hybrid architectures are the pragmatic choice for organizations that must balance latency, privacy, accuracy, and cost.
Worldwide Automatic Tool Change Spindle Market
Why this report matters for 2026 decision-making
- High-growth but high-complexity market: Rapid CAGR underscores urgency: delaying strategy risks ceding platform control or integration costs as suppliers and OEMs entrench their stacks.
- Technology and regulatory inflection points coincide: Advances in on-device neural acceleration, broader 5G/edge infrastructure, and tightened privacy regimes make 2026 a pivotal year to choose architectures that are futureproof.
- Vendor differentiation is practical, not academic: Market concentration metrics show leadership pockets with room for specialist challengers—so sourcing and partnership choices will determine competitive positioning.
- Operational trade-offs are quantifiable: Latency, TCO, data residency, and model update cadence can be modeled; our report includes scenario-based ROI frameworks to transform those trade-offs into board-level decisions.
What the report delivers (actionable, not academic)
PW Consulting’s industry-grade deliverable is structured to convert insight into action across procurement, engineering, legal, and corporate strategy teams. Highlights include:
Worldwide Mobile Folding Tent Market
- Proprietary market-sizing and scenario models that translate macro growth into addressable opportunity by deployment archetype and business model (note: detailed subsegment figures are reserved for subscribers).
- Vendor scorecards and supplier decision matrices calibrated to enterprise priorities: latency, on-device accuracy, privacy controls (SOC 2/ISO readiness), customization, and go-to-market fit.
- Deployment playbooks for three archetypal use-cases — low-latency automotive controls, privacy-sensitive healthcare dictation, and consumer-device wake-word ecosystems — including integration patterns and sample tech stacks.
- Regulatory and compliance checklist templates tailored for GDPR, HIPAA, and industry-specific audit expectations, with pragmatic controls for hybrid architectures (data minimization, consent flows, key rotation, logging).
- M&A & partnership scouting intelligence: mapped capabilities, gap analyses, and a short list of acquisition or alliance profiles likely to unlock value within 12–24 months.
- Risk heat maps and mitigation roadmaps highlighting adversarial robustness, model drift, and third-party dependency risks—plus recommended governance cadence for 2026 procurement cycles.
Competitive landscape — who matters and why
The market shows a mix of hyperscale cloud providers, specialized AI vendors, automotive specialists, and regional leaders. Our competitive analysis synthesizes technology positioning, go-to-market vectors, and likely strategic moves through 2026.
- Hyperscalers (Google, Microsoft, AWS): These players leverage large-scale cloud neural models and extensive developer ecosystems. Their differentiator is breadth—end-to-end platform integrations, multilingual support, and strong enterprise SLAs. Expect them to push deeper into edge-cloud orchestration, often via telco and device OEM partnerships.
- Platform-specialists (Nuance, Cerence): Established strength in automotive and healthcare, combining on-device deterministic processing with cloud-based contextualization. Their domain expertise and vertical certifications remain a durable moat for OEMs seeking embedded, regulation-aware solutions.
- Consumer-device and silicon-aligned players (Apple, Sensory): A focus on privacy-preserving, on-device inference supports differentiated user experiences. Their advantage is tight hardware-software co-optimization that drives power and latency benefits.
- Regional and niche challengers (iFLYTEK, Baidu, Speechmatics): Strong local language models, regulatory familiarity, and rapid product iteration give them authority in specific markets and regulated use cases.
- Innovators and NLU specialists (SoundHound, Speechmatics, Verint): These vendors add value through robust natural language understanding, domain adaptation, and integration into customer engagement and analytics workflows.
Market concentration statistics indicate a moderate level of consolidation at the top tiers—enough to confirm that strategic partnerships with leading providers matter, yet the field is open for differentiated offerings, particularly those delivering domain-specific accuracy or superior on-device economics.
Recent market signals you should not ignore (2024–early 2026)
- Major vendors are investing in cloud-edge stacks and telco partnerships to exploit 5G-enabled low-latency use cases—this changes procurement timelines for OEMs and enterprises.
- Specialist vendors are launching verticalized engines for healthcare and automotive, reflecting buyer demand for compliance-ready, low-latency solutions.
- Regulatory pressures (GDPR, HIPAA) and third-party assurance expectations (SOC 2 Type II, ISO 27001) are now procurement gatekeepers for deals in regulated industries.
Regulatory and standards dynamics shaping strategy
Decision-makers must build compliant and resilient systems. Key dynamics covered in the report include the practical application of GDPR for voice data, HIPAA considerations for clinical voice capture, and NIST’s AI Risk Management Framework as an operational guide. Technical standards discussions emphasize why hybrid designs frequently combine tried-and-true DNN hybrid approaches with emerging end-to-end architectures to balance accuracy and resource constraints—particularly in multilingual and low-resource environments.
2026 strategic playbook — recommended executive actions
- Adopt a hybrid-first product architecture: Prioritize designs that allow dynamic routing between on-device inference and cloud enrichment to manage latency, costs, and privacy simultaneously.
- Invest in edge compute and model lifecycle automation: Capitalize on hardware acceleration and continuous delivery pipelines for models to keep on-device intelligence up to date without compromising governance.
- Negotiate platform-flexible commercial terms: Ask vendors for modular pricing tied to feature tiers (on-device cores, cloud transcription minutes, NLU customization), and secure rights for third-party audits and portability.
- Partner with telcos and integrators for 5G use-cases: Where ultra-low latency or distributed inference is required, co-funded trials with operators can shorten time-to-market and share infrastructure risk.
- Embed compliance into procurement and engineering: Use the report’s checklist to bake consent, data minimization, and auditability into product requirements rather than retrofitting controls later.
- Prioritize focused M&A or minority investments: Acquire capabilities that accelerate domain adaptation (medical vocabularies, automotive command lexicons) rather than broad horizontal stack pieces.
Why PW Consulting’s report is different
Many market notes stop at high-level forecasts. This deliverable goes further: we map macro growth into operational decisions and provide the tactical tools teams need to execute in 2026—sourcing templates, vendor RFP criteria, integration blueprints, and ROI calculators. We intentionally structure the report as a “playbook plus market map” so strategy teams can run pilots, legal teams can complete compliance sign-offs, and finance can model investment returns within the same framework.
Closing and call to action
Hybrid voice recognition is no longer a speculative investment; it is a strategic lever for product differentiation, regulatory-compliant automation, and customer experience transformation. The market’s steep growth trajectory and the evolving competitive/regulatory context create a narrow window in 2026 to lock in architecture, partner ecosystems, and control points.
PW Consulting’s full report contains the proprietary subsegment tables, vendor scorecards, and downloadable decision-support tools that allow teams to translate these insights into procurement-ready, board-approvable plans. To access the complete intelligence package and our scenario models, please visit the PW Consulting research portal for subscription and licensing options.
For detailed analysis of this topic, please visit the official page:Hybrid Voice Recognition System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com