
Hospital-Acquired Infection (HAI) Control Market: Strategic Imperatives for 2026
Executive summary
As health systems worldwide double down on patient safety and regulatory scrutiny tightens, the Hospital-Acquired Infection (HAI) Control market is entering a phase of predictable, durable growth. PW Consulting’s new market study — anchored on a 2025 base year and extending through 2032 — forecasts the global market to grow at a compound annual growth rate (CAGR) of 6.45% across the 2026–2032 forecast window, rising from an estimated market size in 2025 to a materially larger market by 2032. For boards, business unit leaders, and investors planning 2026 capital allocation cycles, the implications are clear: the HAI control market is large, investible, and strategically intertwined with clinical quality metrics, reimbursement risk, and regulatory evolution.
Worldwide Cutaneous Squamous Cell Carcinoma Treatment Market
Why 2026 is a pivotal decision year
Transitional regulatory clarity: 2025 closed with a spate of regulatory activities — advisory committee deliberations and device-specific clearances — that are crystallizing approval pathways for a new generation of UVC and other non-traditional HAI technologies. Those procedural clarifications create a window in 2026 in which strategic product launches and regulatory strategies can realize outsized returns.
Worldwide Slide Tray Box MarketOngoing payor pressure and quality-linked reimbursement: With hospital-acquired condition programs and pay-for-performance metrics remaining a central lever for payors in multiple markets, investments in infection control now carry direct financial and reputational ROI that procurement committees will prioritize in 2026 budgeting rounds.
V-plow Snowplow MarketMarket scale and momentum: Our model captures historical dynamics from 2020–2025 and projects sustained expansion through 2032. This combination of steady historical growth and forward-looking acceleration creates predictable demand that supports both organic expansion and M&A strategies.
Key growth vectors and demand drivers
Technology convergence: Convergence across consumables, disinfection equipment, and digital monitoring is shifting procurement from discrete purchases to bundled, outcomes-focused solutions. Buyers increasingly value integrated offerings that demonstrably reduce infection rates and simplify sterile processing workflows.
Commercialization of novel modalities: Regulatory clearances of ultraviolet (UV) whole-room systems and De Novo pathways for niche microbial-reduction devices have opened new clinical use cases. These device approvals lower adoption friction and provide defensible value propositions to infection prevention teams.
Service and recurring revenue models: Sterilization and contract sterilization services are evolving into predictable revenue streams. Hospitals are outsourcing complex sterilization processes and purchasing consumables under subscription or managed-service frameworks to control cost and compliance.
Procurement economics under pressure: With penalties tied to HAI metrics and growing emphasis on total cost of care, hospital CFOs and supply chain leaders are prioritizing investments that reduce downstream costs from extended lengths-of-stay, readmissions, and litigation.
Regulatory and policy dynamics shaping 2026 strategies
U.S. regulatory signals: FDA engagement on germicidal UV device study design and recent clearances for whole-room UV systems indicate that manufacturers now have clearer evidentiary pathways. However, regulators emphasize that clinical outcome claims (e.g., reduction in HAI rates) require robust study designs — a constraint and an opportunity for sponsors that invest in high-quality clinical programs.
European regulatory tightening: The EU Medical Device Regulation (MDR) has upped post-market surveillance and documentation demands for infection control devices. Suppliers targeting the European market must augment PMS capability and product lifecycle evidence in 2026 or face market access delays.
Reimbursement levers: Ongoing CMS programs and analogous schemes globally continue to make HAI metrics financially material for hospitals. This creates an environment where procurement decisions are evaluated not just on unit price but on demonstrable impact on quality metrics.
Competitive landscape: implications for market positioning
The HAI control market exhibits a mix of global platform players, specialized technology vendors, and contract-service providers. Aggregate concentration is moderate — with the top three and top five market participants collectively representing a meaningful but non-dominant share of the market — a structure that supports both incumbent-led consolidation and focused, high-growth niches.
Established diversified players: Companies with broad infection prevention portfolios — spanning consumables, disinfectants, and sterile processing equipment — remain well positioned to sell integrated value propositions into hospitals. Their advantage lies in deep channel reach, clinical trust, and the ability to bundle hardware, consumables, and services.
Specialists and disruptive entrants: Firms focused on novel disinfection modalities, low-temperature sterilization, or robotic UV systems are driving product-level differentiation. These vendors gain traction by pairing clinical evidence with operational proofs-of-concept, often entering via pilot programs in high-acuity settings.
Service-edge competitors: Contract sterilization and outsourced reprocessing providers have expanded capacity and geographic reach; their models are attractive to device manufacturers seeking scalable sterilization partners and to hospitals aiming to shift capital to operating budgets.
Profiles and strategic postures you should watch
Legacy manufacturers with broad portfolios continue to monetize scale and clinical relationships to defend share, but must accelerate digital and service-layer enhancements to maintain growth.
Innovative device companies that secure regulatory milestones in 2025–2026 will be able to translate clearance into commercial trials and rapid rollouts, particularly in U.S. tertiary centers and large health systems.
Midsize players and contract sterilizers are attractive acquisition targets for platform acquirers seeking to round out sterile processing capabilities or to secure service networks for bundled offerings.
Recent industry developments that change the playing field
Late-2025 regulatory progress: Notable device clearances and a De Novo authorization for UV-based microbial-reduction technologies have created practical precedents for similar devices to follow — lowering time-to-market risk for comparable systems.
Strategic M&A: Transactions aimed at strengthening consumables portfolios and U.S. distribution indicate that incumbents are prepared to buy growth where organic expansion is too slow or too costly.
Policy continuity: Continued financial penalties tied to HAI outcomes remain a core demand driver, reinforcing hospital commitments to invest in prevention technology and process improvement.
What our report contains — practical, executable outputs
PW Consulting’s report is built as a decision-support tool for 2026 planning cycles. It combines rigorous quantitative forecasting with actionable frameworks and includes:
Market sizing and trend analysis: A validated historical series and forward projections through 2032 to stress-test portfolio growth plans and to size addressable opportunity for new product introductions.
Commercial playbooks: Go-to-market recommendations for product types (capital equipment, consumables, and software/monitoring services), pricing strategies, and procurement engagement models that drive adoption in hospital and ambulatory settings.
Regulatory and clinical evidence roadmaps: Practical templates for study design, post-market surveillance, and value dossiers that align with FDA and EU expectations.
M&A and partnership evaluation matrix: A framework to prioritize acquisition targets and strategic alliances, with financial sensitivity analyses that reflect varying adoption curves and reimbursement scenarios.
Operational readiness checklists: Deployment guides for sterile processing departments, infection prevention teams, and supply chain stakeholders to accelerate pilot-to-scale transitions while managing nurse and technician labor impacts.
Strategic recommendations for 2026 decision-makers
Prioritize evidence-based pilots: Allocate budget to clinical pilots that generate meaningful HAI-related endpoints and operational metrics (turnaround time, throughput, consumable usage). Well-documented pilots will materially improve purchasing velocity.
Bundle outcomes, not just products: Create commercial offers that tie consumables, equipment maintenance, training, and monitoring software into single accountable contracts. Buyers increasingly value outcome alignment over unit-level discounts.
Invest in post-market surveillance: For manufacturers, robust PMS and real-world evidence portfolios are no longer optional in heavily regulated geographies; these investments reduce market access friction and support premium positioning.
Use targeted M&A to accelerate footprint: Acquire complementary consumables or service capabilities to rapidly expand addressable markets and to capture recurring revenue streams that stabilize top-line growth.
Plan for regulatory contingencies: Build adaptive clinical and regulatory budgets that can scale if regulators request larger evidence sets or additional post-market commitments following early product launches.
How to use the report for 2026 planning
Procurement leaders, product strategists, and corporate development teams should use the report to align investment case assumptions, stress-test pricing strategies, and prioritize pilots that deliver the quickest route to measurable HAI improvement. The combination of a clearly modeled market size, multi-year growth rates, and pragmatic implementation tools makes this study a practical guide for board-level strategy sessions and annual operating plan (AOP) cycles for 2026.
Closing teaser — what we intentionally withheld to guide your next step
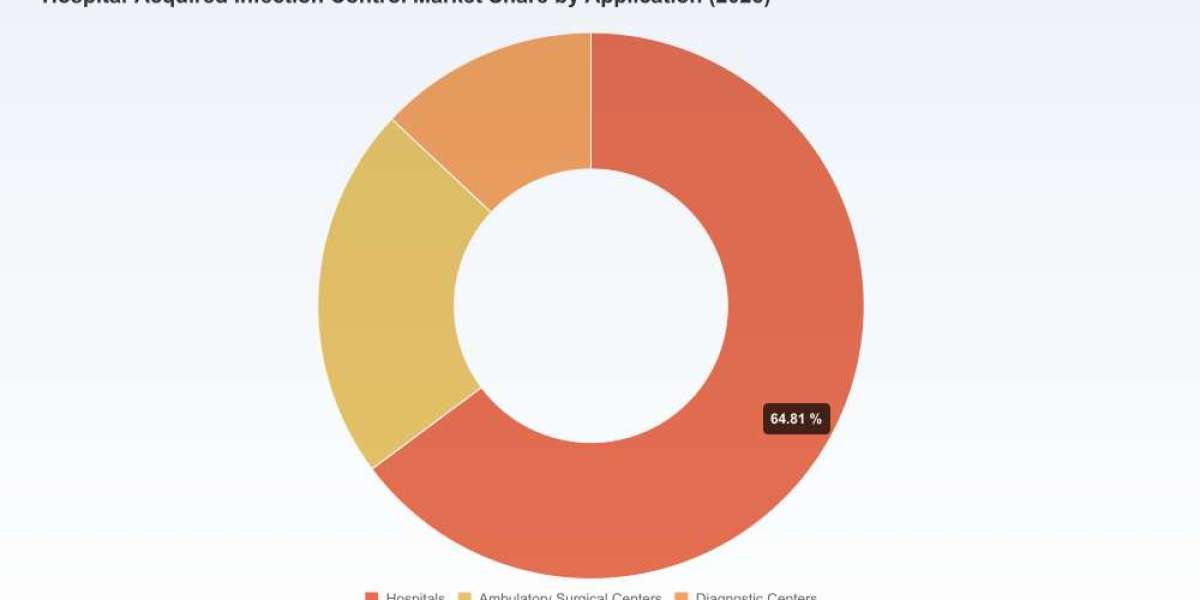
To preserve the “trailer” experience and to encourage direct engagement with our analysts, this press release highlights market-scale metrics, growth trajectory, and strategic imperatives without publishing our full segmentation tables or granular regional/application share breakdowns. The full report contains those detailed splits, vendor benchmarking, and downloadable financial models that clients use directly in investment committees and procurement negotiations.
Next steps
For access to the full model, company benchmarking, and a tailored briefing with PW Consulting’s HAI control practice leaders to translate these insights into your 2026 plan, visit the PW Consulting market page or contact our industry desk to schedule a strategic briefing.
For detailed analysis of this topic, please visit the official page:Hospital Acquired Infection Control Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com