
Paper Coaster Market 2026: Strategic Preview for Corporate Decision-Makers
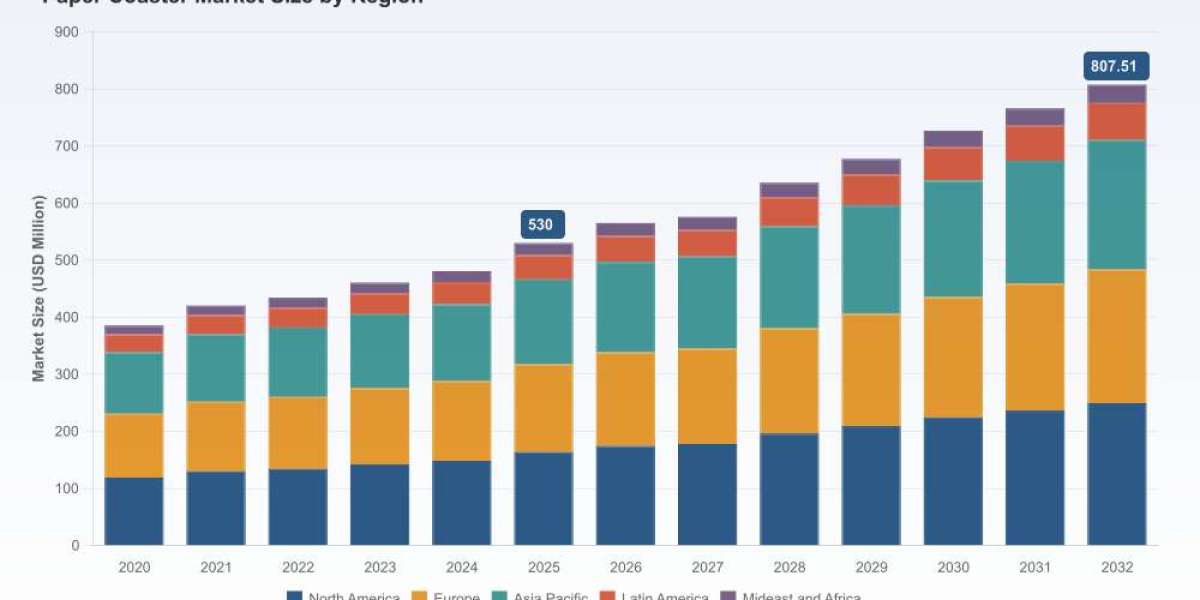
PW Consulting’s latest market briefing — based on the 2025 base-year study and a 2026–2032 forecast horizon — translates granular industry signals into a compact strategic playbook for executives, procurement teams, and investors making decisions in 2026. Our modelling shows the global paper coaster market reached USD 530.0 Million in 2025 and, with a projected compound annual growth rate (CAGR) of 6.2% over the forecast period, is set to advance materially by 2032. This release synthesizes the high‑level implications that matter most to boardrooms while intentionally withholding granular segment-level allocations to direct stakeholders to the full report for transaction‑grade data.
Worldwide Solid Potassium Hydroxide Market
Why this matters for 2026 planning
Timing of investment: With the market on an upward trajectory and a multi-year growth runway, 2026 is a window for strategic investments — in capacity upgrades, margin protection, and differentiated product development — before cost and regulatory pressures fully crystallize.
Vertical Planetary Ball Mill MarketProcurement leverage: Suppliers remain numerous and regionalized. The market concentration metrics indicate limited dominant players, creating opportunities for buyers to extract better terms through selective dual‑sourcing and performance‑based contracting.
Worldwide Glycoprotein Analysis MarketRegulatory risk shaping product roadmaps: Emerging Extended Producer Responsibility (EPR) regimes and state‑level recycling mandates are shifting the economics of paper‑based hospitality disposables. Companies that integrate compliance and circularity into their product lifecycle planning in 2026 will avoid higher redesign and compliance costs later.
Market snapshot (what the headline numbers mean)
Our top‑level sizing and forward curve provide three actionable takeaways. First, the market is sufficiently large and growing at a steady mid‑single digit CAGR, which supports both incremental product innovation and targeted capacity additions. Second, growth is not uniform — it is being driven by a combination of hospitality recovery dynamics, durable demand from promotional channels, and selective premiumization of printed and specialty finishes. Third, the competitive structure remains fragmented: the top three firms capture a modest share of sales, and the top five remain well below consolidation thresholds typically associated with pricing power. Taken together, the environment favors focused differentiation over scale races for most participants.
Segment dynamics and supply‑side signals
Materials and cost base: Two material archetypes dominate product design tradeoffs — virgin fiber constructions that prioritize print fidelity and perceived quality, and recycled/engineered substrates that target cost and sustainability narratives. Buyers should anticipate procurement volatility tied to regional paperboard price differentials and inventory cycles. Recent pricing intelligence indicates material cost dispersion across markets, with pockets of relative cheapness and others exhibiting premium pricing, affecting landed costs and margin levers.
Input price indices: Primary producer price indicators for paperboard categories have shown relative stabilization in the near term, but periodic supply shocks remain a tail risk. Our scenario workbench models the sensitivity of gross margins to ±15–25% shifts in feedstock costs and provides hedging and pass‑through strategies suitable for different business models.
Regulatory overlay: Multiple U.S. states have implemented or are phasing in comprehensive EPR regimes for packaging and paper products. These laws shift financial responsibility for end‑of‑life management to producers and typically accelerate cost recognition through Producer Responsibility Organizations (PROs), service reimbursements, and compliance obligations. Companies that treat EPR as a cost center rather than an opportunity to redesign value chains will underperform peers.
Commercial and product strategy implications
Go‑to‑market: The most effective commercial models blend core hospitality fulfillment with a promotional/brand printing capability. Winning suppliers segment customers by value‑recency — long‑term accounts that prioritize reliability versus short‑term promotion buyers that prioritize cost and speed to market.
Product innovation: Incremental product premiumization — specialty finishes, moisture‑management backings, and bespoke shapes — continues to command price premiums. At the same time, sustainability claims (recyclability, recycled content, compostability) are increasingly table stakes with corporate procurement and QSR chains.
Operational resilience: Given the fragmented supplier base, prudent players are implementing supplier scorecards, dual sourcing with near‑shoring options, and inventory hedges for peak hospitality seasons. Outsourced manufacturers with modular production capabilities offer flexible responses to promotional campaigns and seasonal swings.
Competitive landscape: what the majors are doing (strategic positioning)
The operating field includes a mix of specialized regional manufacturers, promotional suppliers, and bulk commodity producers. Key strategic archetypes we observe:
Regional specialists focusing on custom printed and specialty finishes, leveraging proximity to hospitality clusters and shorter lead times.
Large promotional suppliers emphasizing full‑color printing, sustainability credentials, and channel partnerships with marketing agencies and event planners.
Export‑oriented producers in lower‑cost regions targeting high‑volume, low‑complexity orders for distribution networks and private label programs.
Representative firm profiles in the competitive set illustrate these archetypes. Some suppliers emphasize high‑volume, customizable pulpboard production with advanced finishes and specialty printing; others differentiate with absorbent engineered substrates and laminated backings for moisture performance; still others target cost‑conscious bulk promotional channels with varied thickness and shape options. Against this backdrop, the market’s relatively low concentration ratio implies that new entrants with clear niche focus, margin optimization, or channel control can gain traction without needing large-scale consolidation.
Report deliverables: what the full study provides
The PW Consulting paper coaster report is structured as a pragmatic decision tool for corporate users. Highlights of the full deliverable include:
Market sizing and verified time series (historical 2020–2025, base year 2025) and a bottom‑up forecast model (2026–2032) with scenario toggles for demand shocks, material price swings, and regulatory adoption schedules.
Commercial playbooks: go‑to‑market roadmaps for manufacturers, distributors, and brand owners, including segmentation frameworks, pricing decks, and contract templates for volume discounts and promotional runs.
Procurement and cost modelling tools: bill‑of‑materials (BOM) templates, landed cost calculators by trade lane, and pass‑through modelling tied to material price indices.
Regulatory and sustainability action matrix: EPR compliance pathways, circularity pilots, lifecycle assessment (LCA) scorecards, and recommendations for PRO engagement and reporting.
Supplier and partnership diagnostics: vendor scorecards, M&A screens, and integration checklists for roll‑up strategies or strategic partnerships.
Commercial due diligence annex: checklists, red‑flags, and valuation sensitivities for investors evaluating targets in this segment.
To preserve commercial value for subscribers and deal participants, the public summary intentionally omits granular regional and application splits, and supplier‑level revenue estimates. Those tables and the downloadable modelling workbook are available in the full report package.
Practical 90‑day checklist for executives (actions for 2026)
Run a rapid cost‑to‑serve audit across top accounts and identify one high‑impact supplier to dual‑source within 90 days.
Initiate an EPR compliance gap analysis: engage legal and sustainability leads to assess exposure across operating jurisdictions and develop a cost allocation plan for PRO fees and collection obligations.
Pilot a high‑margin specialty offering with a limited set of hospitality partners to test pricing elasticity and production bottlenecks.
Deploy supplier scorecards with KPIs tied to on‑time delivery, quality, sustainability credentials, and cost improvement commitments.
Model three downside scenarios for raw material price spikes and formalize pass‑through mechanisms in customer contracts where feasible.
What to watch in 2026 and beyond
Regulatory cadence: Implementation timelines and compliance costs under state EPR programs will be the most consequential near‑term operational headwind for producers servicing U.S. markets.
Material substitution and design innovation: Advances in engineered substrates and coating technologies will determine which players sustain margin premiums.
Channel consolidation: Expect selective consolidation among distributors and marketing aggregators that offer integrated promotional services and better order aggregation.
Cost pass‑through clarity: The degree to which producers can pass EPR and material costs to buyers will drive margin divergence across the value chain.
Final assessment and next steps
The paper coaster sector occupies a strategic inflection point: steady baseline demand and product premiumization coexist with regulatory and input‑cost volatility. For companies and investors preparing 2026 strategies, the imperative is threefold — secure supply and cost certainty, embed regulatory‑compliant circularity into product roadmaps, and pursue focused commercial differentiation rather than generalized scale plays. PW Consulting’s full report provides the transaction‑grade segment tables, supplier revenues, and the downloadable modelling workbook necessary to convert these strategic priorities into executable plans.
For immediate access to the complete report, contractor‑grade models, and bespoke advisory engagements tailored to your participation in the paper coaster value chain, please visit our report page or contact PW Consulting. The full dataset contains the detailed regional and application breakdowns and supplier‑level analytics required for procurement negotiations, M&A diligence, and business planning.
For detailed analysis of this topic, please visit the official page:Paper Coaster Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com