
Composite Sandwich Panels Market: Strategic Imperatives for 2026
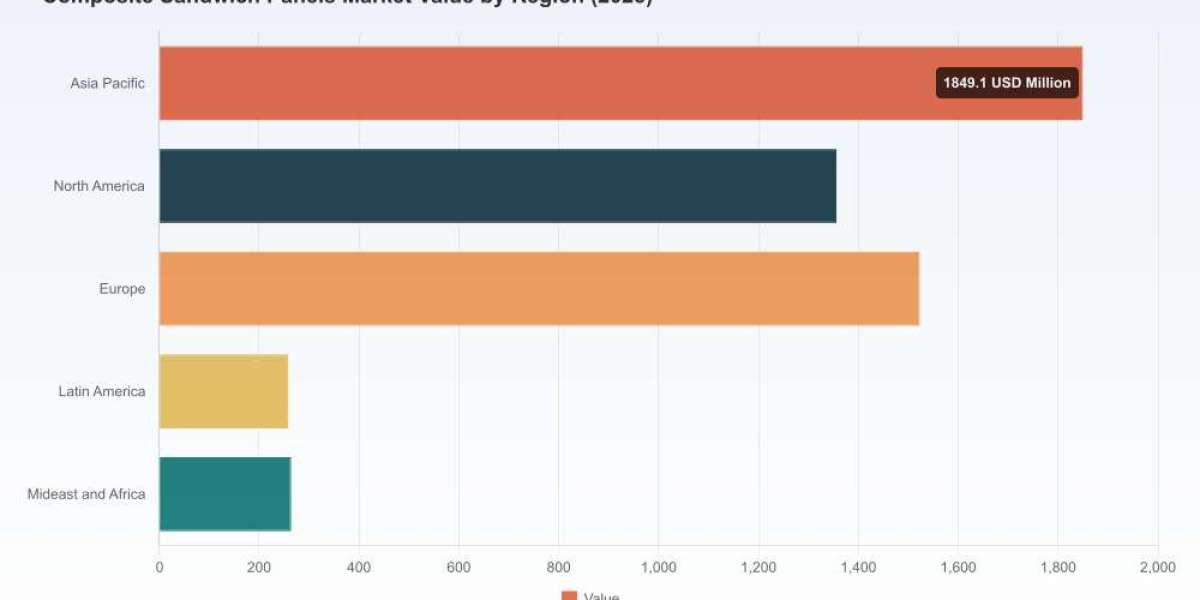
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a focused synthesis of our latest Composite Sandwich Panels Market report — a practical, decision-ready briefing for executives shaping 2026 strategies. The market has demonstrated resilient expansion through the 2020–2025 period and, with a 7.15% compound annual growth rate underlying our projections for 2026–2032, is on a clear growth trajectory. From an estimated USD 5.25 billion in 2025 to a projected USD 8.51 billion by 2032, the scale and direction of this market make it a strategic priority for manufacturers, OEMs, investors, and large end-users planning near-term capital allocation and technology roadmaps.
Worldwide Operation Suture Market
Why this report matters for 2026 decision cycles
Timing of capital: 2026 will be a pivotal year for committing to capacity expansions, new product lines, and certification programs that require 12–36 months to deliver market impact. Our report converts market momentum into prioritized investment windows.
Conductivity Measuring Electrodes MarketRegulatory alignment: Changing fire safety, thermal insulation, and embodied carbon regulations mean that product certification and materials selection will determine market access in several high-growth end markets.
Worldwide Single Use Cystoscope MarketM&A and partnerships: With moderate market concentration at the top, select consolidation and capability partnerships can accelerate customer access without full-scale greenfield investments.
Operational resilience: Raw material volatility and evolving core technologies require hedged procurement strategies and modular manufacturing playbooks to protect margins.
Top-line, data-driven takeaways (for executive action)
Macro growth supports pro‑active investment: The market expanded meaningfully from 2020 through 2025 and is forecast to keep upward momentum to 2032. This trend justifies early-stage investments in certification, automation, and core R&D for companies targeting leadership by 2028–2030.
Regulation and sustainability are demand multipliers: Stricter fire and thermal performance standards, together with client demand for lower embodied carbon, are shifting buyer preference toward advanced cores and recycled/thermoplastic materials. Firms that align product roadmaps now will face lower market-entry friction and faster adoption curves.
Material and supply‑chain volatility is a strategic risk: Polyurethane, PIR foam systems and petroleum-derived resin costs remain sensitive to oil price swings. Hedging raw material exposure and qualifying alternate core chemistries are essential defensive moves for 2026 procurement plans.
Honeycomb and thermoplastic cores are a technology inflection: Honeycomb core technologies remain a dominant substrate across high-value applications. Concurrently, thermoplastic cores and recycled polyolefins are moving from niche to mainstream where recyclability and cost control matter.
Segment convergence creates product platform opportunities: Cross-pollination between construction, transportation and aerospace requirements — especially around lightweighting and thermal control — enables platform products that scale across end markets if engineered for regulatory modularity.
Moderate market concentration favors targeted consortiums: The top three and top five players hold meaningful shares, yet the market remains accessible for focused regional or technological specialists to win repeat business through service and certification advantages.
Competitive landscape: who matters and why
Our report profiles established leaders and nimble specialists whose recent strategies highlight the set of competitive plays available in 2026:
Kingspan Group — market-proven performance positioning around thermal efficiency, fire safety and sustainable building envelopes. Their advanced core technologies set commercial benchmarks for high-performance insulated panels.
Hexcel Corporation — aerospace and defense expertise, focusing on honeycomb cores and high strength-to-weight solutions. Hexcel’s product launches and certification work indicate sustained leadership in high-performance transport applications.
The Gill Corporation & Advanced Custom Manufacturing — specialized manufacturing for aerospace and transportation customers, with flexible production that supports bespoke structural panels and multi-opening press capabilities.
ArcelorMittal, Tata Steel, Nucor — steel- and metal-faced systems providers who leverage integrated materials and distribution channels to serve roofing, cladding and industrial structures with high load-bearing and fire-rated panels.
3A Composites, EconCore, Rock West Composites, and regional specialists (e.g., Hangzhou Holycore, Manni Group, Metecno) — these players advance lightweight materials, honeycomb innovations, and localized capacity expansions that capture regional project pipelines.
DANA Group and Assan Panel — demonstrate how regional market depth and distribution can be paired with product breadth to win infrastructure and industrial contracts across the Middle East, Africa and adjacent regions.
Strategic implications: for product leaders, partnering with honeycomb and thermoplastic core innovators accelerates time-to-market. For investors, target companies with combined strengths in certification, proprietary core tech and scalable manufacturing. For large end-users, preferred-supplier agreements with multi-material capability suppliers reduce integration risk.
Recent developments that shape near-term strategy
Capacity expansions (e.g., Hangzhou Holycore’s facility increase in early 2026) signal rising demand for thermoplastic fiberglass panels, especially in transportation and renewable energy subsegments.
Certifications and OOA readiness (e.g., Toray Advanced Composites’ NCAMP qualification) lower manufacturing barriers for high-performance aerospace honeycomb structures — a prompt for OEM sourcing reviews.
Targeted product launches (Hexcel’s mid-temperature honeycomb and ArcelorMittal’s high-performance roof panel) demonstrate how thermal-resistance innovations are translating quickly into customer offerings.
New continuous production lines for glass fiber/PUR composites highlight how automation and process innovation are unlocking volume markets previously constrained by manual production.
Risk landscape — what to monitor in 2026
Raw material price volatility tied to oil markets and resin/feedstock supply concentration.
Regulatory divergence across major markets on fire safety, recycled content, and embodied carbon that can bifurcate product certification requirements.
Technological displacement risks from thermoplastic cores and out-of-autoclave manufacturing that could render legacy processes uncompetitive.
Supply chain bottlenecks for advanced core materials (e.g., specialty honeycomb) during rapid demand spikes.
Execution risk on capacity expansions — late certifications or qualification failures can delay revenue realization and harm ROI.
Practical 2026 playbook — recommended actions by role
Manufacturers: accelerate certification pathways for fire-rated and low‑carbon cores; pilot thermoplastic and recycled core lines; lock multi-year supply agreements with key resin and honeycomb suppliers.
OEMs and system integrators: require material traceability clauses and performance warranties; select suppliers with cross-sector provenings (construction + transport) to reduce qualification cycles.
Investors: prioritize targets with proprietary core technologies, certification pipelines, and demonstrable production scale economies; consider roll-up strategies to capture regional distribution networks.
Procurement leaders: implement hedging strategies for resin/PIR/PUR exposure and qualify alternative chemistries to reduce single‑source dependency.
R&D teams: focus on modular panel platforms that can be tuned for thermal, acoustic, and fire performance while using a common manufacturing footprint.
What you’ll find inside the full PW Consulting report (teaser)
The report is structured as a hands-on playbook for 2026 strategic decisions, including:
Base-year market sizing (2025) and a 2026–2032 forecast with scenario analysis and sensitivity to raw material price swings and regulatory shifts.
Commercially actionable cost models and margin simulations for core and facing combinations, with break-even and payback timelines for CAPEX scenarios.
Supplier and technology maps, including maturity and certification matrices to accelerate procurement and approval processes.
Competitive profiles and benchmarking of leading players with strategic positioning insights and potential partnership vectors.
Go-to-market and M&A playbooks — including target screening templates, valuation heuristics for technology assets, and operational due-diligence checklists.
Case studies illustrating real-world deployments across construction, transportation and aerospace that show how product choices translated into contract wins.
Closing: how PW Consulting helps executives act in 2026
Decisions made in 2026 about certification investments, capacity build-outs, and strategic partnerships will shape competitive positions well into the next decade. PW Consulting’s Composite Sandwich Panels Market report turns macro momentum — documented in our 2020–2025 historical review and 2026–2032 forecast — into a prioritized set of actions, risk mitigations, and investment targets. The report surfaces the underlying mechanics of growth without giving away the granular segmentation that must be tailored to specific enterprise contexts; this ensures that readers get the strategic clarity to act while preserving the detailed intelligence that drives competitive advantage.
For full access to segmented forecasts, supplier scorecards, and the operational toolkits referenced above, consult the complete PW Consulting report and engage our advisory team to translate insights into a 12–36 month execution roadmap.
For detailed analysis of this topic, please visit the official page:Composite Sandwich Panels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com