
Plc Software Market 2026: Strategic Imperatives from PW Consulting’s New Market Research
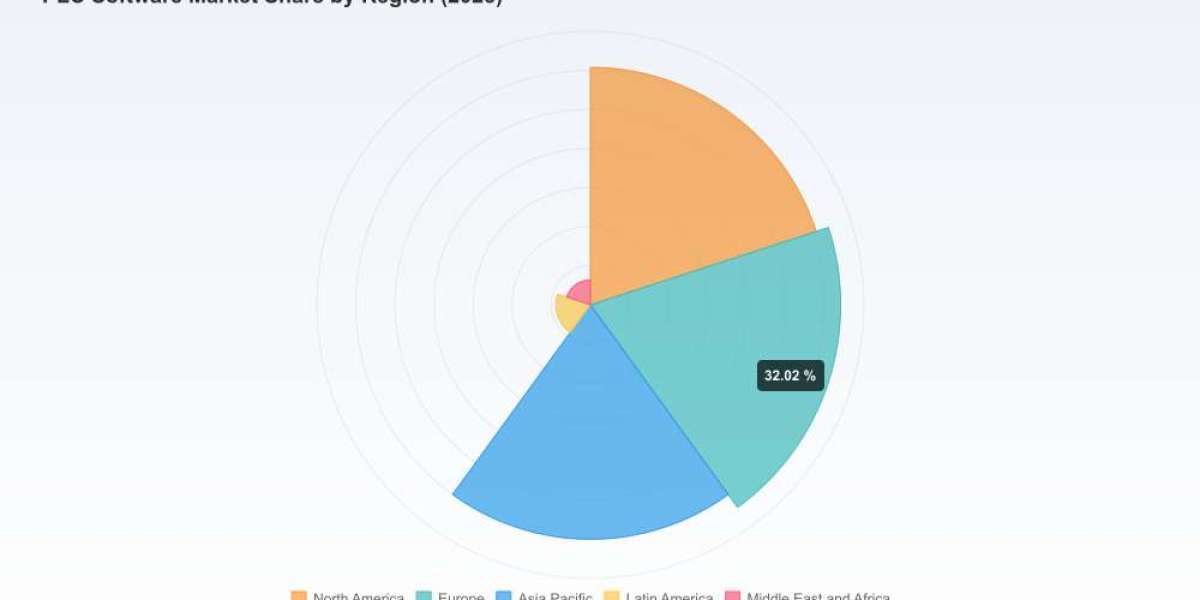
As enterprises and investors recalibrate automation strategies for the post-pandemic industrial landscape, PW Consulting today releases its latest Plc Software Market research brief—an operationally focused guide designed to inform boardroom decisions in 2026. Built on a 2020–2025 historical base with 2025 as the reference year, the study synthesizes market sizing, competitive dynamics, technology trajectories, regulatory shocks, and practical playbooks for adoption, procurement, and risk management. The top-line market story is clear: a healthy mid-single-digit compound annual growth trajectory (CAGR 7.15%) underpins an expansion from a multi-billion-dollar installed base in 2025 toward materially larger scale by 2032, creating near-term opportunities and medium-term structural shifts for platform owners, integrators, and end users.
Double Expansion Anchors Market
Why this report matters to 2026 decision-makers
Operational prioritization: For CIOs and heads of automation, the report translates broad growth indicators into prioritized investment buckets—where to accelerate tooling adoption, and where to defer capital intensity without sacrificing resilience.
Asphalt Blankets MarketVendor strategy: For product leaders and M&A teams, the analysis maps how platform consolidation, cross-vendor interoperability, and embedded AI are reshaping competitive moats—identifying which capabilities command premium valuations and which are becoming commoditized.
Naval Vessels Simulation MarketRisk and compliance: For security, legal, and compliance teams, the brief integrates emerging regulatory requirements and OT cyber-risk vectors into procurement and lifecycle policies—an imperative given recent rules affecting automated decision-making and bulk data handling.
Headline market dynamics (what the numbers imply)
Readers will find the headline trajectory in the report instructive: after steady growth through 2025, the Plc software market is projected to expand at roughly 7.15% CAGR across the 2026–2032 forecast horizon. This pace reflects a blend of steady industrial automation investment, targeted modernization of brownfield assets, and accelerating uptake of software-defined control stacks and GenAI-assisted engineering. Importantly, concentration metrics indicate a market where a few large incumbents retain meaningful share—creating both entry barriers and partnership opportunities. These macro signals together shape the tactical choices enterprises must make in 2026: prioritize modular architectures, invest in vendor-agnostic tooling, and harden supply chains for software and compute components.
What’s new in 2026: technology and regulatory inflection points
AI-augmented engineering: The industry’s adoption of GenAI and code-assistants for PLC programming and code review is transitioning from pilot to production. Leading vendors are embedding assistant workflows into IDEs to accelerate development and reduce time-to-commission.
Software-defined automation & vulnerability management: Multi-vendor orchestration and a shift toward software-defined control are increasing the attack surface for operational technology. This intensifies demand for integrated PLC vulnerability management and secure lifecycle tooling.
Regulatory pressure: New rules—such as obligations around automated decision-making risk assessments and bulk data controls—are converging with OT cyber frameworks. The net effect is actionable: governance, logging, and auditability must become first-class requirements in procurement decisions.
Report anatomy: what’s inside (practical, executable content)
PW Consulting’s brief was written to be applied, not merely observed. Key deliverables included in the package are:
Board-ready executive summary and scenario options for 12–36 month investment horizons.
A vendor selection framework that rates suppliers across engineering productivity, runtime performance, security posture, and ecosystem openness—intended for procurement and integration planning.
Implementation playbooks for three buyer archetypes (greenfield builders, brownfield modernizers, and MSI/contractor partners) with Gantt-style adoption timelines, typical capex/Opex trade-offs, and decision checkpoints.
OT security and compliance templates aligned to recent regulatory developments—ready to be adapted into RFPs and supplier SLAs.
Investment and M&A signal radar: acquisition targets and capability gaps that are most likely to deliver scale or strategic differentiation over a 24–48 month horizon.
Case studies and benchmark KPIs demonstrating measured TCO improvements, productivity uplifts from toolchain consolidation, and deployment time reduction when GenAI-assisted engineering tools are applied.
Competitive landscape: strategic positioning of core vendors
The competitive picture in the Plc software market is dominated by established industrial automation players and a rising set of platform-native innovators. The report’s vendor chapter deep-dives into tactical positioning and strategic intent of the market’s principal actors—illuminating where they play well and where clients should be cautious.
Siemens AG (TIA Portal, STEP 7): Siemens remains a systems-scale competitor, coupling deep PLC ecosystem integration with growing GenAI capability in engineering workflows. Its strength is vertical integration for digital enterprises, but buyers should evaluate lock-in risks tied to broad-system engineering advantages.
Rockwell Automation (Studio 5000 / Logix Designer): Rockwell’s North American installed base and its FactoryTalk ecosystem make it the go-to for customers aligning to EtherNet/IP and regional supply chains. Its platform-centric approach is well-suited to U.S.-centric automation stacks and integrators focused on end-to-end solutions.
Schneider Electric (EcoStruxure Control Expert / Machine Expert): Schneider brings an energy-aware automation narrative to the market, blending IEC programming support with cloud-enabled services. The vendor’s strength lies in cross-domain value—automation plus energy management—useful for organizations with sustainability mandates.
Mitsubishi Electric (MELSOFT GX Works3): With a focus on high-speed precision control and deep presence in Asia-Pacific manufacturing, Mitsubishi is optimized for latency-sensitive applications and high-frequency motion control environments.
Beckhoff Automation (TwinCAT): Beckhoff’s PC-based control and TwinCAT platform continue to attract adopters requiring high-performance compute and advanced motion/CNC capabilities. Its trajectory increasingly emphasizes software flexibility and AI-ready runtimes.
ABB Ltd. (Automation Builder): ABB’s CODESYS-based approach favors interoperability and modular drive/motion integration—positioning it for infrastructure and industrial customers who value standardized runtime and scalable engineering.
CODESYS Group (Development System): As an IDE and runtime standard across many hardware OEMs, CODESYS plays a pivotal role in multi-vendor strategies; it is a strategic enabler for firms seeking portability and vendor neutrality.
The report juxtaposes these vendor profiles against market-concentration metrics and recent product activity. It also maps where new entrants and open-standards projects—particularly those emphasizing version control, multi-vendor vulnerability management, and remote lifecycle features—are eroding traditional differentiation.
Recent developments that alter strategic priorities
Product innovation: The emergence of integrated AI-powered engineering tools, highlighted at industry events in early 2026, materially shortens engineering cycles but requires new validation and security controls.
Field tooling evolution: Platform updates that include remote lifecycle management and multi-vendor orchestration change maintenance economics—shifting spend from field service to centralized software operations.
Regulatory and security shocks: Recent regulations around automated decision-making and bulk data handling, and increasingly publicized OT vulnerabilities, mean buyers must bake compliance and cyber-resilience into both procurement and operational playbooks.
Strategic recommendations for enterprise leaders in 2026
Adopt an interoperability-first procurement policy: Require vendor roadmaps and open API commitments; design for modular substitution to avoid single-vendor lock-in.
Mandate security-by-design for PLC software: Integrate vulnerability management and OT security metrics into SLAs; require demonstrable lifecycle controls and audit trails to meet new regulatory expectations.
Run phased GenAI pilots with strong guardrails: Begin with assistant-driven code reviews and test automation before extending to autonomous code generation; instrument for explainability and rollback control.
Align modernization to business-critical KPIs: Prioritize upgrades that reduce downtime and accelerate product changeover cycles; measure outcomes against a short set of operational KPIs to justify scale-up.
Prepare M&A playbooks: For strategics and PE, target assets that enhance interoperability, deliver security tooling, or accelerate AI-assisted engineering capabilities.
Concluding note: how to use the full report
PW Consulting’s Plc Software Market report is constructed as an operational toolkit for 2026—combining macro forecasts, concentrated competitive insight, regulatory analysis, and prescriptive playbooks. The public summary above provides the strategic contours; the full report contains the diagnostic templates, vendor scoring models, and scenario-specific financials that enterprise teams and investors will need to convert strategy into action. We deliberately withhold granular subsegment disclosures in this public release to preserve the report’s role as a decision-enabling resource and to direct practitioners to the full dossier for implementation-ready detail.
To access the complete report, proprietary benchmarks, and model inputs—along with a customized briefing for your executive team—visit PW Consulting’s Plc Software Market report page or contact our research desk for a tailored engagement.
For detailed analysis of this topic, please visit the official page:Plc Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com