
Worldwide Aescin Market — Strategic Outlook for 2026: Navigating Therapeutic Potential, Supply Dynamics and Regulatory Nuance
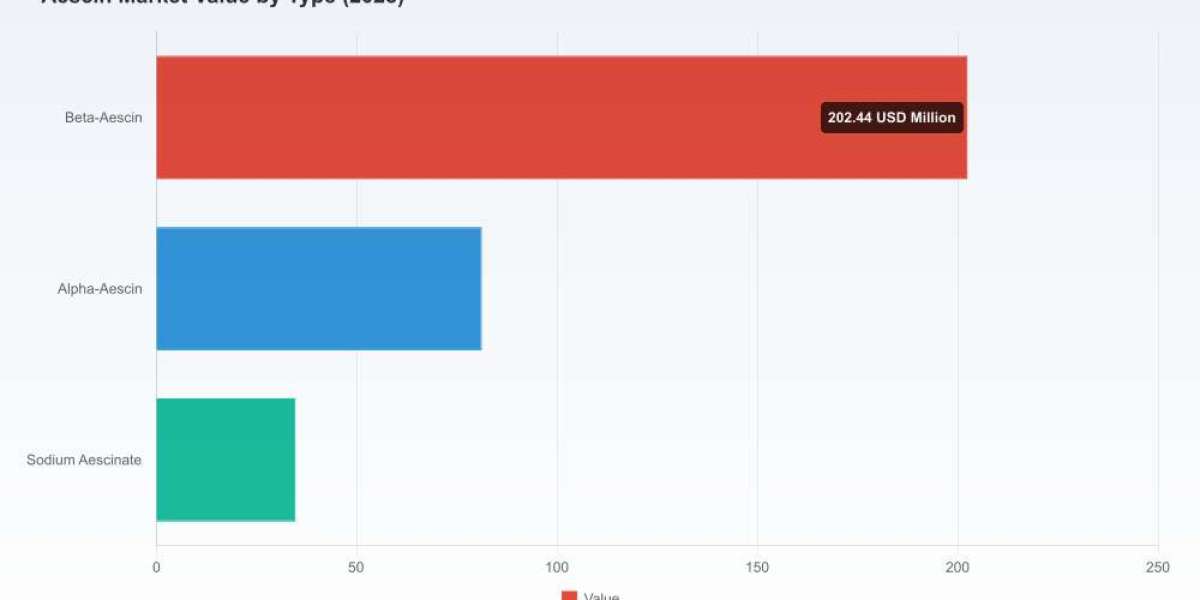
PW Consulting’s new Worldwide Aescin Market report is the definitive briefing for executives preparing strategic decisions in 2026. Anchored in a 2020–2025 historical analysis and a 2026–2032 forecast horizon, the study synthesizes market sizing, regulatory dynamics, raw-material risk, competitive positioning and commercial pathways. The global market reached approximately USD 318.5 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 4.62% through 2032, when headline revenues approach the mid‑400s million USD range. This release summarizes the strategic takeaways while reserving granular segment splits and model outputs for the full report.
Natural Bakery Mixes Market
Executive snapshot: why this matters in 2026
Incremental but resilient growth. The Aescin market is expanding at a steady mid-single digit CAGR driven by durable demand in therapeutic and wellness categories. Growth is non-linear — short-term inflections reflect pricing, raw-material availability and episodic reimbursement changes — creating both timing-sensitive opportunities and tactical risk.
Worldwide Mobile Collaboration Software MarketFragmented value chain with concentrated pockets. While a handful of incumbents exert notable commercial influence, the overall landscape is sufficiently fragmented to enable partnerships, vertical integration and niche premium plays.
Worldwide Satellite Communication System MarketRegulatory arbitrage and evidence gaps. Divergent regulatory treatment across major markets (herbal medicinal authorisations in parts of Europe vs. supplement classification in the US) creates strategic choices around clinical investment, labeling and go-to-market structure.
Market dynamics and growth drivers
Demand drivers are clustered around three vectors: (1) medical use for venous and microcirculatory conditions, where established clinical and regulatory precedents support prescriber and payer recognition; (2) aesthetic and topical applications in cosmetics and personal care, where claims and formulation convenience spur adoption; and (3) nutraceutical positioning in markets that permit non‑prescription dietary supplements. These vectors operate against a backdrop of aging populations, rising prevalence of venous disorders, and consumer willingness to invest in preventative vascular health.
Supply‑side dynamics are shaped by botanical sourcing, extraction yields and standardization practices. The botanical raw material (horse chestnut seeds) contains aescin as a class of triterpene glycosides, and typical saponin concentrations in the dry seed are an input variable companies must actively manage in procurement and quality protocols. These upstream variances directly affect cost of goods, batch-to-batch consistency and margin management for extractors and formulators.
Regulatory and reimbursement landscape — practical implications
European medicinal recognition: Certain jurisdictions in Europe authorise horse chestnut seed extract for symptomatic treatment of chronic venous insufficiency under specific dosing frameworks; regulatory precedents include minimum-escin dosing thresholds that underpin product monographs. This creates a pathway for prescription and reimbursed use where clinical evidence and dossier quality meet payer thresholds.
United States: Aescin-containing products are generally positioned as dietary supplements. That classification short-circuits the pharmaceutical approval pathway but limits therapeutic claims and may introduce safety communications — notably cautions relating to renal effects and bleeding risk. Market entrants must therefore balance claim ambition against compliance risk.
National reimbursement examples: In selected European markets, certain topical aescin formulations are included within statutory reimbursement schemes. Such listings materially alter commercial economics and distribution strategies; gaining or maintaining reimbursement status is a high-impact objective for manufacturers targeting clinical adoption.
Competitive architecture — who to watch and how to act
The report profiles leading participants across extraction, formulation and finished‑product segments. Representative company archetypes include specialized extractors and botanical firms that supply standardized aescin fractions to pharmaceutical and nutraceutical clients, and integrated phytotherapy companies that launch finished‑dose products for venous health.
Specialized extractors (example profile): Firms with long-standing botanical extraction platforms supply standardized horse chestnut extracts to pharmaceutical and nutraceutical customers. Their technical differentiators include extraction chemistry, standardization to active fractions and supply‑chain traceability.
Phytotherapy-focused manufacturers (example profile): Companies that combine in-house R&D with downstream formulation capabilities and direct-to-consumer or practitioner channels benefit from owning therapeutic narrative and capturing higher value.
Clinical-pedigree brands (example profile): Established topical and oral brands that have navigated national reimbursement or maintain clinical positioning hold defensible commercial niches, especially in markets where prescriber trust and formulary placement matter.
Strategic moves to monitor: contract manufacturing tie-ups, long-term supply agreements with seed processors, clinical trial starts that underpin label expansion or reimbursement submissions, and geographic expansion that exploits regulatory asymmetries. The market’s competitive concentration is moderate: the top three players collectively account for roughly one-third of commercial activity while the top five remain under half of total revenues — a structure that supports both consolidation plays and differentiated niche strategies.
Supply‑chain risk and raw‑material strategy
Raw-material risk is the single largest controllable operational factor. Because aescin yield varies by harvest and processing, procurement strategies that blend multi-year contracts, geographic diversification, and supplier development deliver resilience. Producers that invest in upstream agronomy support, quality certification and extraction technology can translate botanical variability into a commercial advantage by guaranteeing standardized potency to downstream customers.
Operational priorities for 2026:
Secure multi‑season supply contracts with built-in quality clauses tied to active fraction assays.
Pursue backward integration selectively where scale economics and access to high‑quality seed justify capital expenditure.
Develop contingency inventory and toll-processing arrangements to smooth production and avoid costly stockouts.
Clinical, regulatory and commercial playbook for 2026
Companies face a strategic inflection point: invest in clinical evidence to pursue expanded medicinal claims and reimbursement, or optimize for fast-to-market supplement/cosmetic channels where claims are constrained but go-to-market is faster. Each path has trade-offs.
Evidence-first strategy: Target markets with established medicinal frameworks. Build randomized controlled trial (RCT) programs that match payer expectations and prepare dossiers for national submissions. This path is capital and time intensive but yields better pricing and formulary access.
Consumer-facing speed strategy: Prioritize topical and OTC formulations with differentiated delivery systems, claims permissible under supplement/cosmetic rules, and strong retail and e-commerce distribution. Complementary investments in safety pharmaco-vigilance and label transparency mitigate regulatory downside.
Hybrid models: Use supplements and cosmetic launches to fund clinical programs in parallel, leveraging brand recognition and real-world data to accelerate adoption in medicinal channels.
Practical recommendations for boardrooms and commercial teams
For organizations preparing budgets and M&A plans in 2026, PW Consulting recommends a prioritized set of actions:
Allocate capital to clinical validation in markets where medicinal classification enables reimbursement; prioritize studies that measure functional outcomes payers value.
Negotiate multi-year raw-material agreements with quantifiable quality metrics, and embed price‑adjustment mechanisms to moderate harvest volatility.
Segment go-to-market by regulatory regime: tailor labeling, claims and distribution to local frameworks rather than pursuing single global claims.
Pursue targeted M&A or JV activity to secure extraction capacity, route-to-market in high-value geographies, or access to premium botanical supplies.
Invest in safety communication and post-market surveillance to address known cautions and protect brand trust in the US and other supplement markets.
What the PW Consulting report delivers — actionable contents reserved for subscribers
The full report provides the operational intelligence required to execute the recommendations above, including:
Proprietary market-sizing model with scenario outputs to 2032 and sensitivity testing for price, raw-material yield and reimbursement changes.
Commercial forecasts by product type, application and region (detailed splits available in the subscriber dataset).
Supply‑chain mapping with supplier scorecards, extraction economics and recommended contract terms.
Regulatory playbooks for major jurisdictions, including dossier checklists for medicinal submissions and compliant labeling frameworks for supplements/cosmetics.
Competitive due diligence profiles of leading extractors, phytotherapy manufacturers and brand owners, plus a framework for M&A prioritization and valuation guidance.
Go-to-market templates, pricing strategy models and a risk matrix covering raw-material shocks, safety communications and regulatory enforcement scenarios.
Conclusion — positioning for advantage in 2026
The aescin value chain offers pragmatically attractive choices: the ability to pursue premium medicinal positioning in regulated markets, or to scale faster in consumer wellness channels. The decisive factor for 2026 is execution: firms that align procurement resilience, evidence generation and regulatory strategy will capture the disproportionate returns available as the market expands at an expected mid-single digit CAGR through 2032.
PW Consulting’s full Worldwide Aescin Market report contains the granular segment-level tables, regional breakdowns and executable templates necessary to convert these strategic insights into operational plans. For access to the complete data, proprietary models and bespoke advisory services, consult the full report and accompanying datasets.
For detailed analysis of this topic, please visit the official page:Worldwide Aescin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com