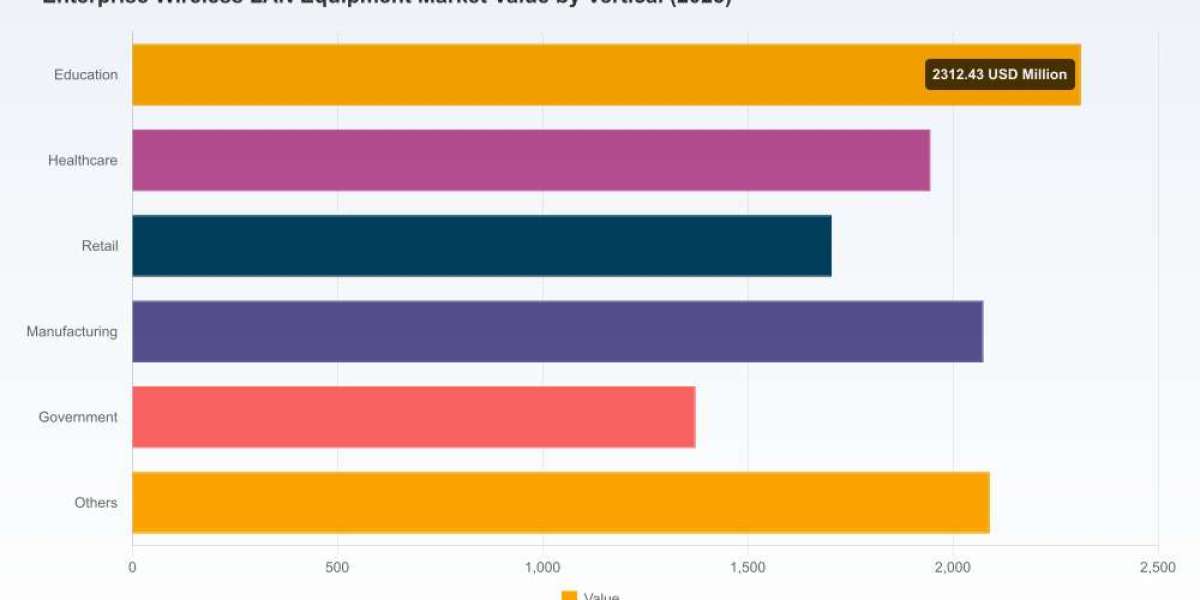

Worldwide Enterprise Wireless LAN Equipment Market: Strategic Imperatives for 2026
As enterprises plan capital and operating expenditures for 2026, the global Enterprise Wireless LAN (WLAN) equipment market presents a clear growth arc and a complex decision environment. According to PW Consulting’s latest market study — with a 2025 base year and a 2026–2032 forecast horizon — the market reached approximately USD 11.5 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.5% through the forecast window, reaching roughly USD 19.1 billion by 2032. These headline numbers tell an important story: Wi‑Fi continues to evolve from commodity infrastructure into a strategic platform for connectivity, security, and digital experience management.
Worldwide Humidification Fan Market
Why this report matters for 2026 decision-makers
Actionable foresight: The study translates macro growth into operational levers that CIOs, CTOs, facilities and network managers can use to prioritize investments across campuses, branch offices, manufacturing floors and healthcare settings.
Catena-X Data Ecosystem MarketRisk-informed procurement: With regulatory changes, supply-chain friction, and rapid product cycles—particularly around Wi‑Fi 7—procurement teams need a defensible, scenario-based approach to timing purchases, specifying requirements, and managing vendor risk.
Mortar Grinder MarketOperational transformation: The report goes beyond vendor product lists to assess operational models (on‑premises controllers vs cloud management, AI-driven assurance, and integration with SASE/SD‑WAN) and quantifies the trade‑offs for performance, TCO and staffing.
Security and compliance: New certification and security baselines (including WPA3‑Enterprise adoption and region-specific procurement restrictions) require integrated network-security planning that the report models for different enterprise archetypes.
What’s inside the study: practical deliverables
Market sizing and scenarios — robust historical reconstruction (2020–2025) and three forward-looking scenarios to 2032, designed to help you stress-test capital plans against optimistic, baseline and downside demand paths.
Decision playbooks — migration roadmaps (Wi‑Fi 6→6E→7), cabling and backhaul checklists, PoC templates, and five procurement strategies (fast refresh, phased replacement, best‑of‑breed aggregation, single-vendor consolidation, and managed-service outsourcing).
TCO models and budgeting templates — customizable calculators that incorporate device CAPEX, cabling/backhaul upgrades (including guidance on Category 6A and 10G backhaul needs), power and cooling, software and license renewal patterns, and staff/managed service cost comparisons.
Vendor decision frameworks — vendor scorecards that evaluate runtime telemetry and AI capabilities, cloud management maturity, security posture, hardware roadmap alignment to Wi‑Fi 7, and ecosystem integration with SD‑WAN, SASE and NAC solutions.
Regulatory and spectrum implications — an assessment of how recent rulings (for example, expanded indoor use in 6 GHz in certain jurisdictions) and procurement restrictions are likely to affect supplier selection, geographic sourcing, and managed service options.
Operational readiness checklists — from RF site survey practices for multi‑link and multi‑band deployments to test plans for latency‑sensitive use cases (real‑time collaboration, augmented reality, industrial control), and a security hardening playbook aligned to WPA3‑Enterprise and Zero Trust principles.
Market dynamics shaping 2026 strategies
Technology inflection: Wi‑Fi 7 (802.11be) is moving from specification to deployment. Multi‑link operation and higher spectral efficiency materially change capacity planning and AP placement considerations. Enterprises that delay upgrading may face hidden costs in increased AP density and degraded user experience.
Spectrum and regulation: Recent regulatory shifts enabling expanded indoor 6 GHz use in select markets lower a key barrier to multi‑gig deployments but simultaneously raise interoperability and coexistence questions. Our report maps regulatory permutations and recommended procurement clauses to mitigate future rewiring or radio‑tuning costs.
Security and certification: With certification programs tightening and WPA3‑Enterprise broadly required for modern WLANs, security is now an integral procurement filter. The report provides a vendor‑agnostic framework to evaluate firmware provenance, supply‑chain hygiene, and integration with enterprise identity services.
Infrastructure cost pressure: Adoption of Wi‑Fi 7 requires commensurate uplink capacity. The requirement for higher-grade cabling and 10G backhaul is a material line item for capital planning in 2026 projects; our models quantify breakpoints where backhaul upgrades become the dominant cost.
Operational intelligence: AI‑driven assurance platforms (cloud or hybrid) have matured to provide predictive troubleshooting and automated remediation. The report quantifies expected reductions in mean time to repair and network‑ops headcount under different automation adoption rates.
Competitive landscape — how vendors are positioning for growth
The market is led by established networking OEMs and cloud‑first entrants, each pursuing distinct routes to capture growth in enterprise WLAN. Our qualitative and quantitative analysis examines product roadmaps, cloud management strategies, channel models, go‑to‑market tactics, and R&D direction for a set of core vendors. Highlights include:
Large incumbent networking vendors that pair portfolio breadth (switching, security, WLAN) with deep channel and enterprise services capabilities, increasingly emphasizing cloud‑managed lines and higher‑speed APs.
Cloud‑native and AI‑driven players focusing on assurance, experience analytics and simplified operations, often leveraging narrow but deep integrations with third‑party security stacks and SD‑WAN.
Cost‑focused challengers offering compelling price‑performance for distributed sites and SMB segments, while enhancing cloud management and security features to move upmarket.
Regional and alternative suppliers that address specific geo‑regulatory and procurement constraints with localized supply chains and tailored services.
The report includes vendor profiles and recent product and go‑to‑market developments to inform shortlists; for example, several suppliers introduced Wi‑Fi 7 enabling platforms and new cloud management features in the past 12–18 months, and industry certification programs for Wi‑Fi 7 interoperability are now active. We analyze these changes and assess their near‑term impact on enterprise rollout plans.
Strategic recommendations for 2026
Adopt a two‑track migration strategy: protect critical latency‑sensitive services with selective early Wi‑Fi 7 deployments while using staged refresh for best‑value footprints in non‑critical areas. Use PoCs targeted at the highest ROI facilities before rolling out campus‑wide.
Budget holistically: incorporate cabling/backhaul, power, software licensing, and lifecycle replacement into a single TCO view instead of siloed CAPEX lines. Our downloadable budget templates are calibrated to real project archetypes.
Lock in vendor interoperability and lifecycle commitments: require multi‑vendor interoperability testing, software support SLAs, and explicit upgrade paths in procurement contracts to hedge against rapid product cycles.
Prioritize observability and AI operations: expect operational savings and improved end‑user experience when investing in telemetry and assurance platforms. Plan for integration with ITSM and security telemetry for rapid incident correlation.
Design for regulation and supply chain resilience: include alternative sourcing clauses and firmware attestations in contracts where geopolitical or procurement restrictions apply.
How to use this report in your 2026 planning cycle
Network, security, and procurement leaders should use the report as both a planning toolkit and a vendor due‑diligence resource. Recommended next steps include running a short‑form TCO exercise across three rollout scenarios, conducting vendor PoCs using our test plans, and mapping regulatory exposure for regions in your portfolio. For MSPs and system integrators, the playbooks provide packaged services and pricing templates to accelerate go‑to‑market efforts.
Closing — why PW Consulting’s perspective is distinct
Our research combines granular device‑level review, vendor roadmap tracking, regulatory mapping, and enterprise deployment economics into an actionable, practitioner‑focused report. We intentionally provide market‑level numbers and scenario guidance here to inform executive prioritization while reserving the segmented datasets, vendor share tables, regional forecasts and downloadable decision tools for the full report and online portal. That structure is deliberate: we want your team to start strategic conversations now, and then use the report as the operational manual for 2026 rollouts.
To access the full dataset, vendor scorecards, customizable TCO models and downloadable playbooks — and to book a briefing with our enterprise networking practice — visit the PW Consulting report landing page for Worldwide Enterprise Wireless LAN Equipment Market.
— PW Consulting, Global Networking & Infrastructure Practice
For detailed analysis of this topic, please visit the official page:Worldwide Enterprise Wireless LAN Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com