
PW Consulting: Strategic Brief — Worldwide Pouchitis Treatment Market (2026 Decision Playbook)
PW Consulting today publishes an executive briefing that distills the strategic implications of our comprehensive Worldwide Pouchitis Treatment Market study for executives making go/no-go, investment, and commercialization decisions in 2026. Built on a detailed market model covering 2020–2025 (base year 2025) and a forecast window through 2032, the study shows the pouchitis treatment market expanding at a compound annual growth rate (CAGR) of 7.8% and reaching approximately USD 1.2 billion by 2032. Between 2020 and 2025 the market scaled materially — a signal that clinical, regulatory and payer inflection points are aligning to reward differentiated clinical value. This brief explains how senior leaders should convert those macro dynamics into specific, time-bound actions in 2026.
Worldwide Children Mask Market
Why 2026 Is a Strategic Inflection Point
Confluence of regulatory and clinical momentum: Europe already has a therapy with formal marketing authorization for a defined chronic pouchitis label, while the U.S. still lacks an indication-specific approval. That regulatory asymmetry is catalyzing both regional clinical programs and cross-border licensing conversations.
Worldwide Ultra Isolation Transformers MarketPipeline reshaping: Next‑generation approaches — notably live biotherapeutic products and targeted immunomodulators — are transitioning from Phase 2 into pivotal-ready designs. Recent IND clearances and indication selections mean 2026 will be the year where several programs decide whether to scale capacity and raise the financing needed for late‑stage trials.
Cross Laminated Timber for Mid-rise and High-rise Construction MarketCommercial concentration and competitive posture: Market share is meaningfully concentrated among a small number of established gastroenterology and pharma players, giving those incumbents leverage over formulary access and clinical guideline narratives. At the same time, the profile of entrants (biologics, probiotics/biotherapeutics, antibiotic incumbents) creates a two-speed market — predictable demand for first‑line antibiotic care versus high-margin opportunities for differentiated chronic‑disease therapies.
Economic pressure on payers and providers: Pouchitis carries measurable incremental healthcare cost burdens following IPAA surgery. Payer scrutiny on outcomes and comparative value will intensify as higher-cost biologics and novel live biotherapeutics approach registrational decision points.
What PW Consulting’s Report Delivers — Practical, Transaction-Ready Content
Proprietary forecasting engine: an editable model with base-year calibration (2025) and scenario toggles for clinical success rates, price erosion, and reimbursement timelines across the forecast horizon (2026–2032).
Clinical and regulatory dossier: deep summaries of pivotal and supportive trials, regulatory precedents (including the European authorization case), and recommended designs for Phase 3 and registrational programs tailored to both EMA and FDA pathways.
Payer value-messaging playbook: evidence gaps mapped to payer decision criteria, health economic modelling templates, and suggested real‑world evidence (RWE) study designs to accelerate formulary acceptance.
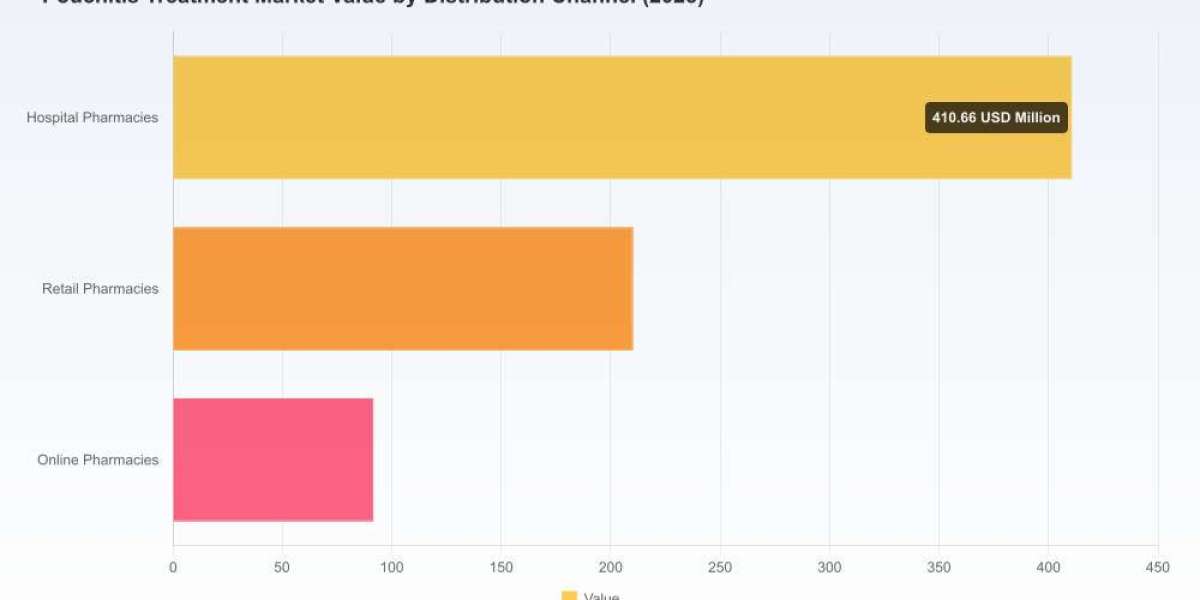
Commercial launch and channel archetypes: segmentation of distribution channels and go‑to‑market sequencing options, with operational checkpoints and staffing templates for hospital, retail, and digital/pharmacy channels.
Competitive and pipeline tracker: forensic company profiles, technology-readiness assessments, and trigger‑based calendars that identify critical windows for partnering, licensing and M&A.
Investment and transaction toolkit: valuation sensitivities, synergies checklists, and integration risk matrices for strategic and financial buyers.
Risk and contingency heatmap: prioritized operational, regulatory and market risks with mitigation playbooks and quick‑win tactics to preserve optionality through 2026.
Competitive Landscape — Who Matters and Why
Large pharma incumbents maintain a dominant commercial and clinical footprint. Established biologics and antibiotic portfolios position these firms to defend share in both acute and chronic settings through label extensions, guideline influence and payer contracting.
Specialist gastroenterology players (including firms with established probiotic and GI-focus portfolios) are actively defending niche channels and clinician relationships that capture routine maintenance and supportive care prescriptions.
Next‑generation entrants — live biotherapeutic developers and targeted immunomodulators — are the most important source of disruption. Their clinical differentiation (durable remission without continuous antibiotic exposure) will determine whether the market bifurcates into a low-cost, high-volume antibiotic segment and a higher-cost, outcomes‑driven specialty segment.
Selected corporate moves to watch: Recent activity includes an immunotherapy developer selecting chronic pouchitis as a new indication and planning a Phase 2, and a live biotherapeutic firm securing regulatory clearance to advance a larger ulcerative colitis program after promising pouchitis data. These moves foreshadow a clustered period of readouts and financing decisions in 2026.
Representative companies analyzed in the report include leading global pharmaceutical firms with GI portfolios, specialist gastroenterology companies, probiotics/biotherapeutic developers, and several clinical-stage entrants. For each, our analysis provides strategic options (in‑license vs. build), likely timeline to commercial relevance, and bargaining power at the point of formulary negotiation.
Regulatory, Clinical and Reimbursement Dynamics — The Operational Implications
Regulatory precedent: A treatment has received formal authorization in Europe for a defined chronic pouchitis population — an important proof point that a regulatory path exists for indication-specific approval. By contrast, no therapy has explicit FDA approval for pouchitis to date, which creates both opportunity and uncertainty for U.S.-focused programs.
Clinical standard of care: Antibiotics such as ciprofloxacin and metronidazole remain the preferred first-line approach for acute pouchitis per clinical guidelines, underscoring the need for new entrants to demonstrate superiority on durable remission and safety to justify higher prices.
Payer evidence expectations: Because pouchitis can drive higher gastrointestinal-related inpatient and pharmacy costs post‑IPAA, payers are receptive to interventions that demonstrably reduce downstream resource use — but they require robust health economic and RWE packages to change formulary placement.
Trial design considerations: Guideline recommendations restrict certain interventions (for example, conventional fecal microbiota transplantation outside trials), which both channels innovation into controlled clinical settings and raises the bar for demonstrating reproducible, regulatory‑grade outcomes.
Actionable Strategic Priorities for 2026
Prioritize indication and label strategy: Decide early whether to pursue narrow, regulator‑friendly chronic labels or broader symptom‑based claims — each requires different evidence and payer strategies.
Invest in differentiated endpoints: Emphasise durable clinical remission, steroid‑sparing effects and reduced hospitalizations in registrational and RWE programs to accelerate payer uptake.
Align pricing to value: Use early health economic modeling to set price and discount frameworks that accommodate payer risk‑sharing and outcomes contracts.
Plan manufacturing and supply with optionality: For live biotherapeutics and biologics, de‑risk capacity choices through dual‑source agreements and scalable fill/finish partners.
Use partnerships strategically: Consider co‑development with gastroenterology specialists, or licensing deals in geographies where regulatory precedent or commercial channels differ materially.
Design RWE to win formulary debates: Commit to prospective registries that capture resource utilization and QoL metrics aligned with payer priorities.
Prepare for selective M&A: With moderate concentration among top incumbents, identify bolt‑on targets that shore up access to high-value channels or proprietary clinical assets.
How PW Consulting Enables Faster, Safer Decisions
Executive dashboards that convert the report’s model into board-ready scenarios (best/worst/most‑likely), including sensitivity to pricing, uptake and trial outcomes.
Due diligence packs for investors: legal/regulatory red flags, clinical comparators, and integration playbooks.
Commercial launch blueprints: payer negotiation scripts, clinician engagement plans, and digital patient support frameworks tailored to hospital and retail distribution realities.
Custom workshops: 2‑day strategy sprints to align R&D, commercial and finance teams on 2026 milestones and go/no‑go gates.
Our “trailer” approach in this press release is intentional: we reveal the macro growth trajectory and the decisive strategic choices companies face in 2026, while detailed segmentation, proprietary unit‑share models, and granular regional/application numbers are available in the full report and interactive subscription tools. For teams evaluating investment, licencing or launch decisions in pouchitis, the report provides the specific inputs, scenarios and tactical templates necessary to act with conviction.
Next Steps
PW Consulting invites executives and investors to request the full report or schedule a briefing to review the model and tailored implications for a specific program or portfolio. In fast-moving therapeutic niches such as pouchitis, early alignment between clinical development and commercial strategy is the most reliable route to protect value and accelerate patient access — 2026 will reward those who plan with both rigor and speed.
For detailed analysis of this topic, please visit the official page:Worldwide Pouchitis Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com