
Worldwide CMP Slurry for Substrate Market — Strategic Outlook for 2026 Decision‑Makers
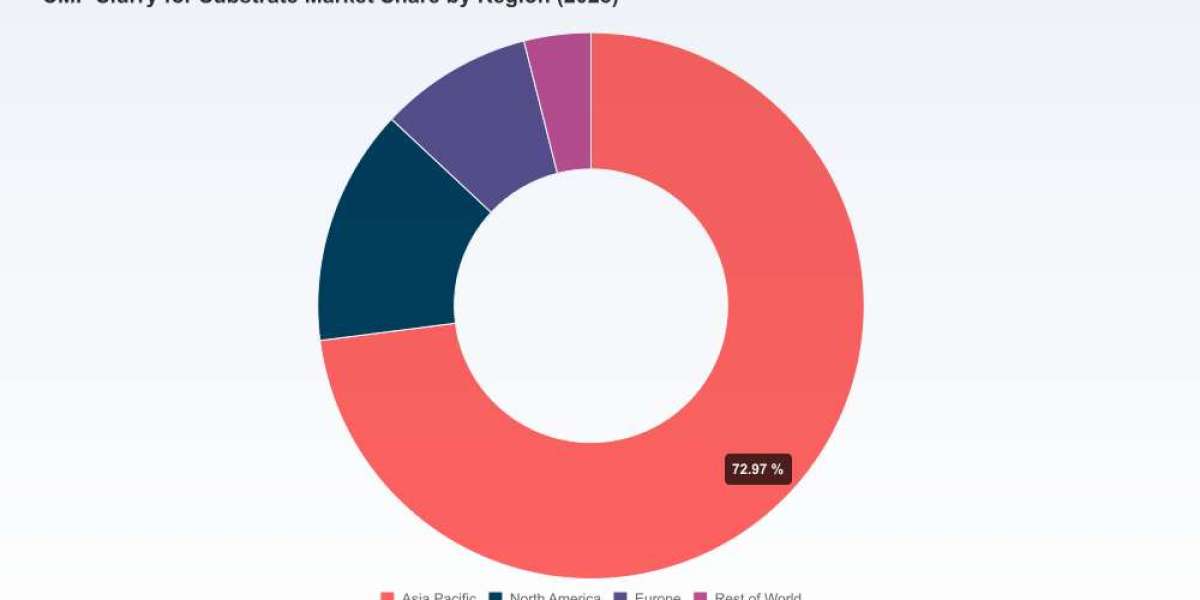
PW Consulting’s new market intelligence brief on the Worldwide CMP (chemical mechanical planarization) Slurry for Substrate market is designed as an executive-grade planning instrument for companies making high‑stakes sourcing, R&D, capacity and M&A decisions in 2026. Our proprietary model shows the market expanding from an estimated USD 565.0 Million in 2025 to approximately USD 981.8 Million by 2032, representing a compound annual growth rate (CAGR) of 8.21% over the forecast horizon. This release summarizes the strategic implications and hands-on levers executives should prioritize; detailed segmental tables and regional splits are deliberately reserved for the full report to preserve the trailer-style approach to insight delivery.
Polycrystalline Alumina Blankets Market
Why this report matters for 2026
- Translate macro momentum into actionable plans: the mid‑2020s inflection in substrate complexity (SiC, GaN, sapphire, and ultra‑thin silicon) demands targeted slurry solutions — and rapid strategic responses from suppliers and end users.
- Inform capital allocation: our forecasts and sensitivity analyses provide the basis for CAPEX prioritization across production footprint, R&D pipelines, and capacity expansions.
- De‑risk supply chains: the report maps critical raw‑material exposures and prescribes procurement and hedging playbooks tuned for current trade and regulatory dynamics.
- Support commercial strategy: vendor selection frameworks and competitor benchmarking enable faster go/no‑go decisions on partnerships, licensing and bolt‑on acquisitions.
Market dynamics shaping 2026 strategy
The substrate polishing market is being reshaped by a confluence of technology adoption and supply‑side constraints. Rapid uptake of wide‑bandgap semiconductors (SiC and GaN) for power electronics, continued demand for sapphire in optoelectronics, and the persistent drive for higher yield in advanced packaging are each increasing the technical sophistication required from CMP slurries. These shifts are accelerating demand growth while raising margin dispersion between commodity silica formulations and high‑performance abrasives engineered for ultra‑hard substrates.
Worldwide Smart Access Control Attendance Machine Market
On the supply side, three structural forces demand immediate attention from executives:
Worldwide Vacuum Coffee Pouch Market
- Raw material concentration and price volatility — the cerium ecosystem and other key nano‑abrasives remain geopolitically sensitive. Our sector analysis highlights how dependence on a small set of producers can amplify cost and delivery risk.
- Regulatory tightening — environmental and chemical handling rules, especially in major manufacturing regions, are increasing operational complexity and compliance cost for slurry producers and their customers.
- Trade measures and tariffs — recent policy actions affecting precursor chemicals and nano‑abrasives have elevated landed costs and prompted near‑term rethinking of sourcing and local production strategies.
Competitive landscape: what to watch
The market exhibits concentrated leadership with a small set of global incumbents commanding a large share of high‑end substrate slurry volumes, complemented by a diverse set of regional specialists and emerging players. Our concentration metrics indicate that top-tier suppliers hold a dominant position across premium substrate segments, shaping technology roadmaps and customer expectations.
Across the competitive set, strategic patterns are clear:
- Engineering differentiation — leaders invest in proprietary chemistries and process engineering to win epi‑ready polishing and low‑defect applications for hard substrates.
- Proximity and capacity plays — several major suppliers have recently expanded production nearer to foundry and wafer fabrication clusters to shorten lead times and co‑develop solutions with customers.
- Portfolio diversification — established players are broadening offerings from commodity oxides into specialty ceria, engineered alumina and hybrid formulations to capture higher margins.
Notable strategic moves in the recent cycle illustrate these trends: new product launches focused on advanced packaging copper CMP, targeted capacity expansions in foundry‑adjacent locations, and next‑generation cerium formulations aimed at sub‑5nm process tolerances. For buyers and investors, these moves signal both opportunity and the need for vendor validation beyond press statements — something the full report supports with comparative product matrices and technology readiness assessments.
What the PW Consulting report delivers (operationally actionable)
- Proprietary market model and forecast to 2032, including scenario variants reflecting raw‑material shocks and tariff regimes (note: granular segment/regional breakdowns are included only in the complete dataset).
- Supplier benchmarking pack — capability maps, product fit‑for‑purpose matrices, capacity footprints and recent investment timelines for leading and challenger vendors.
- Supply chain stress test — multi‑factor sensitivity analyses (raw material price swings, export controls, regulatory cost shocks) and recommended mitigation portfolios.
- Cost build‑up templates — bottom‑up production cost models adaptable to local input prices, labor and environmental compliance differentials.
- Technology and application guides — slurry selection heuristics across substrate hardness, target roughness, defectivity and throughput tradeoffs.
- Regulatory compliance and ESG checklist — actions and cost estimates required to meet evolving chemical handling and waste management standards in key manufacturing hubs.
- M&A and partnership playbook — valuation primers and integration checklists for buyers targeting specialty abrasive platforms or regional manufacturing scale.
- Customizable executive dashboards — KPI sets and trigger thresholds for procurement, R&D prioritization and capacity deployment decisions.
Priority strategies for 2026 (recommended)
- Secure raw‑material access: establish multi‑tier sourcing, strategic inventory buffers and material‑level hedges for cerium, colloidal silica and engineered alumina. Consider long‑term supply agreements with geographically diversified suppliers or invest in upstream capabilities where feasible.
- Localize critical capacity: move beyond cost rationales to strategic proximity — local production near major foundry clusters reduces lead times, facilitates co‑development, and mitigates tariff exposure.
- Differentiate via formulation and service: prioritize investment in high‑value slurry chemistries tuned for SiC, GaN and sapphire, and offer technical services (process integration, on‑site support) to lock in customers.
- Build environmental compliance as a competitive moat: early investments in waste‑treatment, closed‑loop systems and transparent reporting will reduce future disruption and unlock customer contracts in regulated jurisdictions.
- Employ an agile partnerships approach: accelerate qualified supplier lists, explore joint R&D with foundries for co‑optimized consumables, and consider bolt‑on acquisitions to rapidly expand specialty capabilities.
- Prepare adaptive pricing and contract strategies: incorporate input‑cost passthrough clauses and dynamic pricing models to protect margins against raw‑material and tariff shocks.
How to operationalize the insight in 90–180 days
- 90‑day sprint: complete a raw‑material exposure assessment, launch supplier qualification for secondary sourcing, and run a pilot localization feasibility study for one high‑value customer cluster.
- 180‑day plan: finalize CAPEX priorities informed by our scenario outputs, sign at least one strategic supply agreement with material price protection, and deploy an updated supplier scorecard across procurement and quality functions.
- Ongoing: integrate the PW Consulting KPI dashboard into monthly commercial reviews and schedule quarterly technology calibration sessions with R&D and key customers.
About the release and next steps
This briefing intentionally highlights strategic and operational takeaways while withholding granular regional and application‑level data that are included in the full PW Consulting report package. Those detailed segmentations, downloadable data packs and model files are the centerpiece of the paid report and are intended for teams executing procurement, R&D road‑mapping and corporate development programs in 2026 and beyond.
To access the complete dataset, supplier scorecards, and the downloadable scenario models that underpin the forecasts and recommendations summarized above, please visit the PW Consulting reports page or contact our client services team for a tailored briefing. Our analysts can also provide a custom workshop to apply the findings directly to your company’s portfolio and operational plans for 2026.
For detailed analysis of this topic, please visit the official page:Worldwide CMP Slurry for Substrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com