
Worldwide Polyethersulfone Dialyzers Market — A 2026 Strategic Preview for Decision‑Makers
As healthcare systems re‑calibrate after pandemic era disruptions and reimbursement regimes adapt to new cost and outcome imperatives, polyethersulfone (PES) dialyzers remain a strategic linchpin for renal replacement therapy portfolios. PW Consulting’s new market intelligence shows a resilient growth profile for the PES dialyzer market: with the market valued at approximately USD 4.25 billion in the base year (2025) and a steady compound annual growth rate of 5.45% across the 2026–2032 forecast window, the sector is projected to exceed USD 6.1 billion by 2032. For executives building 2026 roadmaps, that trajectory matters — not only for topline planning, but for resource allocation across R&D, manufacturing, regulatory and commercial channels.
Textured Protein Ingredients Market
Why this report is essential for 2026 decision cycles
Actionable foresight for capital allocation: The growth profile and scenario variants in this study enable CFOs and corporate development teams to size investments in capacity expansion, outsourcing, or acquisitions with greater confidence.
Worldwide Green Fluorescent Protein (GFP) Assay Kits MarketRegulatory and reimbursement alignment: With tighter CMS rules, device classification dynamics and an active 510(k) environment, the report maps regulatory timelines to product launch and reimbursement windows so teams can avoid costly timing mismatches.
Worldwide Fiber Reinforced Plastic (FRP) Tanks MarketCommercial playbooks for shifting care settings: As care migrates across in‑center, home and hybrid pathways, the intelligence here supports differentiated go‑to‑market strategies and channel economics modeling.
M&A and partnership scouting: Market concentration insights and company profiles identify strategic targets, complementary capabilities and divestiture candidates aligned to near‑term scale and technological needs.
What the report delivers — practical, executable content
Robust market sizing and transparent methodology: Historical performance (2020–2025) and a detailed forecast hierarchy (2026–2032) with scenario splits that stress‑test volumes and average selling price dynamics under multiple reimbursement trajectories.
Buyer economics and unit economics templates: End‑to‑end cost of goods sold (COGS) models for PES dialyzers, enabling margin stress tests and break‑even calculations for new product variants or outsourced manufacturing strategies.
Regulatory roadmaps and approval timing matrices: A practical playbook for 510(k) submissions, biocompatibility testing and pivotal comparators — calibrated to observed clearance lead times and FDA expectations for high‑permeability systems.
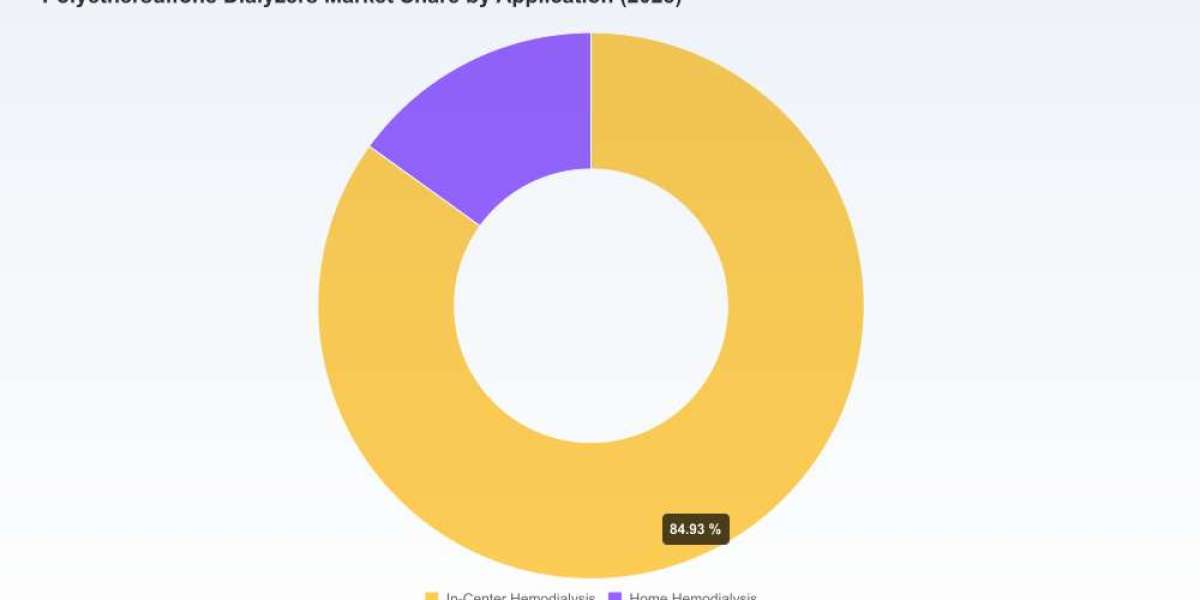
Commercial and channel frameworks: Segmented go‑to‑market strategies for in‑center and home settings, with distributor scorecards, pricing levers and patient uptake scenarios.
Priority investment and innovation roadmap: Technology archetypes (membrane chemistry, surface coatings, adsorptive layers), clinical value levers and R&D timelines tied to expected reimbursement inflection points.
M&A playbook and due‑diligence checklists: Rapid assessment templates for target valuation, manufacturing fit, IP strength and integration risk — designed for transactions that must close in 2026 to capture near‑term growth.
Competitive landscape — what the market structure tells strategic buyers
The PES dialyzer space shows material concentration among a handful of global players, with the top three firms representing a clear majority of market revenues and the top five firms commanding an even larger share. This structure creates a dual dynamic: sustained scale advantages for incumbents, and meaningful white‑space opportunities for agile challengers that can pair niche technological differentiation with flexible manufacturing footprints.
Fresenius Medical Care AG & Co. KGaA (Bad Homburg, Germany): A global leader with deep clinical trial linkages and strong hospital network relationships. Recent 510(k) clearances for new FX CorAL variants and multiFlux products reinforce Fresenius’s strategy of combining membrane advances with system‑level performance claims. Strategic implication: scale and clinical data make Fresenius a preferred partner for healthcare systems seeking integrated therapy solutions; competitors should anticipate rapid adoption cycles once system efficiencies are demonstrated.
Baxter International Inc. (Deerfield, Illinois, USA): A long‑standing supplier with broad acute and chronic dialysis footprints. Baxter’s product family and distribution strength position it well for contract wins in institutional settings. Strategic implication: Baxter is a likely counterparty in distribution partnerships and could be acquisitive around specialized membrane technologies that extend product differentiation.
Nipro Corporation (Osaka, Japan): A strong regional leader with an expanding global foothold. The March 2026 FDA 510(k) clearance for the ELISIO‑H high‑flux dialyzer illustrates Nipro’s investment in technical performance and regulatory execution. Strategic implication: Nipro is driving competitive pressure in high‑flux segments and is a credible cross‑border consolidation candidate.
Asahi Kasei Medical, B. Braun, Toray Medical and Nikkiso: Each brings distinct capabilities — from membrane chemistry and manufacturing scale to healthcare system relationships. These firms compete on incremental clinical performance and supply reliability; their strategic moves will likely focus on incremental innovation and selective regional expansion.
Lepu Medical (OCI), Dialife and regional players such as Farmasol: These manufacturers occupy fast‑growing regional niches and can be attractive partners for large firms seeking cost‑efficient supply chains or market entry in select geographies. Strategic implication: consider contract manufacturing or licensing arrangements to access local production cost advantages while preserving clinical branding for premium segments.
Regulatory and reimbursement dynamics — timing is a competitive advantage
Regulatory classification and reimbursement policy are primary determinants of product adoption velocity. PES dialyzers are regulated as Class II high‑permeability hemodialysis systems under 21 CFR 876.5860, requiring 510(k) clearance that demonstrates substantial equivalence on key performance metrics such as urea clearance and biocompatibility. Recent clearances (e.g., Fresenius’s FX CorAL 40/50 and multiFlux lines in late 2025–early 2026, and Nipro’s ELISIO‑H in March 2026) illustrate that firms with disciplined regulatory programs can accelerate market access.
On reimbursement, the Centers for Medicare & Medicaid Services finalized the CY 2026 ESRD PPS base rate at $281.71, reflecting modest market basket updates, and set the transitional add‑on offset for capital‑related home dialysis assets at $10.43 per treatment. Notably, no new transitional add‑on applications for dialyzers were approved in the recent cycle — a signal that direct reimbursement for device innovation remains constrained and that manufacturers must demonstrate clear clinical and economic value to influence payers.
Market concentration and strategic implications
With a concentrated top‑tier, market leaders will continue to leverage supply chain integration, scale manufacturing and adjacent service offerings to defend margins. For challengers and new entrants, the path to commercial viability in 2026 requires one or more of the following: (a) demonstrable clinical differentiation that shortens the payer‑approval cycle; (b) low‑cost manufacturing partnerships that preserve margin while enabling competitive pricing; or (c) targeted regional strategies that exploit gaps in incumbent distribution networks. Our competitive scorecards and supplier risk matrices in the full report quantify each firm’s strengths across these dimensions.
Five priority actions for 2026
Embed regulatory accelerators into R&D timelines: Structure development programs so that 510(k) readiness aligns with commercial launch windows and payer evidence requirements to avoid costly hold‑backs.
Pursue selective bolt‑on acquisitions or minority investments: Prioritize membrane or coating technologies that demonstrably improve clearance or biocompatibility and shorten time‑to‑clinical differentiation.
De‑risk supply chains through geographic diversification: Balance in‑house capacity with trusted contract manufacturers to manage unit cost volatility and geopolitical disruption risk.
Design home‑dialysis enablement packages: Combine dialyzer forms with patient support services and clinician education to accelerate home uptake where reimbursement incentives exist.
Build payer evidence packages early: Use real‑world evidence pilots and cost‑effectiveness models to secure favorable coverage conversations ahead of full launches.
What the full PW Consulting report includes (preview)
Interactive dashboards with historical and forecasted market values, growth scenarios and sensitivity analyses.
Segment‑level datasets and unit/price assumptions (available only in the full study) that support transaction diligence and budgeting.
Detailed competitor profiles, recent device clearances, patent landscapes and supplier scorecards prioritized for M&A screening.
Playbooks for regulatory submissions, reimbursement negotiation checklists and clinician adoption accelerators tailored to product archetypes.
Templates and KPIs for integration planning, manufacturing readiness assessments and commercial ramp metrics.
PW Consulting’s Worldwide Polyethersulfone Dialyzers Market report is designed to be a decision‑grade resource for boards, corporate development teams, product leaders and private equity sponsors evaluating strategies in 2026. Our “trailer” here highlights the strategic implications and actionable directions; the full study contains the granular segment outputs, scenario tables and executable templates that organizations will use to convert insight into measurable outcomes.
For executives ready to translate the market’s projected growth into concrete strategic moves, the full report and supporting data services are available via the PW Consulting report page. Accessing the full content will provide the segment‑level granularity, transaction comparables and operational checklists necessary to execute with conviction in 2026.
For detailed analysis of this topic, please visit the official page:Worldwide Polyethersulfone Dialyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com