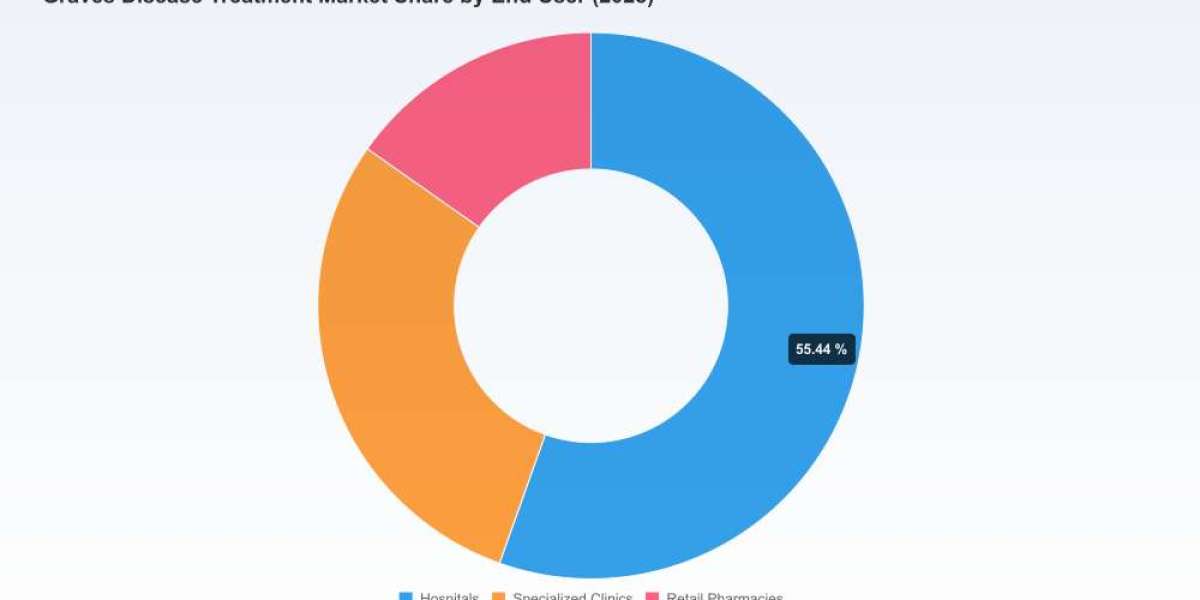

Worldwide Graves Disease Treatment Market — Strategic Briefing for 2026
PW Consulting’s latest market research report on the Worldwide Graves Disease Treatment Market offers a timely, high-resolution strategic compass for executive teams preparing decisions in 2026. Anchored on a 2025 base year and a forecast horizon through 2032, the study documents a clear expansion pathway: the market has grown from the low hundreds of millions in 2020 to an estimated USD 896.37 Million in 2025 and is projected to exceed USD 1.28 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.32% across the forecast period. These headline metrics frame a market that is large enough to attract multi‑strategy competition yet sufficiently fragmented to reward targeted clinical and commercial plays.
Worldwide 3D Vascular Ultrasound Imaging Market
Why this briefing matters to 2026 decision-makers
Timing: 2026 marks a transition from pandemic recovery dynamics to adoption-driven growth in specialty therapies and renewed pressure on generics supply chains. Your 2026 choices—whether capex, M&A, licensing, or go‑to‑market investments—will determine positioning for the next six years of steady expansion.
Cats Food Extrusion MarketValue capture: with single‑digit CAGR but robust absolute growth to 2032, the market favors high-margin biologics and optimized generic portfolios. Commercial, regulatory, and reimbursement strategies deployed in 2026 will disproportionately influence lifetime value realization for new and existing assets.
Filled Pasta MarketCompetitive posture: the market exhibits moderate concentration (CR3 ≈ 34.5%; CR5 ≈ 47.85%), indicating leading players control meaningful share but leave ample space for tactical entrants and differentiated offerings that address clinical unmet needs and payer pain points.
Practical, actionable content contained in the report
The PW Consulting report is built for immediate operational use by strategy, business development, and market access teams. It goes beyond descriptive market sizing to include empirically driven, executable modules such as:
Scenario-based market sizing and sensitivity models (base case, adoption-accelerated, and access-constrained scenarios) calibrated to 2020–2025 historicals and extending to 2032.
Clinical and commercial segmentation frameworks that identify where premium pricing, formulary inclusion, and specialist adoption converge to enable sustainable launches for novel therapies.
Reimbursement and pricing playbooks that map payer decision levers by therapeutic class and product archetype—critical for therapies with high per‑course costs.
Supply‑chain and manufacturing risk matrix, including scarcity scenarios for legacy small‑molecule antithyroid agents and mitigation roadmaps for raw material and contract manufacturing vulnerabilities.
M&A and partnership decision support: target-screening filters, synergies quantification templates, and integration risk checklists tailored to the Graves disease ecosystem.
Commercial launch sequencing and channel optimization blueprints, including hospital and specialist clinic engagement roadmaps and pharmacy distribution strategies.
Regulatory and HTA dossier templates with mapped evidence gaps and suggested post‑marketing study designs to accelerate reimbursement negotiations.
Competitive landscape: what incumbents and new entrants signal for 2026
Our analysis profiles a mix of large branded biologics developers and global generic manufacturers. The commercial dynamics are being reshaped by high‑value biologic treatments for ophthalmic complications alongside entrenched generics for hyperthyroid control. Key themes and implications include:
Biologics commercialization and portfolio integration: Amgen’s strategic acquisition activity has brought specialized treatments for thyroid eye disease into a global commercial engine. For companies contemplating late‑stage investments or licensing deals, Amgen’s moves illustrate the premium placed on integrated specialty care pathways and the value of complementary distribution and payer relationships.
Generic incumbency and consolidation pressure: established generic producers across North America, Europe, and Asia continue to underpin first‑line antithyroid therapy availability. Manufacturers with diversified regulatory footprints and resilient manufacturing networks will retain advantage as payers seek lower‑cost alternatives.
Opportunity for differentiated clinical assets: novel modalities addressing the ocular manifestations of Graves disease, as well as improved formulations or safety profiles for antithyroid agents, can command disproportionate clinical and commercial leverage—provided developers invest in targeted evidence generation and payer engagement early.
Regulatory, reimbursement and supply dynamics to watch in 2026
Reimbursement pressure for specialty therapies: high-cost courses for some targeted treatments create complex payer negotiations. For context, a full course of one recently commercialized ophthalmic biologic averages in the high hundreds of thousands of dollars, with traditional government payers covering a substantial portion under specific benefit structures. Manufacturers must prepare robust health‑economic packages and innovative contracting models (outcomes‑based, annuity, risk‑share) to secure access.
Safety and label constraints: legacy antithyroid agents carry clinically significant safety considerations that affect prescribing patterns and monitoring burdens. These regulatory realities influence product positioning, labelling strategies, and post‑market surveillance commitments.
Supply fragility in small‑molecule chains: episodic shortages of key active pharmaceutical ingredients or finished products have material commercial consequences. Firms should prioritize dual sourcing, strategic stockpiles, and transparent communication protocols with payers and providers.
Intellectual property cliff management: patent landscapes for high‑value biologics will shape competitive windows. Where exclusivity extends into the early 2030s, late entrants must plan for lifecycle strategies well before patent expiry.
How leading stakeholders should use the report in 2026
Pharmaceutical executives: use the report’s adoption curves and payer modeling to prioritize allocations between specialty biologics and generics, and to design pricing anchors that align with willingness‑to‑pay across major markets.
Business development teams: deploy the M&A playbooks and target filters to screen bolt‑on assets that accelerate specialist access or fill formulation gaps in the generics portfolio.
Market access and HEOR functions: adapt our HTA dossier templates and budget impact models to accelerate reimbursement negotiations for high-cost therapies and to structure innovative payment mechanisms.
Manufacturing and supply chain leaders: apply the risk‑matrix and scenario stress tests to quantify business continuity investments and prioritize capacity build‑outs that maximize resilience at acceptable cost.
Investors and private equity: leverage the report’s concentration metrics and scenario outputs to size potential returns under different consolidation and access outcomes.
Research integrity and the “trailer” approach
PW Consulting’s analysis balances transparency with commercial prudence. The public executive summary conveys the market’s trajectory and competitive dynamics, while the full report contains the detailed segmentation, regional and application-level breakdowns, and provider-level revenue models that institutional decision‑makers rely on. We intentionally withhold granular splits in this briefing to protect the proprietary value of the datasets and modeling techniques that support our recommendations.
Key strategic recommendations for 2026 (executive checklist)
Prioritize payer‑aligned evidence generation for any high‑price specialty asset entering 2026 market access discussions.
Strengthen manufacturing redundancy for legacy small molecules and secure secondary suppliers for critical inputs by Q4 2026.
Evaluate inorganic options to build specialty ophthalmology channels or to acquire capabilities that accelerate uptake among endocrinologists and ophthalmologists.
Design commercial pilots for outcomes‑based contracting in parallel markets to test payer receptivity and build case studies before full launch.
Use our scenario models to stress‑test portfolio valuations under differing adoption and reimbursement outcomes prior to committing to major capex or M&A deals.
Next steps to convert insight into advantage
For teams that need to convert this strategic context into executable plans, PW Consulting offers modular deployment: bespoke market models tailored to your asset, target‑level diligence for M&A, payer negotiation simulations, and on‑demand access to our specialists for road show and investor Q&A support. The full report includes the granular segmentation and financial tables that underpin the top‑line figures referenced here, together with downloadable spreadsheets and reproducible modelling assumptions.
To obtain the comprehensive dataset, proprietary segmentation, and the operational toolkits referred to in this briefing, visit our Worldwide Graves Disease Treatment Market report page or contact your PW Consulting representative. In an environment where clinical innovation, payer scrutiny, and supply resilience will determine winners, the right information in 2026 will separate merely reactive players from those that shape the market’s evolution.
For detailed analysis of this topic, please visit the official page:Worldwide Graves Disease Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com