
Worldwide 2‑Nitroaniline Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s new Worldwide 2‑Nitroaniline Market report provides C‑suite and strategy teams with a focused, decision‑grade perspective on a niche but strategically important chemical intermediate. Our analysis shows the market has expanded from approximately USD 245 million in 2020 to USD 313.4 million in 2025 and is projected to reach about USD 441.0 million by 2032, implying a compound annual growth rate (CAGR) of roughly 5.0% through the forecast horizon. This release is written as a strategic “preview”: it demonstrates the analytical depth and actionable frameworks you will find in the full report while directing procurement, commercial and M&A leaders to the primary source for the full data sets and proprietary subsegment tables.
Anti-Corrosion Glass Market
Why 2‑Nitroaniline matters as a 2026 strategic lever
Critical feedstock status: 2‑Nitroaniline is a core intermediate for dyes and pigments, pharmaceutical synthesis, corrosion inhibitor chemistries and agrochemical intermediates. Its role as a bridging material between basic aromatics and high‑value specialty products makes it a bellwether for shifts in downstream demand and pricing dynamics.
Worldwide Pancreatic and Bile Duct Stone Management MarketSupply chain sensitivity: production relies on classic nitration chemistry (nitration of aniline or protected acetanilide with mixed acids) and downstream separation of ortho isomers. These unit operations concentrate regulatory, safety and environmental risk factors that can produce sudden regional capacity adjustments.
Worldwide Overhead Monorail System MarketRisk of trade and regulatory shocks: the product’s hazardous classification, evolving environmental controls, and recent tariff policy updates affecting chemical intermediates are changing cross‑border economics and contracting approaches for 2026.
What the report delivers — practical, executable content
This is not a descriptive market brief. PW Consulting’s report is built for execution. Key deliverables include:
Validated market sizing and forecast model (2020–2032) with scenario pivots for demand shocks, feedstock price swings and regulatory tightening.
Supply‑side mapping and capacity ledger (facility by facility), including an operational scorecard that flags likely scale‑up or scale‑down candidates under the three most probable 2026 market scenarios.
Cost curve analysis and margin sensitivity for typical purity grades and product forms, allowing buyers to reverse‑engineer competitive pricing and suppliers to model EBITDA under variable feedstock and logistics costs.
Regulatory and HSE risk matrix that translates global classification and transport rules into practical procurement and contract clauses to reduce liability and insurance costs.
Supplier intelligence dossiers and a concentration analysis that support strategic sourcing, supplier diversification and M&A screening.
A near‑term playbook (12–18 months) for trading desks, procurement and M&A teams with prioritized actions, KPIs, and negotiation scripts tied to realistic market outcomes.
Segment dynamics you need to know (high‑level)
The market is commonly segmented by product grade, application and geography — each segment exhibits materially different demand drivers and risk profiles. High‑purity grades command different pricing and compliance requirements than standard technical grades; pharmaceutical family synthesis imposes stricter supplier qualification and traceability needs; pigment intermediates depend on textile and coatings cycles. Our report models these variances and synthesizes them into a consolidated demand forecast that remains usable at commodity trading desks as well as at corporate strategy tables.
Importantly, established production practice—nitration followed by ortho‑isomer separation—creates a manufacturing topology in which incremental capacity is rarely fungible across grades without investment. Historical production baselines (industry literature places worldwide output in the tens of thousands of tonnes per year) help explain why local shortages or regulatory closures can have outsized price impacts in specific end‑use channels.
Competitive landscape — who matters and why
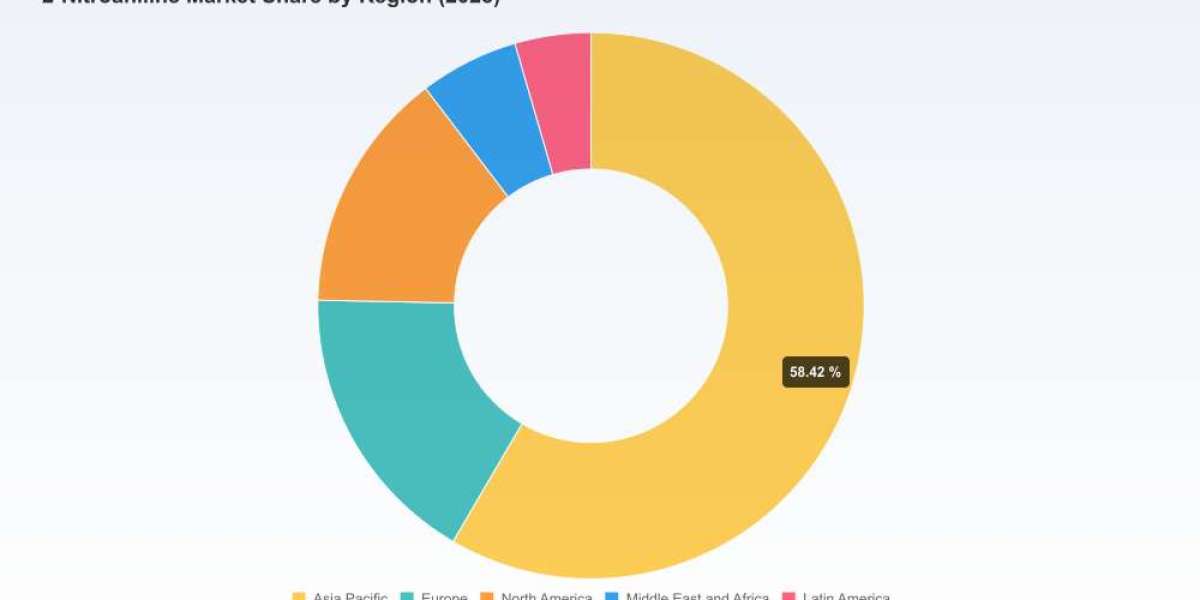
The global producer set combines large, ISO‑certified integrated manufacturers and specialized producers that target high‑purity applications. Market concentration is meaningful: the top three producers account for approximately 42% of market sales, and the top five reach close to 58%, creating a marketplace where a handful of players can influence pricing and availability.
Aarti Industries (India) — a strategic supplier of high‑purity 2‑Nitroaniline with explicit focus on pharmaceutical synthesis and CDMO channels. Their positioning gives them leverage where traceability and compliance command premium pricing.
Muby Chemicals / Mubychem Group (India) — an established specialty chemicals exporter with global distribution networks; often used as a flexible sourcing node for buyers seeking alternative contract terms.
Chinese manufacturers (representative examples include several established producers and ISO‑certified facilities) — these players collectively sustain a large portion of traded supply and are typically the swing capacity in response to global demand fluctuations.
Central Drug House (India) — an ISO‑certified supplier with a presence in both lab and industrial supply channels; useful as a qualified backup source for regulated customers.
Sinochem Nanjing — supplier with detailed safety and production disclosures, relevant to buyers increasingly requiring near‑real‑time HSE documentation.
Each supplier profile in the full report includes footprint, production technology notes, quality certifications, typical lead times, and an indicator of strategic intent (e.g., capacity expansion, focus on high‑margin pharma channels, export orientation). Those details are structured to support supplier segmentation and strategic sourcing decisions in 2026.
Regulatory, trade and HSE forces shaping 2026 outcomes
Three external forces will constrain strategic choices in 2026:
Regulatory compliance: 2‑Nitroaniline’s hazardous classification compels strict handling, storage and waste management protocols. Buyers should assume increasing inspection and permitting overhead in markets tightening environmental enforcement.
Trade policy: new tariff regimes rolled out in 2025 for broadly traded chemicals have altered landed cost equations. These changes increase the value of near‑sourcing and long‑term supply agreements that can lock favorable duty treatment or mitigate exchange‑rate exposure.
Logistics and insurance: hazardous product transport limitations and higher liability premia for international shipments raise the effective cost of distant sourcing; the report quantifies those delta‑costs under several routing and insurance assumptions.
Five strategic playbooks for 2026
Based on our scenario modeling and supplier scorecards, firms should prioritize the following actions:
Implement an upstream risk dashboard: combine supplier HSE scores, permit expiry timelines and regional inspection indices to generate a “near‑term disruption probability” and trigger contingency buys.
Revisit purity segmentation in contracts: separate commercial terms by grade band (high‑purity versus technical) to capture margin differentials and reduce cross‑grade substitution risk.
Secure logistics hedges: negotiate shared‑risk clauses and pooled insurance solutions for hazardous shipments to reduce single‑shipment exposure, especially for long‑lead imports subject to new tariff regimes.
Consider bolt‑on acquisitions or tolling agreements: target smaller, ISO‑certified producers with available capacity in strategic geographies to shorten lead times and improve quality control for regulated end‑uses.
Design a phased sourcing pivot: for organizations heavily exposed to a single region, model a two‑phase transition to diversified supply that balances cost, lead time and regulatory burden over 12–24 months.
How the full PW Consulting report helps you act in 2026
Readers of this preview should expect the full report to provide the built models, supplier dossiers, regulatory checklists and contract templates necessary to operationalize the strategies above. The proprietary forecast scenarios and the facility‑level supply ledger are intentionally retained for the full deliverable to protect the value of the modeling and to enable confidential briefings with clients making procurement, investment or M&A decisions.
For procurement heads, the report provides a prioritized sourcing roadmap and negotiation playbook. For corporate development teams, it provides an M&A scorecard and short‑list of opportunistic targets. For operations and EHS leaders, it supplies a compliance action matrix and contingency planning templates aligned to regional permit regimes and recent tariff changes.
Next steps
If your 2026 planning cycle includes raw material sourcing, capacity investment, or M&A activity in intermediates or specialty chemicals, PW Consulting’s Worldwide 2‑Nitroaniline Market report converts market complexity into executable decisions. Contact our research desk to schedule a demonstration of the models and supplier intelligence, or to arrange a confidential briefing tailored to your company’s exposure and objectives.
For detailed analysis of this topic, please visit the official page:Worldwide 2-Nitroaniline Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com