
Worldwide N-Acetylneuraminic Acid Market — Strategic Outlook for 2026 Decision-Makers
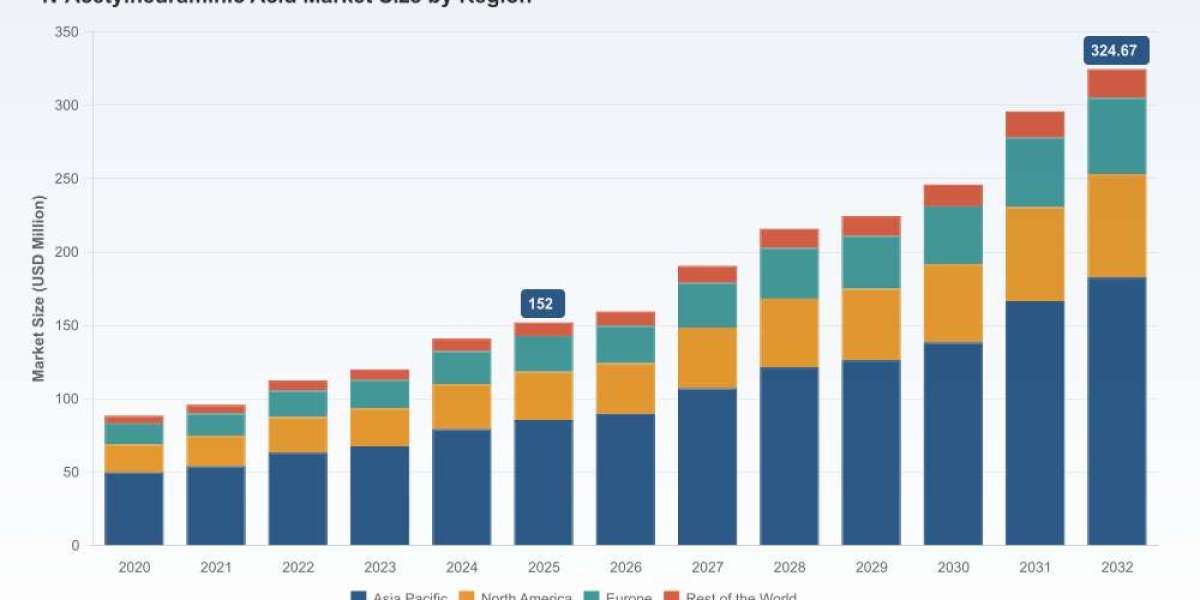
PW Consulting’s latest market study on Worldwide N-Acetylneuraminic Acid (Neu5Ac / NANA) is designed as a decision-ready intelligence package for executives planning actions in 2026. Built on a documented historical window (2020–2025, base year 2025) and a forward-looking forecast (2026–2032), the report combines a granular supplier assessment, practicable commercial playbooks, and scenario-tested demand models. At the macro level the market demonstrated steady expansion through 2025 (reaching USD 152.0 Million in 2025) and is projected to more than double by the end of the forecast, reaching roughly USD 324.67 Million by 2032 — a compound annual growth rate (CAGR) of 11.45% for the 2026–2032 period. This briefing highlights how the intelligence supports immediate 2026 decisions, while intentionally withholding detailed segment and regional line-item figures to preserve the value of the full report.
Worldwide Tool Holder Collets Market
Why this market matters for corporate strategy in 2026
N-Acetylneuraminic Acid has transitioned from a niche biochemical to a multi-channel specialty ingredient with commercial applications spanning infant nutrition, dietary supplements, cosmetics, and pharmaceutical intermediates. Several industry-level inflection points converge in 2026 that raise the strategic stakes:
Worldwide Commercial Switches Market
- Regulatory momentum: Recent approvals and standards activity — including national health authority recognition of Neu5Ac as a novel food production route and initiation of cosmetics-ingredient standard workstreams — reduce market-entry friction for food and personal-care applications and create regulatory windows for early adopters.
- Clinical catalysts: Regulatory milestones in therapeutic development (for example, clearance of an IND for a Neu5Ac prodrug program targeting GNE myopathy) underline an emerging clinical use-case that could materially affect demand segmentation and pricing dynamics if clinical programs advance as planned.
- Manufacturing evolution: Primary production remains fermentation-based using glucose or corn syrup feedstocks, with alternative bioprocesses (e.g., one-pot biosynthesis from chitin) advancing in the research-to-pilot corridor. These technical alternatives change the cost curve, sustainability profile, and supplier differentiation.
- Market structure: The market exhibits moderate concentration — the top three suppliers account for the majority of capacity, and the top five hold a substantially larger share. This structure creates both supplier power and acquisition opportunities for downstream buyers.
What PW Consulting’s report delivers (practical, deployable outputs)
The study is intentionally operational. It moves beyond descriptive narrative to supply the tools commercial teams need to act in 2026:
Worldwide Pediatric Oxygen Masks Market
- Market model and demand scenario suite — base case plus upside/downside scenarios calibrated to regulatory, clinical, and feedstock variables for 2026–2032.
- Price and cost curve estimates — historical price movement, raw-material pass-through sensitivity, and near-term price shock scenarios tied to glucose/corn syrup and energy inputs.
- Supplier scorecards — production capacity estimates, quality grading (food, pharmaceutical, cosmetic), certifications, geographic footprint, and supply continuity indicators suitable for vendor selection and dual-sourcing strategies.
- Regulatory matrix — jurisdictional requirements for food, cosmetic and pharmaceutical use, dossier mapping, and timelines for conformity with evolving standards (including China and key export markets).
- Go-to-market playbooks — segmented commercialization strategies for infant nutrition, supplements, cosmetics and pharma intermediate channels; recommended pricing strategies and packaging/quality KPIs for each channel.
- M&A and partnership shortlist — an annotated list of prospective targets and collaboration partners, screening for technical fit, certification status, and scale-up potential.
- Risk register and mitigation templates — supply-chain resilience plans, feedstock hedging approaches, and quality/recall playbooks for ingredient buyers and brand owners.
Competitive landscape — how to read the supplier map
Our competitor analysis synthesizes public records, supplier interviews, and third-party certifications to create comparative positioning for the leading participants. The market includes manufacturers that specialize in bulk commodity supply, high-purity lab reagents, and pharmaceutical-grade material — each category demands a distinct commercial approach.
- Fengchen Group (China) — Positioned as a volume supplier for chemical and material applications. Strengths: scale and established bulk-supply channels. Strategic implication: attractive partner for sourcing but requires careful quality and traceability audits for food-grade or pharma-grade applications.
- Xi’an Biof Bio-Technology Co., Ltd. (China) — Focused on higher-standard materials for nutraceuticals and functional ingredients. Strengths: product development aligned to supplement and food sectors, potentially faster responsiveness for custom formulations.
- Henan Steeda Industrial Co., Ltd. (China) — Bulk manufacturer serving dietary supplement and food additive markets; typically competes on cost and volume. Strategic implication: a candidate for cost-driven supply chains or toll-manufacturing partnerships.
- Xi’an SR Bio-Engineering Co., Ltd. (China) — Supplier of pharmaceutical-grade Neu5Ac with ISO certifications. Strengths: regulatory alignment and certification pedigree, suited for pharma-intermediate supply chains or contractual manufacturing for clinical programs.
- Biosynth (Switzerland) — Serves research and biochemical markets; recognized for quality and traceability. Strategic implication: preferred for R&D and early-phase clinical sourcing, less focused on high-volume food applications.
- TCI Chemicals (Japan) — Known for high-purity (>98% by HPLC) lab and industrial reagents. Strengths: analytical-grade products that underpin formulation and analytical development.
- Zhejiang Jianfeng Chemical Co., Ltd. (China) — Active producer integrated into established supply chains; typical profile of a regional mid-cap manufacturer with potential to scale for export markets.
Collectively, the top three suppliers capture a meaningful share of installed capacity, and the top five further consolidate supply — a structure that increases the value of early supplier qualification and long-term procurement contracts for buyers planning to scale in 2026.
Regulatory and technical inflection points to watch in 2026
- China’s regulatory posture: The National Health Commission’s acceptance of Neu5Ac production routes and the inclusion of the ingredient in cosmetics standard planning materially reduce near-term regulatory uncertainty for local manufacturers and exporters. However, the ingredient’s placement on certain administrative lists (e.g., terminated review lists for some new food raw materials) introduces specific compliance checkpoints buyers must clear.
- Clinical development: An IND clearance for a Neu5Ac prodrug paves a potential pathway from intermediate to active clinical demand. Even small shifts in clinical procurement can ripple through supply, especially where pharmaceutical-grade material is required.
- Manufacturing technology: The dominant route remains E. coli–based fermentation using glucose or corn syrup feedstocks, followed by multi-step purification and crystallization. Parallel advances — notably one-pot biosynthesis from chitin — promise alternative feedstocks and potentially improved sustainability metrics, but most alternatives are still in the pilot or early-scale phase.
- Feedstock risk: Because commercial production links closely to commodity sugars, capex and procurement strategies must incorporate raw-material price volatility and geographic concentration of feedstock supply.
Actionable recommendations for 2026
- Prioritize supplier qualification for pharmaceutical- and food-grade certification now — regulatory timelines and clinical programs mean qualified suppliers will be scarce as demand surfaces.
- Lock in forward pricing or establish index-linked contracts for key feedstocks to protect margins against sugar-price volatility.
- Explore co-development agreements with manufacturers advancing one-pot or alternative biosynthesis routes to secure preferential allocation and potential cost advantage.
- Develop a two-tier sourcing strategy: a certified, low-risk supplier for regulated channels and a cost-optimized supplier for non-regulated applications, with contingency capacity mapped for each.
- For CPG and ingredient companies: run accelerated stability and formulation pilots now using lab-grade material from suppliers with clear HPLC purity data to shorten time-to-market once regulatory windows open.
- For investors and corporate development teams: target acquisition or minority investments in ISO/regulated-grade producers to capture upside from clinical or cosmetics regulatory catalysts.
What this briefing intentionally omits — and how to obtain it
This release follows a “trailer” approach: it demonstrates the analytical depth and operational framing available in our full study while deliberately omitting line-item segmentation and granular regional or application revenue figures that drive procurement and M&A decisions. The full report includes:
- Segment-level forecasts and market shares by region and application (infant formula, dietary supplements, cosmetics, pharmaceutical intermediates).
- Supplier-specific capacity, price curves, and win/loss analyses with raw data tables.
- Detailed scenario outputs (sensitivity matrices tying regulatory and clinical outcomes to demand and price trajectories).
These datasets and proprietary models are available on the report landing page and via direct engagement with PW Consulting’s industry practice. For procurement teams, R&D leaders, business development and corporate strategy, securing the full dataset will materially accelerate sourcing decisions, formulation timelines, and M&A prioritization for 2026.
About PW Consulting
PW Consulting’s specialty chemicals and ingredients practice combines quantitative market modeling, primary supplier diligence, and regulatory intelligence to produce commercially actionable insight. Our N-Acetylneuraminic Acid study is the result of structured interviews, supplier audits, lab-grade specification reviews, and scenario-driven modelling — designed to convert market visibility into executable strategy for 2026. To request an executive summary, sample deliverables, or to schedule a briefing with the authors, visit our report page or contact our advisory team.
For detailed analysis of this topic, please visit the official page:Worldwide N-Acetylneuraminic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com