
Moulding Maize Starch Market: Strategic Imperatives for 2026 — PW Consulting Outlook
As food manufacturers and ingredient suppliers navigate the twin pressures of raw-material volatility and tightening regulatory scrutiny, moulding maize starch has re-emerged as a strategically significant input across confectionery and specialized industrial applications. PW Consulting’s latest market study — with a 2025 base year and a 2026–2032 forecast window — identifies clear growth trajectories and decision levers that corporate leaders must act on in 2026 to secure competitive advantage.
Worldwide Binding Resins for Oriented Strand Board (OSB) Market
Headline Market Signals
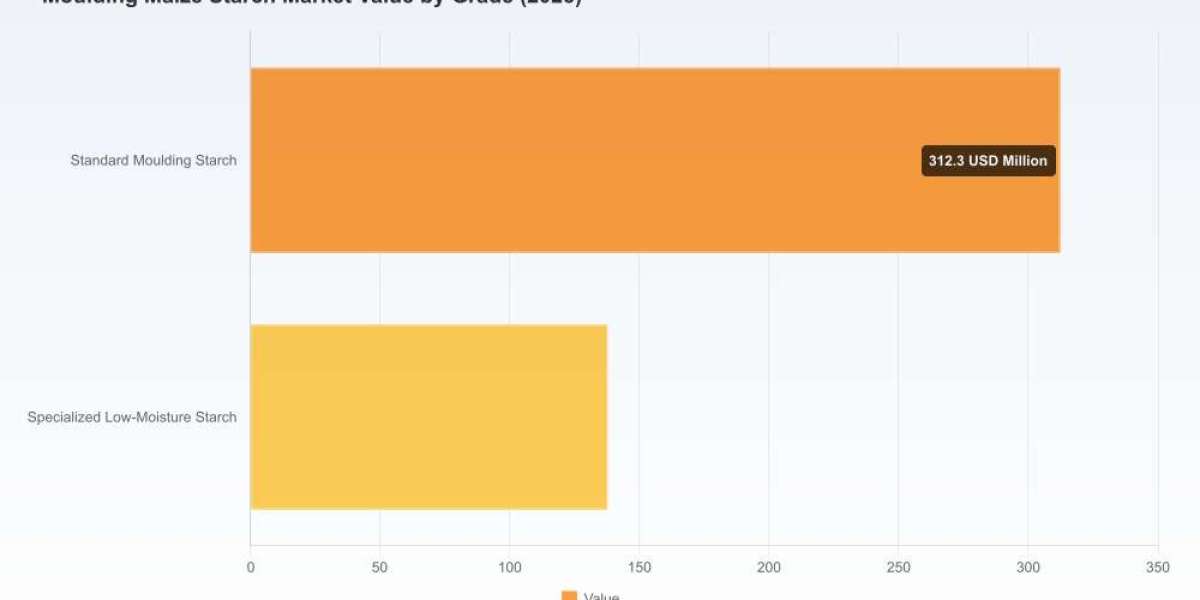
Our analysis places the global moulding maize starch market at approximately USD 450 million in 2025, with an expected compound annual growth rate of 4.85% through 2032. At this pace, the market advances materially by the end of the forecast period, reflecting resilient demand from confectionery moulding processes and selective industrial uses that favor tailored starch grades.
2-in-1 Micro Inverter Market
Concentration metrics indicate a moderately consolidated supplier landscape: the three largest players account for roughly 45–46% of market sales, while the top five reach north of two-thirds of the market. This structure continues to shape pricing dynamics, innovation diffusion, and access to scale advantages for customers and suppliers alike.
Ski Scooter Market
Why 2026 Is a Pivotal Year for Decision-Makers
Raw-material and cost pass-through realities: Producer price indices and feedstock movements in late 2025 and early 2026 have re-priced starch economics — a trend that will test contract models, hedging approaches and vertically integrated margins in 2026.
Regulatory inflection points: Policy reviews around organic availability and GMO thresholds are altering procurement options for food-grade starch. These regulatory dynamics are not uniformly distributed by market, creating tactical windows for suppliers who can certify or retool quickly.
Supply-side repositioning: Portfolio realignments, capacity expansions and targeted product launches among industry incumbents are reshaping competitive spacing and route-to-market strategies.
What the Report Delivers — Practical, Actionable Intelligence
PW Consulting’s report goes well beyond topline figures to equip boards, commercial leaders and supply-chain executives with executable insights, including:
Decision frameworks for procurement and contracting: Playbooks for term versus spot sourcing, pass-through clauses, and index-linked pricing that align with starch production cycles and confectionery production calendars.
CapEx and capacity planning templates: A phased model to evaluate greenfield versus brownfield investments, return thresholds under different feedstock price scenarios, and sensitivity to process yields and co-product economics.
Product and portfolio strategies: A segmentation roadmap for positioning standard moulding starches versus specialized low-moisture or functional-modified grades, with go-to-market implications for branding, formulation support and co-development with key customers.
Regulatory and certification playbook: Action steps to anticipate organic program changes and GMO labeling impacts — including audit checklists, certification timelines and cross-border compliance matrices.
Commercial tactics for margin management: Pricing levers, margin-protection strategies and route-to-market combinations (direct sales, distributors, co-manufacturing partnerships) tailored to different customer segments.
Risk scenarios and mitigation measures: Stress-tested scenarios for feedstock shocks, logistics disruption, and abrupt regulatory shifts — with contingency plans and early-warning indicators to embed in management dashboards.
Competitive Landscape: What Leading Suppliers Are Doing
The market is shaped by a group of well-capitalized, capable suppliers that span global agribusiness integrators and specialized starch manufacturers. PW Consulting’s study synthesizes company-level moves and strategic intent to clarify where differentiation is emerging:
Cargill Incorporated — Continuing to commercialize oil-blended and modified dent-corn offerings tuned for clean release and moisture management in confectionery moulds. Recent product introductions underscore a push on formulation-led differentiation and customer support at trade events.
Archer Daniels Midland (ADM) — Capacity additions completed in 2025 signal a focus on throughput flexibility and supply assurance for confectionery customers. ADM’s product suite emphasizes non-GMO options and process-friendly flow characteristics.
Tate & Lyle — Leveraging its moulding starch range to address drying and stoving challenges in jelly-type products, with a commercial focus on reducing dusting and improving downstream handling.
Ingredion — Active in specialty starch grades and, in early 2026, executed a portfolio realignment to rationalize ownership in certain maize starch operations while retaining strategic minority stakes — a move that signals selective consolidation and capital redeployment.
Roquette, AGRANA, Tereos and Emsland Group — Each supplier is pursuing a mix of regional footprint optimization, organic or sustainability-oriented credentials, and product variants suited for mogul systems and other confectionery manufacturing technologies.
The net effect: competition is shifting from purely price-driven to a hybrid of reliability, formulation support and regulatory alignment. Suppliers that can bundle certification, technical service and flexible supply will increasingly capture higher-margin business.
Industry Context and Emerging Risks
Input-price volatility: The Producer Price Index for wet corn milling and starch manufacturing rose meaningfully into early 2026, underscoring the need for dynamic procurement and tighter margin monitoring across the value chain.
Regulation and labeling: Active reviews of organic listings and persistent GMO regulatory regimes in some major markets create asymmetries in available product sets. Manufacturers should anticipate procurement constraints and build multi-jurisdictional compliance into product launch timelines.
Feedstock risk concentration: Price swings and regional production limits continue to advantage vertically integrated players with raw-material flexibility and co-product hedges.
Strategic Imperatives for 2026 — A Roadmap
Based on our scenario analysis and company-level intelligence, PW Consulting recommends executives pursue a balanced set of actions in 2026 to convert market signals into advantage:
Lock in tiered supply arrangements: Layer long-term agreements for core volumes with indexed short-term purchases to exploit periodic dislocations. Include explicit clauses for force majeure, certification changes and pass-through of additive inputs.
Prioritize certification and segmentation options: For confectionery brands targeting organic or clean-label positioning, prioritize supplier partners with track records in organic molding starch or who can provide transition timelines under regulatory change.
Invest in formulation and processing R&D: Small gains in release, moisture control and dust suppression translate to downstream yield and quality improvements. Co-development agreements can accelerate adoption while spreading development cost.
Use concentration insights to inform M&A and partnership strategy: With the top-five suppliers capturing the majority of market share, selective acquisitions or strategic alliances can be an efficient route for regional entrants or ingredient distributors to scale quickly.
Hedge operationally against feedstock swings: Vertical integration, tolling agreements and flexible co-product monetization reduce exposure. Financial hedges should be complemented by operational levers such as inventory buffers and alternate-sourcing clauses.
Embed regulatory surveillance into product roadmaps: Anticipatory compliance and certification timelines should be treated as gating milestones in any new-product or market-entry plan.
Where PW Consulting Adds Value
Our report is deliberately structured as an execution companion: it pairs macro forecasting (market size trajectory and CAGR through 2032) with modular tools — supplier scorecards, procurement playbooks, scenario-modelled capex matrices and regulatory action plans. We reveal the causal mechanisms behind price moves and supplier behavior, while preserving detailed segment-level spreadsheets and proprietary supplier scoring behind paywalled data to support transaction-grade decisions.
For executives preparing budgets and strategic briefs in 2026, the report offers:
Concrete sensitivity analyses for revenue and margin under alternative feedstock and demand scenarios
Template contracts and checklist language to de-risk sourcing of certified or specialty starches
Due-diligence frameworks for potential M&A targets, with playbooks for integrating production assets or supplier relationships
Next Steps and How to Access the Full Intelligence
PW Consulting’s executive summary provides a strategic snapshot suitable for board-level discussions. However, the granular segmentation, regional and application-level dynamics — including customer-by-application demand patterns and supplier-by-region exposures — are reserved for the complete market datasheet and model pack available from PW Consulting.
If your 2026 planning cycle requires transaction-ready analysis, supplier negotiation support or a tailored deep-dive into a sub-segment (for example, specialty low-moisture grades or organic moulding starch go-to-market plans), PW Consulting can deliver customized workshops, scenario modelling and supplier diligence packages.
Conclusion
The moulding maize starch market in 2026 sits at the intersection of steady demand growth, concentrated supplier power and heightened regulatory complexity. Companies that align procurement discipline with formulation innovation and regulatory foresight will translate the market’s modest but durable expansion into differentiated returns. PW Consulting’s report equips leaders with the frameworks and tools to make those decisions with confidence — detailed segment-level data and supplier models are available through our full report for organizations seeking to operationalize these insights.
Contact PW Consulting to arrange access to the complete market model, supplier scorecards, and tailored advisory support for your 2026 strategic planning process.
For detailed analysis of this topic, please visit the official page:Moulding Maize Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com