
Worldwide Gallium Arsenide (GaAs) Devices Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
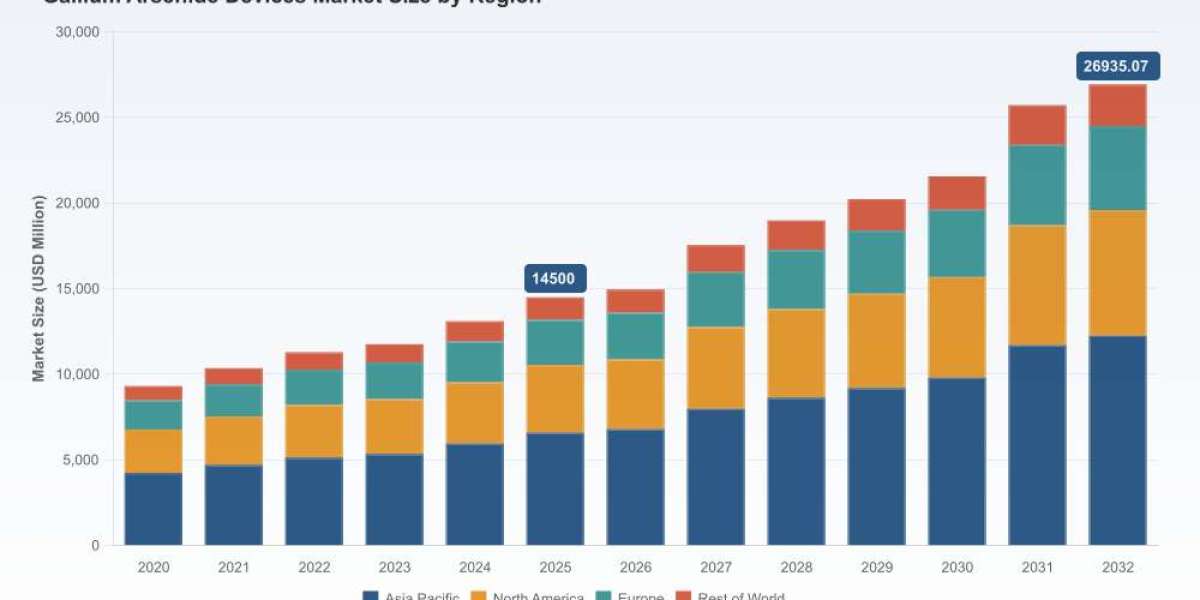
PW Consulting’s latest market intelligence — the Worldwide Gallium Arsenide Devices Market report (base year 2025, historical 2020–2025, forecast 2026–2032) — surfaces the fast‑moving dynamics that will determine winners and losers in the GaAs ecosystem over the next investment cycle. Our analysis confirms a robust industry trajectory: the GaAs devices market exceeded USD 14.5 billion in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of approximately 9.25% through 2032, reaching roughly USD 27 billion by the end of the forecast horizon. This growth is being driven by persistent demand for high‑frequency RF components in wireless infrastructure and mobile devices, alongside accelerating use cases in optical interconnects, defense radars, and select automotive applications.
Tablet Note App Market
Why this matters for corporate strategy in 2026
Macro momentum with asymmetric risk: Healthy top‑line growth masks concentrated supply‑side vulnerabilities. Market expansion creates revenue and scale opportunities, but concentrated raw material sources and regulatory shifts can create episodic supply shocks and cost volatility.
Worldwide Encryptor MarketCapital allocation inflection: The 2026 planning window is pivotal — firms must decide where to invest in capacity, vertical integration, and secure sources of epitaxial material versus opportunistic M&A to accelerate technology access.
Worldwide Semi- Balanced Ship Rudder MarketCustomer value re‑engineering: For OEMs and module suppliers, optimizing GaAs bill‑of‑materials and supplier strategies will increasingly determine competitiveness for 5G/6G infrastructure, emerging mmWave consumer devices, and datacenter optics.
Market trajectory and the numbers you can act on
Over the historical 2020–2025 period PW Consulting traced sustained market growth that culminated in a 2025 market size of approximately USD 14.5 billion. Our baseline projection models — calibrated to device lifecycle dynamics, OEM capex plans, and supply‑chain constraints — point to a continued compound annual growth rate near 9.25% across 2026–2032. That trajectory implies the market will roughly double over the coming seven years, delivering expanding addressable revenue pools but also intensifying competition for critical raw inputs and epitaxial capacity.
Importantly, market concentration remains material: the top three vendors account for a majority share of the industry, and the top five approach three‑quarters of the market. For executives, this concentration creates strategic tradeoffs between competing on scale versus specialization — and underscores the potential impact of single‑player moves (capacity additions, long‑term supply contracts, or technology leaps) on industry economics.
Competitive landscape — who matters and why
The GaAs value chain spans substrate and epi suppliers, foundries, device makers, and module integrators. Our report profiles and benchmarks the key players shaping the market:
AXT Inc. (Fremont, CA) — a substrate and wafer supplier, visible through quarterly production and revenue disclosures indicating steady commercial activity in high‑performance wafer substrates.
IQE PLC (Cardiff, UK) — a leading epitaxial wafer supplier with multi‑year supply agreements that tie directly into smartphone power amplifier supply chains and Tier‑One OEM ramps.
WIN Semiconductors (Taoyuan, Taiwan) — a GaAs foundry and device maker focused on RF/microwave devices for mobile and infrastructure, increasingly emphasizing secure logistics and material stewardship through strategic partnerships.
Qorvo and Skyworks (US) — design and manufacturing leaders for GaAs‑based RF front ends, serving both mobile OEMs and defense markets; their product roadmaps are pivotal to mmWave adoption curves.
Sumitomo Electric and DOWA — established materials and wafer producers that are strategically positioning capacity toward data center optics and AI interconnect opportunities.
Freiberger, Xiamen Powerway, Coherent (formerly II‑VI), MACOM, and regional specialists — collectively support geographic diversification and specialist supply for photonics, optoelectronics, and defense applications.
Each of these players brings distinct strengths — from substrate purity and epi capability to foundry scale and systems integration. The interplay of capability, location, and long‑term customer contracts (e.g., multi‑year wafer supply agreements) is a primary determinant of supplier resilience and bargaining power.
Recent industry developments that will shape 2026 decisions
Strategic contracts sharpen competitive moats: Notable multi‑year supply agreements between epitaxy suppliers and smartphone power amplifier manufacturers have already begun to reconfigure supplier roadmaps and OEM procurement strategies.
Targeted capacity expansions: Announced investments to increase wafer and epi capacity for datacenter optics and AI server interconnects signal a structural demand shift beyond traditional wireless markets.
Operational security and logistics: Partnerships focused on long‑term secure storage of wafers, dies, and mask sets indicate a rising premium on intellectual property protection and continuity of supply.
Public financial confirmations: Quarterly and full‑year results from substrate manufacturers corroborate continued commercial traction across diversified end markets.
Supply‑chain and regulatory risk — the hidden accelerants
Two interlinked themes dominate supply‑risk analysis:
Raw material concentration — Gallium production is geographically concentrated. This concentration translates into systemic exposure when major producing jurisdictions impose export restrictions, license regimes, or bans. Policy decisions affecting gallium flow have material implications for lead times, cost pass‑through, and inventory strategies.
Regulatory interventions and industrial policy — Governments are actively shaping the compound semiconductor landscape. Subsidy programs and CHIPS‑style funding mechanisms are directing capital to expand domestic GaAs and compound semiconductor fabrication in specific markets, altering the economics of capex and localization decisions.
For procurement and risk teams, the practical takeaway is clear: visibility into material provenance, dual‑sourcing plans for epitaxial wafers, and scenario playbooks for export‑control events are no longer optional. They are central to maintaining shipment continuity and preserving customer trust.
What the report delivers — operational, not just informational
PW Consulting’s report is expressly built to be actionable for 2026 planning cycles. Key deliverables include:
Forward‑looking revenue and volume forecasts at the total‑market level (2026–2032), including sensitivity runs tied to adoption scenarios for wireless infrastructure, datacenter optics, and defense procurement.
Supplier and raw‑material risk matrices mapping concentration, likely chokepoints, and mitigation levers (contractual, inventory, geographic diversification) that procurement teams can operationalize.
Capex decision frameworks and payback models for wafer/epi capacity investments, with tiered scenarios for greenfield builds, expansions, and strategic partnerships.
M&A and JV scoring templates tailored to GaAs technology, enabling acquirers to prioritize targets by technology fit, customer access, and supply resilience.
Commercial playbooks for OEMs and module suppliers that translate device‑level trends into BOM optimization, supplier negotiation levers, and product roadmaps.
We intentionally present a high level of methodological transparency in the report: inputs, assumptions, and model sensitivity are documented so corporate planning teams can re‑run scenarios using their own constraints.
How to use this intelligence in your 2026 planning
Procurement leaders — use the report’s supplier maps and risk matrices to implement tiered sourcing strategies, negotiate longer‑term epitaxy contracts, and justify strategic inventory buffers to mitigate regulatory disruption.
Corporate development teams — apply the M&A scoring templates to shortlist bolt‑on targets that offer immediate supply‑chain resilience or unique IP for high‑value use cases (mmWave, VCSELs, datacenter optics).
R&D and product strategy — align device roadmaps with the forecasted demand curves and sensitivity scenarios, prioritizing product families that achieve differentiated performance while reducing dependency on scarce inputs.
Policy and government affairs — leverage the report’s regulatory impact models to quantify the business case for public‑private collaboration and to design practical compliance playbooks for export‑control regimes and duty classifications.
Trailer: what we’re intentionally withholding (and why)
To preserve the commercial value of the full report for subscribers and enterprise clients, this briefing deliberately omits granular regional and application split figures, and specific vendor revenue breakdowns beyond high‑level profiles. The full report contains detailed segmentations, regional demand curves, device‑level forecasts, and proprietary vendor benchmarking that materially inform procurement sizing, capacity decisions, and M&A valuations. Accessing the complete dataset and Excel model is recommended for teams making binding capital allocation or contractual commitments in 2026.
Conclusion — decisions to take now
2026 is not a passive planning year. Firms that move early to secure diversified epitaxy supply, align capex with credible adoption scenarios for both wireless and optical markets, and invest in supplier partnerships or targeted acquisitions will be best positioned to capture disproportionate value as the GaAs market scales. PW Consulting’s report is designed to convert market insight into executable plans: from procurement playbooks and capex models to M&A prioritization and regulatory contingency planning.
For executives preparing budget cycles, negotiating supplier commitments, or assessing strategic transactions in 2026, the report provides the high‑fidelity analytics, scenario templates, and playbooks necessary to make defensible, high‑impact choices. To access the full intelligence and the downloadable model that underpins our forecasts and recommendations, please consult the PW Consulting report landing page for subscriber access and enterprise licensing options.
For detailed analysis of this topic, please visit the official page:Worldwide Gallium Arsenide Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com