
Automated Marine Debris Collection Equipment Market: Strategic Insights for 2026 Decision-Making
PW Consulting’s latest market research, Automated Marine Debris Collection Equipment Market — 2026 Strategic Brief, synthesizes five years of historical data and a seven-year forecast to equip executives with the evidence and frameworks required to make high-confidence decisions in 2026. The study combines rigorous market-sizing, competitive benchmarking, deployment economics, and regulatory mapping to translate a fast-growing, mission-driven industry into actionable corporate strategy.
Wheel Range Finder Market
Executive snapshot: Why this market matters in 2026
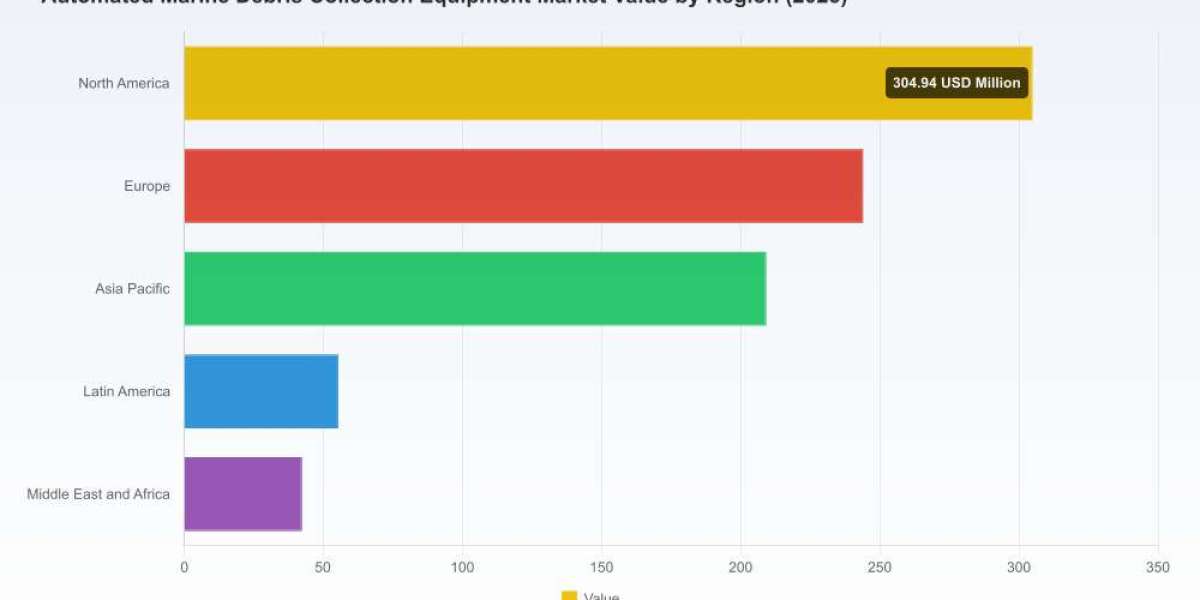
Growth momentum — The automated marine debris equipment market has roughly doubled in scale over the last half-decade, reaching an estimated USD 856 million (Million USD unit) in 2025, and is projected to continue expanding at a compound annual growth rate (CAGR) of approximately 12.45% through the 2026–2032 forecast horizon.
Industrial Inline Process Viscometer MarketMarket structure — Concentration is moderate: the top three players account for a meaningful minority of revenue while the top five extend that share substantially (CR3 ≈ 38.5%; CR5 ≈ 52.7%), leaving clear room for new entrants, niche specialists, and strategic consolidations.
Disposable Fermentation Tank MarketPolicy and funding alignment — Recent progress in high-level plastics governance and stepped-up public-sector financing have converted environmental urgency into procurement pipelines and public-private partnership opportunities.
What makes 2026 an inflection year?
Regulatory catalyzers: Negotiations and implementation activity around global plastics governance — including mandates that emphasize collection targets and extended producer responsibility — have sharpened procurement timetables for municipal and national buyers. This creates near-term windows for vendors who can demonstrate verifiable collection outcomes and circular-material value chains.
Capital flows and pilot-to-scale pathways: Multilateral development banks and bilateral funds are transitioning from grants supporting pilots to outcome-based financing for scalable deployments, encouraging vendors to present robust total-cost-of-ownership (TCO) models and performance guarantees.
Technology maturation: Autonomous navigation, onboard AI sorting, and modular collection systems are moving from pilot projects to sustained operations — enabling more predictable operational metrics (uptime, collection per mission, maintenance cadence) that procurement teams can use as contracting KPIs.
Circular inputs: Innovative reuse of recovered plastics as feedstock for equipment components is creating both cost and reputational advantages for operators who close the loop between collection and manufacture.
Competitive landscape: who’s shaping the market and how
The market is populated by a mix of mission-driven scale players, specialized robotics vendors, and established marine-equipment suppliers. Our analysis profiles operating models, technology architectures, commercial approaches, and recent milestones for the core players shaping 2026 activity:
The Ocean Cleanup (Rotterdam, Netherlands): Known for large-scale river Interceptors and ocean barrier systems. Recent milestones include a multi-million-kilogram cumulative removal achievement and the global expansion of its urban river deployment program — moves that underscore a strategy focused on scale, infrastructure partnerships, and programmatic city-level engagements. (https://theoceancleanup.com/)
RanMarine Technology (Rotterdam, Netherlands): Markets autonomous surface vessels (WasteShark series) tailored for ports, marinas and urban waterways. Their value proposition centers on repeatable, compact fleets that can be integrated with facility-level maintenance contracts.
Seabin Project (Mullumbimby, Australia): Offers floating collection units optimized for marinas and calm waters; their solution model emphasizes low upfront cost and local operator deployment, targeting community-led and commercial waterfront applications.
Clear Robotics / Clearbot (Hong Kong): Develops AI-driven autonomous electric boats with a focus on river cleanup pilots and municipal deployments. Recent pilot expansions in partnership with regional development banks signal growing acceptance of autonomy-integrated operational models.
Elastec (Carmi, Illinois, USA): A longer-standing provider of booms, skimmers and custom skimming vessels, Elastec brings legacy marine engineering competence and a catalog-based procurement channel attractive to traditional waterway operators.
Collectively, these players illustrate several strategic archetypes in the market: platform-scale integrators, autonomous fleet specialists, niche unit providers, and traditional marine-equipment firms. Each archetype presents distinct partnership, procurement, and M&A implications for buyers and investors.
What the PW Consulting report includes — practical and deployable content
Beyond topline metrics, the report is constructed as a decision-support toolkit. We deliberately focused on operational utility and procurement relevancy rather than only descriptive analysis. Key deliverables inside the full study include:
Proprietary market-sizing model and scenario engine: Interactive frameworks that allow buyers to stress-test demand, unit economics and payback timelines across riverine, coastal and port deployment settings.
Vendor scorecards and supplier shortlists: Qualitative and quantitative benchmarks across technology maturity, service model, scalability, and post-sale support — enabling rapid longlisting and focused RFP design.
TCO and procurement templates: Standardized templates to evaluate CAPEX vs. OPEX trade-offs, maintenance cycles, spare-parts logistics, and financing structures (capex lease, performance payments, blended finance).
Operational playbooks and KPIs: Field-tested operating procedures for fleet scheduling, fleet-to-infrastructure integration, data capture for impact reporting, and contractor oversight.
Regulatory and funding map: A jurisdictional synthesis that aligns policy levers, grants, and procurement windows to practical rollout timelines — plus guidance for aligning vendor proposals with extended producer responsibility schemes.
M&A and partnership locator: A short-list of strategic targets and partnership types tailored to acquirers seeking rapid capability expansion or geographic entry, accompanied by valuation multipliers and risk checklists.
Case studies and pilot evaluations: Deeper dives into representative projects — from urban river pilots to harbor-scale fleet deployments — with anonymized performance data, lessons learned and decision-gate milestones.
Strategic recommendations for executives in 2026
Adopt a “pilot-to-scale” procurement approach: Structure early contracts to capture performance data while explicitly preserving scale-up rights and pricing resets. Governments and donors are increasingly comfortable with staged financing linked to agreed KPIs.
Prioritize interoperability and modularity: Select systems that can be upgraded in-situ (sensor suites, sorting modules, autonomy stacks) to hedge against rapid technological obsolescence and to facilitate component-level recycling.
Embed circularity as a commercial differentiator: Preference for equipment or suppliers that demonstrate recycled-material use for components, and that can trace recovered plastics into secondary markets will command procurement preference and potential EPR credits.
Design for service economics: Buyers should shift evaluation from unit price to full-life service economics — uptime, mean-time-to-repair, spare-parts availability, and data transparency are the variables that determine long-term value.
Forge multisector partnerships: Combine technical vendors with local operators, civil-society monitoring groups, and financing partners to reduce implementation risk and to strengthen outcome validation for funders.
How to use this report in your 2026 planning cycle
Procurement leads, corporate sustainability officers, and investment committees can use the report as a practical playbook for three immediate actions:
Shortlist technologies and vendors against an organization’s operational constraints using our vendor scorecards and procurement templates.
Build scenario-based budgets using the report’s TCO modules and sensitivity analyses to set realistic production and financing targets for the next 18–36 months.
Inform partnership and M&A strategies by mapping competence gaps to the market’s strategic archetypes and concentration metrics, identifying where to buy versus build.
Why PW Consulting’s approach matters
Clients tell us they need more than trend summaries — they need deployment-level clarity that aligns with procurement windows, donor timelines, and commercial capex cycles. PW Consulting’s automated marine debris market study marries rigorous macroforecasting with playbooks and procurement instruments that decision-makers can apply immediately. We intentionally present headline metrics and strategic direction in public communications while reserving granular segment matrices, region/application splits and vendor unit economics for the full study — ensuring stakeholders have the precise data they need to act without diluting the commercial intelligence provided to subscribing clients.
Next steps and access
For executives preparing capital plans, seeking technology partners, or assessing acquisition targets, PW Consulting’s full report provides the empirical backbone for 2026 decisions. The comprehensive dataset includes our proprietary forecasts, scenario engines, supplier benchmarking, and templated contract language designed for rapid operationalization.
To obtain the full study, proprietary appendices, and an invitation-only briefing with our senior analysts, visit PW Consulting’s reports page or contact our advisory desk. Our analysts are available for tailored workshops to translate the report’s strategic recommendations into a three-to-nine month implementation roadmap.
PW Consulting — translating market momentum into executable strategy.
For detailed analysis of this topic, please visit the official page:Automated Marine Debris Collection Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com