
Worldwide Child Rehabilitation Market — Strategic Imperatives for 2026
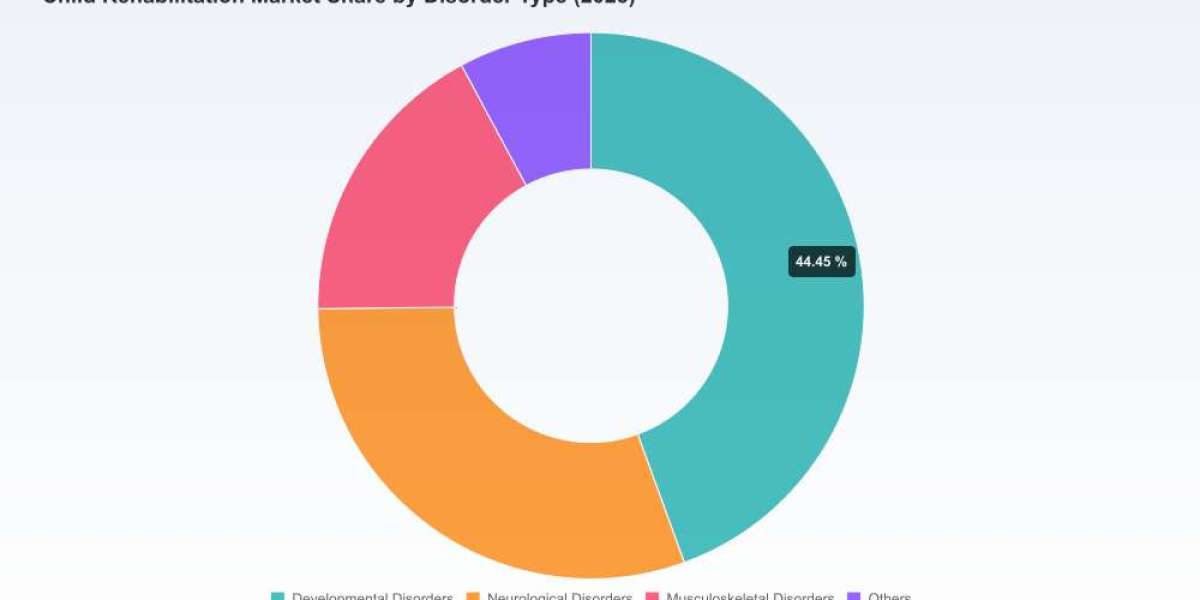
PW Consulting’s new Worldwide Child Rehabilitation Market report delivers a data-driven, actionable intelligence package designed to inform executive decisions in 2026. Anchored on a detailed historical view (2020–2025) and a rigorous forecast run (2026–2032), the study finds the global market expanding from roughly USD 8.8 billion in 2020 to an estimated USD 12.5 billion in 2025, and projects continued acceleration to approximately USD 20.3 billion by 2032 at a compound annual growth rate (CAGR) of 7.21%. This trajectory reflects persistent demand for paediatric-focused therapy services, technology-enabled care models, and specialized clinical capacity — all under new operational and regulatory constraints that will define winning strategies next year.
Digital Clam Heat Press Market
Why this report matters for 2026 decision cycles
Investment allocation — Our forecast and scenario analysis translate growth vectors into investment priorities. Companies contemplating greenfield units, acquisitions, or technology adoption will find a calibrated view of near-term payback windows and medium-term scale opportunities that align with a 2026 planning horizon.
Worldwide Underwater Expendables MarketM&A and partnership playbooks — With market concentration remaining low (CR3 ~14.9% and CR5 ~21.3%), opportunities for value-creating consolidation coexist with local, high-margin specialty plays. The report maps target profiles, integration risks, and partnership archetypes suited to capture scale without eroding clinical differentiation.
Automotive Fiber-reinforced Polymer Composites MarketOperational resilience — Labour scarcity and rising specialist compensation are already reshaping care models; our operational dashboards quantify the impact of workforce inflation (e.g., average US pediatric physical therapist salaries) on unit economics and prescribe staffing mixes, telehealth leverage, and contract labor strategies to protect margins in 2026.
Regulatory and reimbursement navigation — Detailed guidance synthesises Joint Commission requirements for children’s facilities, CMS outpatient therapy reimbursement dynamics, and child-privacy telehealth constraints, enabling finance and compliance teams to forecast reimbursement risk and design compliant service bundles.
Practical, executable content inside the report
Proprietary market model: full historical dataset (2020–2025) and a deterministic/Monte Carlo hybrid forecast for 2026–2032, permitting stress-testing under alternative demand and reimbursement scenarios.
Tactical playbooks: go-to-market decision trees for outpatient vs. inpatient expansion, school-district integration, and hybrid tele-rehabilitation programs; each playbook includes staffing templates, capital intensity estimates, and 12–36 month KPI roadmaps.
Reimbursement & regulatory compendium: mapped payer rules, therapy cap impacts, and a compliance checklist for Joint Commission and pediatric telehealth (including parental consent workflows and data governance for minors).
Technology adoption matrix: ROI-calibrated guidance on robotics (gait trainers, exoskeletons), motion analysis systems, remote monitoring and digital therapeutics — with procurement heuristics and break-even timelines.
Risk register & device safety brief: a focused primer on pediatric device lifecycle risks and FDA-related recall exposures for growth-adjustable equipment — crucial for procurement, clinical engineering and legal teams.
Competitive intelligence dossiers: strategic profiles, recent moves, and capability heatmaps for incumbent and fast-growing providers — structured to support corporate development, business development, and C-suite strategy sessions.
Operator-ready appendices: sample contracts for community partnerships (e.g., school district integrations), templates for outcome-based payer agreements, and a ready-to-deploy parent engagement framework used in pilot programs.
Competitive landscape — what incumbents and challengers are signaling for 2026
Kindred Healthcare (Louisville, KY) remains a core national provider, leveraging both inpatient and outpatient platforms to deliver multidisciplinary pediatric rehabilitation. Their breadth in neuro-orthopedic programs positions them to capitalize on demand for coordinated, cross-setting care, particularly where payers emphasize continuity and outcomes.
Encompass Health (Birmingham, AL) is extending its pediatric footprint through community-integrated strategies; recent partnerships with local school districts exemplify an approach that reduces barriers to access while aligning with value-based objectives. Expect further collaborations that embed therapy services into community ecosystems.
Select Medical (Mechanicsburg, PA), through its Select Kids subsidiary, demonstrates a focused specialty route — concentrating on complex brain and spinal injury recovery across age groups. Their clinical depth makes them an attractive partner for health systems looking to offload high-acuity pediatric rehab cases.
Children’s Specialized Hospital (Mountainside, NJ) has continued capacity expansion; the opening of a new pediatric brain injury unit signals sustained investment in specialty inpatient capability and underscores demand for focused neurorehabilitation services.
Shriners Children’s (Tampa, FL) is practicing a technology-forward clinical strategy — adopting robotic exoskeletons for gait training across centers — an indicator that capital allocation toward advanced rehab technologies is maturing and will shape referral patterns and clinical outcomes.
Smaller multi-clinic operators such as AbilityPlus Therapy Services are consolidating local demand for developmental and sensory-processing therapy, demonstrating that nimble, community-rooted providers remain important channels for outreach and early-intervention programs.
Together, these profiles reveal a dual-track competitive dynamic in 2026: large system-integrators bolstering specialty hubs and tech capabilities, and local specialist chains or clinics capturing volume through community integration and school-based delivery. With market concentration low, both roll-up strategies and targeted partnerships are viable — the choice depends on capital availability, integration capability, and projected payer contracting environments.
Key dynamics shaping strategy in 2026
Workforce economics: rising specialized pediatric clinician compensation and constrained supply mean that labor will be the single largest determinant of unit economics. Organizations that redesign care pathways to judiciously combine synchronous in-person care with asynchronous digital supports will realize early margin protection.
Technology as clinical and commercial differentiator: adoption of robotics and advanced motion analysis is moving from pilot to operational scale in leading centers. Decisions on where to invest — centralized specialty hubs versus distributed clinic-level devices — should be guided by referral density and reimbursement clarity.
Regulatory & payer friction: Joint Commission pediatric standards, CMS outpatient therapy rules, and child-privacy constraints on telehealth create a complex compliance overlay. Successful operators will standardize consent, privacy, and documentation workflows to avoid downstream revenue leakage.
Device safety and procurement risk: pediatric-specific growth-adjustable equipment carries unique safety and recall exposure; procurement teams must incorporate lifecycle risk scoring into CAPEX planning to avoid clinical disruption from device recalls.
Recommended 90–180 day actions for executives
Run a rapid portfolio stress-test using our provided scenario templates to identify service lines vulnerable to reimbursement shifts and to quantify the benefit of telehealth substitution.
Prioritise one pilot that pairs a specialty inpatient hub with satellite outpatient/telehealth nodes, using robotics or motion-analysis selectively to drive referral concentration and measurable outcomes.
Negotiate at least one school-district or community partnership to create a feeder pipeline and demonstrate community-based outcomes to payers — a low-capex route to volume growth.
Establish a device lifecycle and procurement protocol tied to FDA pediatric safety risk mitigation to protect clinical continuity and limit legal exposure.
How PW Consulting’s deliverables accelerate execution
Our report is structured as an executive playbook — combining a validated market model, operator-ready templates, and competitive dossiers — so teams can move from strategy to implementation without a separate data-gathering phase. For 2026, this means faster capital allocation decisions, clearer M&A target criteria, and immediate internal alignment on workforce, technology, and compliance priorities.
Next steps
PW Consulting’s full report includes the granular regional, therapy-type and disorder-level breakdowns, country snapshots, and company revenue share tables that underpin the recommendations summarized here. Those detailed segment tables and our primary-research interview transcripts are intentionally reserved for report licensees to preserve the actionable edge for decision-makers. To access the complete dataset, modeling workbook, and the operator toolkits, visit our report page or contact PW Consulting’s healthcare strategy desk for a briefing.
For detailed analysis of this topic, please visit the official page:Worldwide Child Rehabilitation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com