
Worldwide Inorganic Pigments for Cosmetics Market — Strategic Briefing for 2026: Actionable Paths for Growth, Resilience, and Product Leadership
PW Consulting’s new market study on Worldwide Inorganic Pigments for Cosmetics provides an operational playbook for executive teams preparing to make consequential decisions in 2026. Built on a 2025 base year and a historical review of 2020–2025, the report pairs granular supplier intelligence with forward-looking scenario models through a detailed forecast horizon of 2026–2032. The market reached approximately USD 950.0 Million in 2025 and is projected to grow to roughly USD 1,350.2 Million by 2032, implying a compounded annual growth rate of 5.15% across the 2026–2032 period. This trajectory creates distinct strategic opportunities and risks for manufacturers, brands, and investors across the value chain.
Worldwide Indwelling Needle Market
Why this report is mission-critical for 2026 decision cycles
- Time-sensitive sourcing choices. The study translates raw material volatility and supply dynamics into procurement playbooks that procurement chiefs can use to lock in cost and availability scenarios this calendar year.
- Product roadmap alignment. R&D and portfolio teams receive prioritized formulation levers—where inorganic pigments can enhance performance (opacity, UV protection, effect finishes) while meeting “clean” and regulatory constraints.
- Investment and M&A readiness. Corporate development and PE teams get an evidence-based shortlist of acquisition and partnership archetypes aligned to consolidation and niche premiumization trends.
- Regulatory compliance assurance. Legal and regulatory functions obtain a compliance matrix that translates heavy-metal limits and global cosmetics rules into actionable product specifications and audit checklists.
Core macro and market dynamics shaping 2026 strategies
Several structural forces are converging to redefine competitive advantage in inorganic pigments for cosmetics. Demand-side momentum is supported by premiumization in color cosmetics and renewed interest in durable, high-performing colorants that combine safety and sensory appeal. At the same time, innovation in surface treatments and hybrid/inorganic-effect pigments is widening formulation possibilities for makeup, sun care boosters, and specialist finishes.
Worldwide Fiber Reinforced Plastic (FRP) Tanks Market
On the supply side, upstream feedstock volatility remains a defining constraint. For example, titanium dioxide markets have shown rapid price and inventory swings: North American prices contracted materially in late 2025 amid surplus supply, and broader export pricing pressures were evident in 2024 market data. Those fluctuations—and ongoing variability in ilmenite and rutile feedstock costs—translate directly into margin pressure for pigment processors and, consequently, pricing dynamics for cosmetic formulators. Our report quantifies these sensitivities and models pass-through outcomes under alternative procurement strategies.
Hand-push Power Trowel Market
Regulatory and sustainability imperatives are equally consequential. Inorganic pigments are subject to strict heavy-metal limits and regionally varying cosmetics regulations; compliance remains a non-negotiable market entry barrier. The market concurrently rewards suppliers who can deliver low-impurity, certified, and eco-conscious pigment grades—demand that is driving recent proprietary product launches and reformulated supply lines targeted at “clean beauty” claims.
Competitive landscape: concentration, capability and strategic positioning
The market exhibits moderate concentration among established chemical and specialty-pigment companies. The leading three firms account for a material portion of global supply (CR3 ~38.5%), and the top five approach a controlling share (CR5 ~52.1%). That structure creates clear roles for global incumbents, regional specialists, and agile niche suppliers.
- BASF SE (Ludwigshafen, Germany) — Known for high-purity grades and regulatory expertise, BASF combines technical-grade titanium dioxide and iron oxide lines with a growing emphasis on nanotechnology-enabled pearlescent effect pigments for premium makeup.
- Sensient Cosmetic Technologies (France) — Offers a broad cosmetic-grade portfolio with surface-treated variants that improve dispersibility and sensory attributes in color cosmetics formulations.
- Merck KGaA (Darmstadt, Germany) — Focused on high-brilliance effect and inorganic pigments with global regulatory compliance, recently expanding UV-optimized effect pigments for facial cosmetic applications.
- Sun Chemical Corporation / DIC (USA) — Markets high-purity iron oxides and TiO2 pigments with low-heavy-metal profiles and ISO/COSMOS-compliant options, including upcycled-material narratives.
- Clariant AG (Switzerland) — Positioned on eco-friendly pigment innovations and clean-beauty formulations; recently launched bio-derived pigments with enhanced dispersibility for cosmetics.
- Venator Materials PLC (UK), LANXESS AG (Germany), Vibrantz Technologies (USA), Neelikon Colors (India), and Cathay Industries/Oxerra (Hong Kong/USA) — Each offers differentiated capabilities spanning titanium dioxide, synthetic iron oxides, ultramarines, and high-purity cosmetic grades tailored to regional markets and technical needs.
Recent product rollouts—bio-derived dispersible pigments, nanotechnology-enabled pearlescent grades, UV-optimized effect pigments, and ultra-high-purity iron oxides—underscore how incumbents are competing on formulation performance, compliance, and sustainability rather than on price alone. Our competitive analysis provides executive-level scorecards, manufacturing footprint maps, and patent/innovation overlays to help leaders decide whether to compete, collaborate, or consolidate.
Report contents: what you will find inside PW Consulting’s full study
- Executive summary with strategic implications tailored to C-suite, R&D, procurement, and corporate development teams.
- Market-sizing methodology (base year 2025), historical dataset (2020–2025), and an integrated forecast model spanning 2026–2032 built on transparent assumptions and scenario toggles.
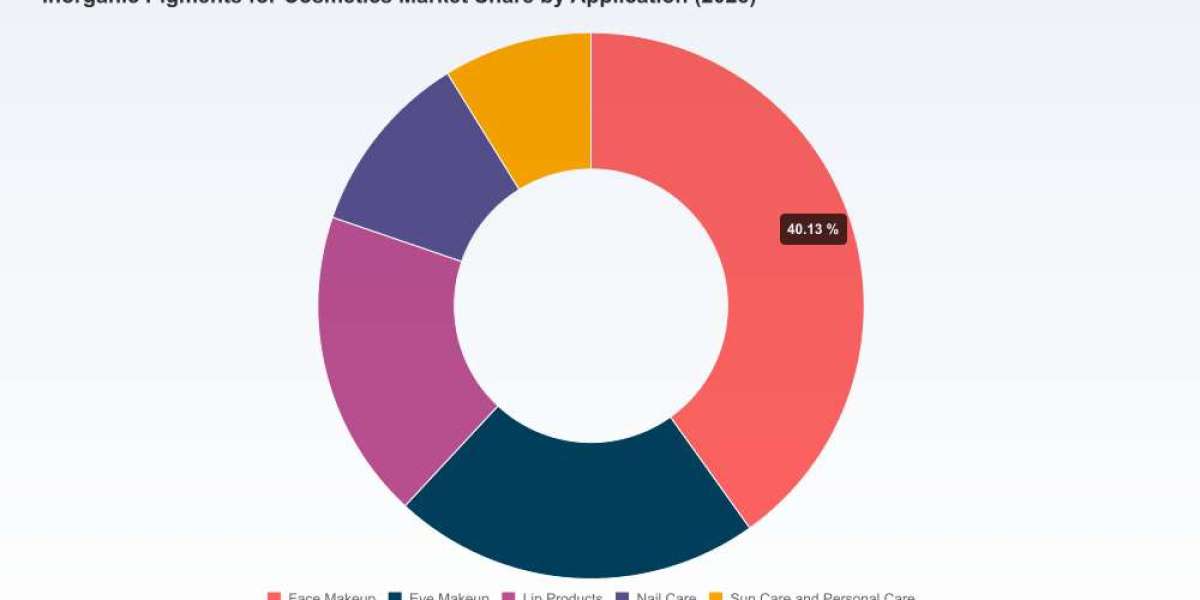
- Demand and application analysis that identifies where inorganic pigments materially shift product economics and consumer value—presented as qualitative opportunity maps and proprietary adoption curves (note: deep segmentation tables are reserved for the full report).
- Supply-side overlays including manufacturing capacities, feedstock sensitivity analyses, and price pass-through models that quantify margin impacts under alternative raw material scenarios.
- Competitive landscape—detailed profiles of the top global suppliers, innovation roadmaps, and M&A heatmaps highlighting target archetypes and valuation benchmarks.
- Regulatory and compliance matrix translating global heavy-metal limits, certification pathways, and labeling implications into a practical checklist for product launches.
- Practical playbooks: procurement hedging strategies, formulation swap lists, green-certification routes, and go-to-market templates for regional market entry.
- Interactive appendices (data tables and sensitivity models) and an annotated list of primary and secondary sources.
How to convert these insights into 2026 actions
- Procurement and supply chain: implement a two-pronged sourcing strategy—secure high-purity core feeds via multi-year agreements while piloting alternative suppliers for specialty effect pigments to manage risk and speed to market.
- R&D and product development: prioritize pigment technologies that deliver demonstrable sensory gains or compliance advantages (e.g., low-impurity, surface-treated, bio-derived). Use our formulation trade-off matrices to quantify cost vs. consumer benefit.
- Commercial and brand: recalibrate value propositions around durability, safety, and sustainability for premium SKUs; reserve price-led plays for commoditized base pigments where scale advantages matter most.
- Corporate development: target acquisition or JV opportunities that expand high-purity capacity, provide access to specialty effect chemistries, or strengthen upstream feedstock control—our M&A diagnostic shortlists targets by strategic fit and integration complexity.
- Regulatory & quality assurance: integrate our compliance matrix into product approval workflows to reduce time-to-market and avoid costly reformulations.
Why PW Consulting’s analysis is unique
Our study combines a commercial-grade supply model with application-level formulation insight and regulatory intelligence. We synthesize pricing data, feedstock trends, supplier capabilities, and formulation economics into decision-ready outputs—scenario models, procurement hedges, and product prioritization tools—rather than a simple top-line forecast. The report’s datasets are built for immediate use by procurement teams, R&D labs, and strategic investors preparing decisions in 2026.
Next steps and access
This briefing intentionally highlights strategic takeaways and the operational utility of the study while reserving detailed segmentation tables, supplier scorecards, and the interactive forecast model for report subscribers. Executives seeking to operationalize the insights—create hedging strategies, execute reformulation pilots, or assess M&A targets—will find the full dataset and playbooks indispensable.
For full access to the complete report, interactive models, and bespoke advisory engagements tailored to your strategic objectives for 2026, please visit the PW Consulting report page or contact our industry team to schedule a briefing demonstration. Our analysts are prepared to walk through scenarios customized to your portfolio and competitive position.
For detailed analysis of this topic, please visit the official page:Worldwide Inorganic Pigments for Cosmetics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com