
Worldwide Alfalfa Feed for Horse Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on Worldwide Alfalfa Feed for Horse (base year 2025; forecast 2026–2032) reframes how senior leaders should think about supply, pricing, and resilience in equine forage markets. The market reached approximately USD 8,510 million in 2025 and, under our base-case assumptions, is forecast to expand at a compound annual growth rate of about 5.8% through the 2026–2032 horizon. These headline dynamics create both immediate tactical choices and multi-year strategic inflection points for producers, traders, feed formulators, and equity investors entering 2026 planning cycles.
Worldwide Mobile Scaffolding Market
Why this report matters for 2026 strategic decisions
- Translate macro growth into executable allocation: growth is steady but unevenly distributed; capital and procurement choices made in 2026 will lock in sourcing patterns through the decade.
- De-risk water- and input-exposure: regulatory shifts and rising production costs mean companies that identify and mitigate hydrological and cost risks this year will enjoy margin advantage.
- Prioritize product-form mix and channel investments: demand for different alfalfa product forms and modern distribution channels is changing the economics of feed portfolios.
- Inform M&A and JV appetites: fragmentation leaves room for value-creating consolidation, but targets must be validated against water, logistics, and quality constraints.
Macro takeaways that should shape 2026 plans
Three headline macrofacts are non‑negotiable for next-year planning. First, scale: the global alfalfa-for-horse market is large and growing—USD 8.51 billion in 2025 with a mid-single-digit CAGR expected through 2032—meaning incremental demand will support new capacity and premium product strategies. Second, concentration is low to moderate: market share is dispersed, and leading producers account for a modest slice of global volume; this creates sourcing optionality but also competitive pressure on margins. Third, input and resource risks are intensifying: production costs have risen materially since 2020, yields have broadly stagnated, and water‑management regulations are already contracting acreage in key producing areas.
Worldwide Whole-meal Bread Premix Market
Operationally relevant datapoints that underpin the above and should be baked into 2026 models include persistent input inflation (notably water, fertilizer, labor, fuel, and machinery), stagnating yield profiles in established producing regions, and basin-level regulatory interventions that have already reduced irrigated area in some critical zones. These forces together compress supply elasticity and increase the value of quality-controlled, traceable forage.
Worldwide Texture Analyser Market
Competitive landscape—how incumbent and emerging players are positioning
The competitive field is broad, spanning regional exporters, vertically integrated forage houses, specialized pellet and cube producers, and branded equine feed formulators. Key players profiled in our study illustrate the range of strategic postures:
- Anderson Hay & Grain Co., Inc.: global exporter with strong bale and pellet logistics; competitive advantage is scale in premium hay and export channels.
- Standlee Premium Products, LLC: brand-led Western forage specialist focused on premium equine nutrition and diversified product forms.
- Al Dahra ACX Global Inc.: combines export-oriented production with global trading capabilities, offering resilience for buyers seeking international sourcing options.
- Green Prairie International and Barr‑Ag Ltd.: North American exporters emphasizing non‑GMO and long‑fiber quality—valuable for premium equine segments.
- Regional producers such as Alfalfa Monegros and Grupo Osés: European specialists supplying premium forage for thoroughbred and performance horse markets.
- Producers of value‑added forms (Cubeit Hay Company, Riverina Pty Ltd): targeting logistics‑efficient, pelleted, and cubed formats that unlock new channels.
- Specialist animal-health and feed formulators (Oxbow Animal Health): integrating alfalfa into branded feed and supplement strategies for higher downstream margins.
The combination of branded products, export capability, and product-form diversity will define winners in 2026. Our competitive scoring in the full report highlights capability clusters—export scale, product innovation, traceability, and customer channel reach—without disclosing proprietary share data here.
Regulatory and resource dynamics that will influence 2026 outcomes
- Water management rules and basin allocations: region-specific groundwater reforms and deficit irrigation programs have already forced supply contraction in some basins; procurement teams should run basin-level exposure analyses now.
- Input-cost inflation: farms are managing 20–35% higher input expenses versus 2020 in many producing geographies; this compresses margins absent pass-through mechanisms or efficiency gains.
- Technology and agronomy shifts: recent equipment launches and seed/varietal investments are improving quality retention and harvest timing; these incremental gains can be folded into premium product narratives.
Operational hotspots and near-term mitigation playbook (2026)
To convert insight into action, we recommend a focused 90–180 day program for companies exposed to alfalfa feed markets:
- Supply‑map and stress-test: identify top-10 sourcing basins and quantify exposure to water restrictions and labor/fuel cost inflation; run downside scenarios to 2030.
- Secure offtake and contract farming: move from spot to blended sourcing (contract + spot) with price indexation tied to transparent input-cost metrics.
- Product-form optimization pilots: launch or expand trials in pellets and cubes where logistics or scarcity favor compressed formats; measure margin impact and customer acceptance.
- Invest in traceability and quality assurance: premium equine buyers increasingly demand provenance; fast-track traceability pilots that can be commercialized in 12 months.
- Operational efficiency: accelerate adoption of best-in-class harvest and conditioning equipment and agronomic practices that preserve fiber quality and nutrient density.
M&A and investment themes to watch in 2026
Given the market’s fragmentation and the capital intensity of logistics and storage for premium forage, expect acquisitive activity around:
- Processing and value-add: pelletizing, cubing and packaging assets that convert raw hay into higher-margin formats.
- Export logistics and cold-chain partnerships: players buying shipping and handling capability to guarantee quality into distant equine markets.
- Water-tech and precision-agronomy providers: firms that lower unit water-use or improve harvest efficiency will command strategic premiums.
- Regional consolidation: bolt-on acquisitions in proven basins to secure long-term supply contracts and create bargaining power with buyers.
What’s inside PW Consulting’s full report (practical, executable modules)
The complete Worldwide Alfalfa Feed for Horse Market report provides the operational detail teams need to act in 2026, including:
- Rigorous market sizing and seven-year forecasts (global and by segmentation axis) and scenario variants for regulatory and input-cost shocks.
- Supply‑chain maps and basin-level risk heatmaps with actionable mitigation options.
- Detailed company profiles and capability matrices assessing export scale, product forms, quality controls, and channel reach.
- Cost‑to‑produce curves, breakeven analyses, and pricing sensitivity models suitable for procurement and FP&A teams.
- Deal desks and M&A screening frameworks, including target prioritization criteria and integration checklists.
- An operational playbook—contract templates, KPI dashboards, and a 12‑month pilot calendar for product-form and traceability initiatives.
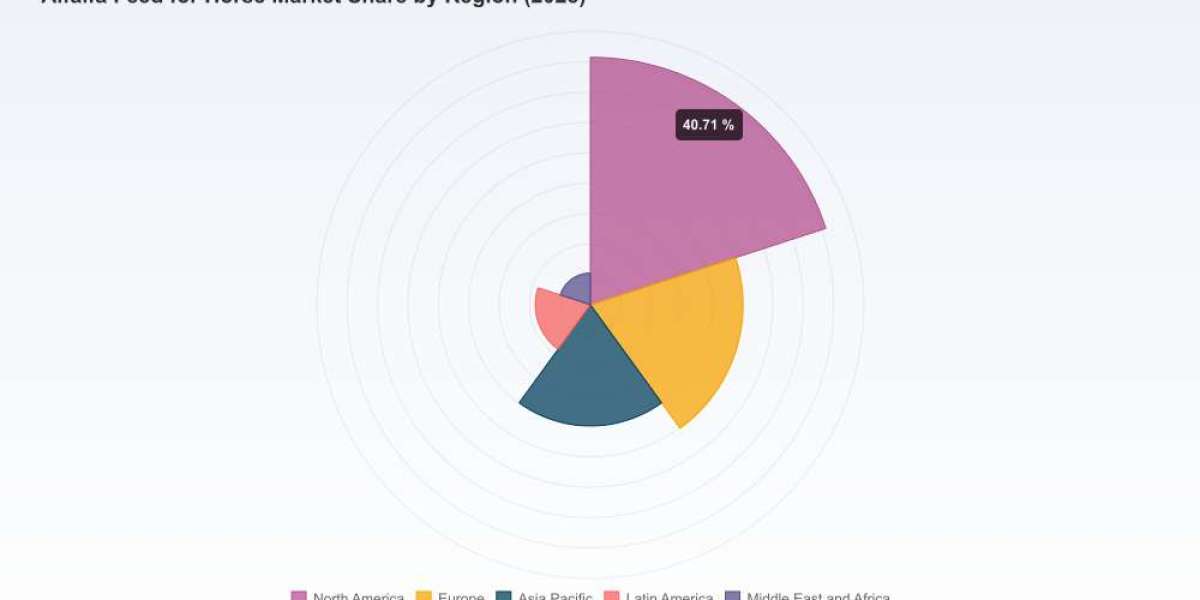
To preserve competitive value in this preview, we deliberately withhold segmented regional and application-level revenue breakdowns; those granular tables, along with downloadable data workbooks and model files, are included in the full report and accompanying Excel deliverables.
Decision checklist for executives and investors
- By March–June 2026: finalize basin exposure mapping and secure prioritized offtake or contingency supply agreements.
- By Q3 2026: deploy a pellet/cube pilot in two strategic channels and evaluate logistics/working-capital impact.
- By year‑end 2026: commit to either (a) targeted M&A in processing/logistics, or (b) multi-year contracted supply arrangements underpinned by traceability and quality premiums.
PW Consulting’s preview should serve as a strategic compass, not a substitute for the granular models procurement, operations, and corporate development teams will need. The full report provides those models, calibrated scenarios, and executable checklists designed specifically to support capital allocation, sourcing, and product innovation decisions in 2026.
For access to the complete study, proprietary datasets, and to schedule a strategy workshop tailored to your organization’s exposure, visit our report page or contact the PW Consulting industry team. The next 12 months offer a narrow window to convert market growth into lasting competitive advantage—firms that act on the signals outlined here will be best positioned to capture both premium margins and sustainable supply chains.
For detailed analysis of this topic, please visit the official page:Worldwide Alfalfa Feed for Horse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com