
Worldwide Wearable Inertial Sensors Market — Strategic Insights for 2026 Decision-Makers
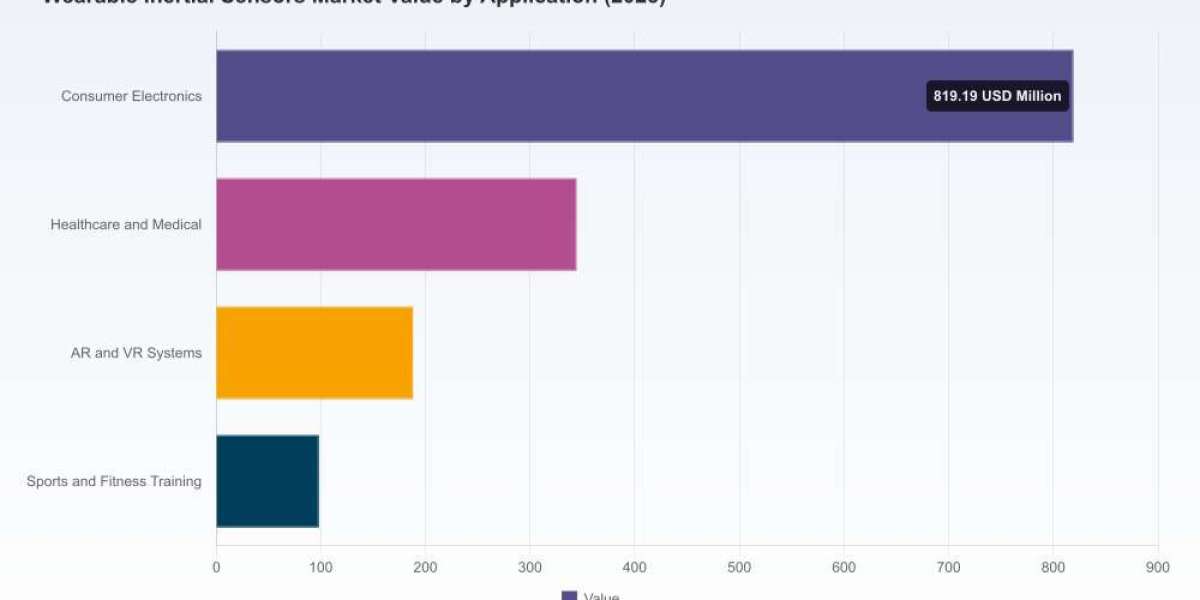
PW Consulting’s new market study on Worldwide Wearable Inertial Sensors (base year 2025; historical 2020–2025; forecast 2026–2032) is designed as an operational playbook for executives planning product, investment, regulatory, or sourcing moves in 2026. The global market shows sustained momentum — growing from a mid‑hundreds USD‑million industry in 2020 to roughly USD 1.45 billion in 2025, and projected to expand to the multi‑billion range by 2032 under a compound annual growth rate (CAGR) of 13.01%. Those macro trajectories underscore that inertial sensing is no longer a niche ingredient but a foundational module across consumer, medical, sports, and immersive‑technology value chains.
Worldwide Integrated Industrial Automation Systems Market
Why this report matters for 2026 strategy
Leaders face three simultaneous transitions in 2026: (1) commoditization of basic MEMS inertial functions alongside rising demand for differentiated sensor fusion and embedded AI; (2) regulatory and standards divergence between wellness devices and regulated medical devices; and (3) consolidation pressures as system integrators and semiconductor vendors sharpen go‑to‑market plays. Our study translates these transitions into prioritized actions: where to invest in silicon or systems, how to structure partnerships and clinical evidence programs, and how to protect product roadmaps from sourcing or compliance setbacks.
Worldwide Automotive Shift-by-Wire System Market
What’s inside — practitioner tools, not just charts
Market sizing and scenario models: transparent, reproducible models covering the 2020–2032 horizon (historical validation, 2026 baseline, and three scenarios for addressable demand and pricing evolution).
Hand Push Electric Trowel MarketDemand archetypes and buyer journeys: segmentation of purchaser needs (consumer OEMs, clinical research organizations, rehabilitation providers, AR/VR OEMs, sports performance vendors) with purchase‑decision matrices and TCO sensitivity drivers.
Technology readiness maps: comparative assessment of MEMS IMUs, accelerometers, gyroscopes, magnetometers and sensor‑fusion stacks by power, latency, size, and embedded inference capability.
Competitive scorecards: vendor capability evaluations (hardware performance, firmware/toolchain, regulatory track record, manufacturing scale, distribution) with bespoke recommendation tiers for sourcing or strategic partnership.
Regulatory & clinical playbooks: decision trees for handling EU MDR, U.S. FDA pathways (including sDHT considerations), and medical‑grade quality systems planning (ISO 13485, IEC/ISO risk and safety standards).
Commercial templates: sample RFPs for IMU modules and wearables, SLA frameworks, licensing and data‑sharing terms, and an M&A diligence checklist for targets from component makers to full‑stack wearable providers.
Implementation case studies: anonymized examples of successful proofs‑of‑concept and scale‑up programs, showing timeframes, cost buckets, and evidence generation strategies that moved pilots to clinical or commercial deployments.
High‑level market dynamics — drivers and friction points
Several structural drivers are fuelling the market: continued miniaturization and power reductions in MEMS, growing adoption of on‑node and near‑sensor AI for motion classification, and rising demand for validated, real‑world mobility data across healthcare, sports, and XR use cases. At the same time, friction points are becoming more prominent: regulatory clarity is improving for low‑risk wellness products but remains stringent for devices making medical claims; suppliers of high‑fidelity IMUs and integrated systems are consolidating, compressing margins for purely component suppliers; and data privacy, interoperability, and clinical validation requirements are raising time‑to‑market and up‑front investment needs for differentiated products.
Competitive landscape — who matters and why
The competitive map resembles a two‑tier structure: global MEMS and mixed‑signal chip vendors that underpin most wearable IMUs, and specialized system providers that package sensors into validated wearables and developer ecosystems.
Silicon and MEMS specialists (examples include Bosch Sensortec, STMicroelectronics, TDK InvenSense, Analog Devices): these firms compete on power, noise performance, sensor fusion, and ecosystem support. Their roadmaps increasingly feature embedded AI inference and lower current draw optimized for continuous monitoring in battery‑constrained form factors. For product teams, the choice among them will often be driven by OS/toolchain compatibility, long‑term supply commitments, and support for medical‑grade lifecycle controls.
System and application specialists (examples include Movella/Xsens, Shimmer, Noraxon, BTS Bioengineering, 2M/QSense Motion, ActiGraph, 221e): these vendors add validated form factors, clinical workflows, and domain‑specific analytics. They are the go‑to partners when the mission requires regulatory certification, research‑grade data quality, or turnkey integrations for gait, biomechanics, or clinical trials.
Recent vendor activity illustrates strategic emphasis across the stack. Semiconductor firms are shipping IMUs with embedded AI acceleration to offload classification tasks from host processors — a clear signal that the race is moving to “edge intelligence.” Separately, IP and biometric authentication patent activity in the wearable interface space reinforces that gesture and biopotential fusion is becoming commercially important beyond straightforward motion sensing. Finally, device makers with regulatory certifications (including CE marks for medical use) continue to outpace peers in clinical and research markets where evidence and compliance are non‑negotiable.
Regulatory and standards implications
Regulation is bifurcating the market into lower‑risk wellness wearables and higher‑risk medical devices requiring documented quality systems and clinical evidence. U.S. FDA guidance in early 2026 further clarified enforcement discretion for low‑risk consumer fitness products while maintaining oversight for devices claiming diagnosis or treatment. In parallel, European MDR and international standards (IEC 60601, ISO 14971, ISO 13485) still govern medical applications. For procurement and product planning in 2026, teams must build regulatory roadmaps in parallel with product roadmaps rather than as afterthoughts.
Strategic imperatives for 2026
Differentiate with software and evidence, not just sensors. With baseline inertial performance commoditized, material differentiation will come from sensor‑fusion algorithms, domain‑specific analytics, and validated clinical endpoints.
Choose sourcing partners for continuity. Secure multi‑source supply and long‑lead agreements with MEMS suppliers that can provide device lifecycle support and medical‑grade traceability where required.
Invest in embedded AI and edge tooling. Reducing the data pipeline and performing classification on‑device lowers power consumption, data governance burdens, and latency—critical in both consumer and clinical pathways.
Plan regulatory evidence early. For any product that may claim diagnostic or therapeutic use, commit to ISO 13485 and a phased clinical validation program before scaling manufacturing.
Adopt modular architectures. Design sensor modules and firmware abstraction layers so developers can swap or upgrade IMUs without redesigning the entire device, protecting R&D and certification investments.
Prepare for consolidation and partner aggressively. Identify targets for M&A, licensing, or exclusive supply to secure roadmap differentiation and reduce competitive exposure.
How PW Consulting’s study supports boardroom decisions
The report is deliberately outcome‑oriented: it combines a defensible market model (with sensitivity testing at the component and end‑market level), practical procurement templates, technology roadmaps, and vendor scorecards. Rather than publish exhaustive segment worksheets in the executive summary, the study surfaces decisive insights and an operational toolkit you can use immediately to draft 2026 investment memos, procurement schedules, or regulatory submission plans.
Next steps for executives
Use our scenario outputs to stress‑test product and pricing plans under different adoption and component cost assumptions.
Run a rapid vendor selection using the included scorecard to shortlist suppliers for prototype and ramp phases.
Initiate or accelerate evidence generation programs for any product that will be positioned for clinical or regulated markets.
Engage business development with system integrators that offer validated ecosystems to shorten time‑to‑market.
PW Consulting’s Worldwide Wearable Inertial Sensors Market report provides the strategic clarity and hands‑on templates required to move from insight to action in 2026. For the full data tables, detailed segmentation, vendor‑level scores and downloadable operational templates, please visit the report page to access the complete study and supplemental materials.
For detailed analysis of this topic, please visit the official page:Worldwide Wearable Inertial Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com