
Worldwide Ultrasonic Probe Covers Market — Strategic Preview for 2026 Decision-Makers
PW Consulting is pleased to release an executive preview of our in-depth market research on the Worldwide Ultrasonic Probe Covers market. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, this advisory piece is designed to equip senior procurement, product, and corporate strategy teams with the directional intelligence they need to set priorities for 2026. The full study—anchored to a 2025 base year and projecting at a 6.5% compound annual growth rate (CAGR)—combines quantitative forecasting with operational playbooks, regulatory trackers, and competitive due diligence. Below we summarize the strategic implications without disclosing the granular segment allocations reserved for subscribers.
Worldwide Online Music Education Market
Market Trajectory and What It Means for 2026 Planning
Our model indicates the global ultrasonic probe covers market has undergone steady expansion through recent years and is expected to continue growth into the early 2030s. After recovering from pandemic-related supply disruptions, aggregate market value expanded meaningfully between our 2020 baseline and the 2025 base year, and under the central forecast returns to a sustained growth path at a mid-single-digit CAGR through 2032. For executives, this translates into three immediate planning imperatives for 2026:
Worldwide Car Head Pillow Market
- Prioritize capacity and procurement flexibility. A mid-single-digit CAGR over the forecast period implies predictable demand growth but does not obviate episodic supply shocks (raw material shortages and sterilization bottlenecks). Firms should secure multi-sourced agreements and scalable sterilization capacity.
- Convert incremental volume into margin via differentiated offer sets. As unit volumes grow, companies with product or service differentiation—better clarity materials, lower-profile gel-free designs, or integrated infection-control bundles—will preserve or expand margins versus commoditized covers.
- Invest in compliance and packaging optimization. Regulatory clarity and sterilization capacity are gating factors for sterile product expansion. Early investment will reduce time-to-market for sterile lines and minimize cost volatility linked to contracting sterilization services.
What the Report Delivers — Practical Assets for 2026 Execution
The full PW Consulting report is intentionally operational. Beyond forecasting, subscribers receive:
Worldwide Stargazing Telescope Market
- Decision frameworks to size incremental capacity needs under alternate demand scenarios (conservative, base, aggressive) and stress-tested supplier contingency plans;
- A procurement playbook with contract clauses, lead-time benchmarks, and cost-to-serve templates tailored for raw film materials and outsourced sterilization partners;
- Regulatory and reimbursement checklists that map device classification, sterile product submission considerations, and payer dynamics tied to bundled CPT reimbursement models;
- Go-to-market toolkits for product managers, including launch checklists for sterile vs. non-sterile SKUs, end-user adoption levers, and quality/packaging validation templates aligned to ISO 11607 and sterilization standards;
- A competitive scorecard and M&A heatmap that highlights targets, defensive imperatives, and integration risks;
- Scenario-modeled financials that quantify margin sensitivity to input cost swings, sterilization outsourcing, and channel mix shifts.
These deliverables are structured to be immediately actionable for 2026 budgeting and strategic projects while preserving the proprietary segmentation that we reserve for the complete report.
Competitive Landscape: Who Matters and Why
The industry exhibits moderate concentration: the top three players account for a material share of the market, and the top five capture a clear majority. This structure supports scale advantages in sourcing and regulatory operations while leaving room for specialist innovators that focus on clinical differentiation or regional regulatory agility.
- CIVCO Medical Solutions (Coralville, IA, USA) — A broad portfolio player with both sterile and non-sterile disposables, CIVCO’s prominence is reinforced by its trade show visibility and portfolio refreshes aimed at clinical adoption in hospital imaging departments. Their public exhibition of expanded sterile endocavity sheaths underscores an aggressive push into higher-value sterile segments.
- Parker Laboratories (Fairfield, NJ, USA) — Known for gel-free, low-profile designs, Parker competes on infection-control features and ergonomics. Their product positioning is attractive to ambulatory and outpatient settings where handling efficiency and infection prevention are prioritized.
- Kentec Medical (Bicester, UK) — A Europe-headquartered supplier that emphasizes regulatory compliance (including EU MDR) and single-use sterile offerings. Kentec’s global distribution footprint combined with MDR readiness makes it a logical partner or competitor depending on regional strategies.
- Sunray Medical (Edison, NJ, USA) — FDA-cleared product lines and a focus on imaging clarity position Sunray to compete in clinical environments where image fidelity is the priority, such as cardiology and TEE probe applications.
- ImaX Medical (Montreal, Canada) — Focused on high-clarity disposable covers, ImaX targets users who require premium optical properties for image-sensitive procedures.
For 2026, expect continued competition along two axes: (1) scale-enabled cost competition (raw film sourcing, sterilization contracts) and (2) clinical differentiation (material clarity, gel-free systems, reduced-profile sheaths). Our benchmarking tools help buyers and strategists quantify where to compete on cost versus clinical value.
Regulatory, Reimbursement, and Raw Material Dynamics
Understanding the operating environment is core to 2026 decisions. The device classification landscape differentiates sterile from non-sterile covers: certain covers can be Class I exempt while sterile products typically need Class II submission pathways such as 510(k) in the U.S. Sterile products must also align with packaging and sterilization standards (ISO 11607 and ISO 11135/11137 for ethylene oxide and radiation sterilization). These compliance requirements materially affect time-to-market and cost structures.
On reimbursement, probe covers are largely bundled into ultrasound procedure payments rather than receiving a dedicated HCPCS code in most jurisdictions. Consequently, purchasing decisions are frequently made within hospital supply chain budgets rather than being driven by direct reimbursement advantages. This bundles the product into value-based purchasing discussions where total cost of care, infection-prevention outcomes, and workflow efficiency matter more than per-unit price alone.
Raw materials are another strategic lever. The market is moving steadily toward latex-free films—medical-grade polyethylene and polyurethane—driven by biocompatibility and allergy-avoidance requirements. Material selection influences imaging clarity, tactile performance, and sterilization compatibility. Procurement teams that lock favorable long-term agreements for medical-grade polymer films or secure preferred access to sterilization capacity will capture durable cost advantages.
Strategic Priorities for Executives Setting 2026 Budgets
- Embed regulatory readiness into product roadmaps: allocate dedicated budget for sterile-product validation and packaging validation to accelerate sterile SKU launches.
- Negotiate sterilization partnerships with performance SLAs and capacity options: sterilization availability is often the least elastic constraint in sterile product scale-up.
- Differentiate through user-centric product features: low-profile, gel-free, and higher-clarity materials command premium placements in certain clinical workflows.
- Optimize channel and pricing strategies around bundled procurement dynamics: proposals that quantify net savings (infection reduction, OR time savings, reprocessing labor) win procurement committees.
- Monitor M&A and partnership targets: smaller, clinically differentiated specialists are attractive tuck-in targets for larger manufacturers seeking to round out sterile product portfolios.
How PW Consulting’s Research Adds Value
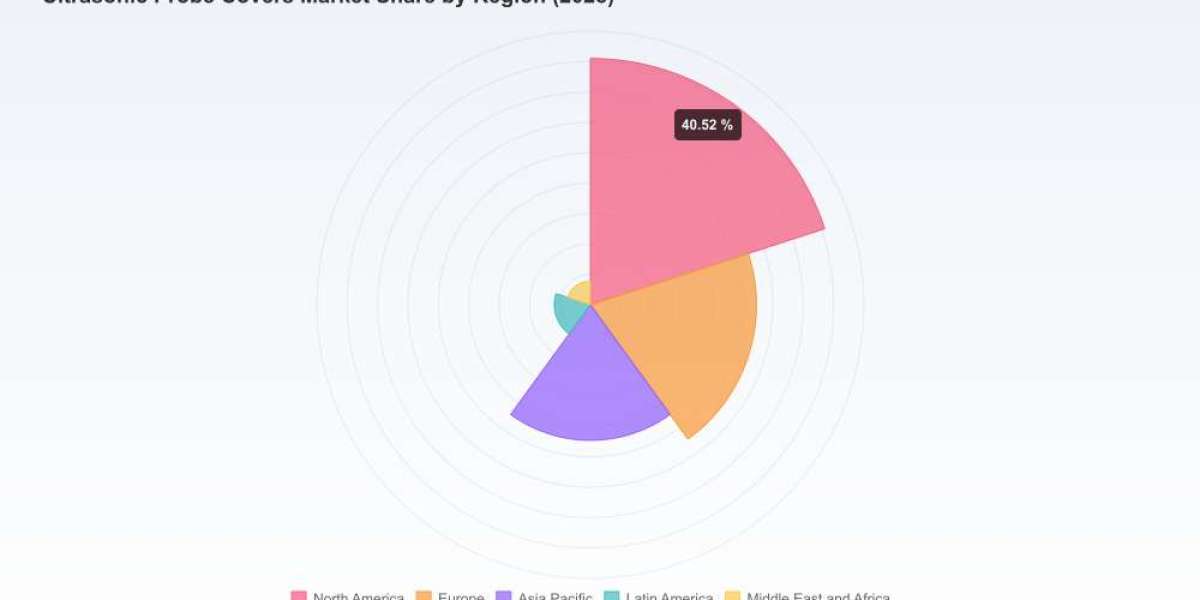
Our report is not merely a forecast—it is an execution manual calibrated for 2026. Clients receive scenario-driven financials to stress-test investments, procurement templates to shorten sourcing cycles, and an up-to-date compliance tracker that flags jurisdictional submission needs. Importantly, while this preview outlines strategic directions and competitive dynamics, detailed segment-level allocations, regional splits, and SKU-level forecasts are intentionally redacted here to preserve subscriber value.
If your 2026 planning hinges on securing supply, accelerating sterile product launches, or evaluating acquisition targets, PW Consulting’s Worldwide Ultrasonic Probe Covers market study provides the empirical foundation and pragmatic tools to act with confidence.
Next Steps
- Contact PW Consulting for the complete report to access the full segmentation, regional allocations, SKU-level forecasts, and our executable procurement playbook.
- Schedule a tailored strategy session to translate the report’s scenarios into a project roadmap for 2026 budgeting cycles.
For the full dataset, proprietary segment breakdowns, and the operational toolkits referenced above, visit our report page or reach out to your PW Consulting representative to arrange an analyst briefing.
For detailed analysis of this topic, please visit the official page:Worldwide Ultrasonic Probe Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com