
Worldwide Furniture Installation and Relocation Service Market: Strategic Insights for 2026 Decision‑Making
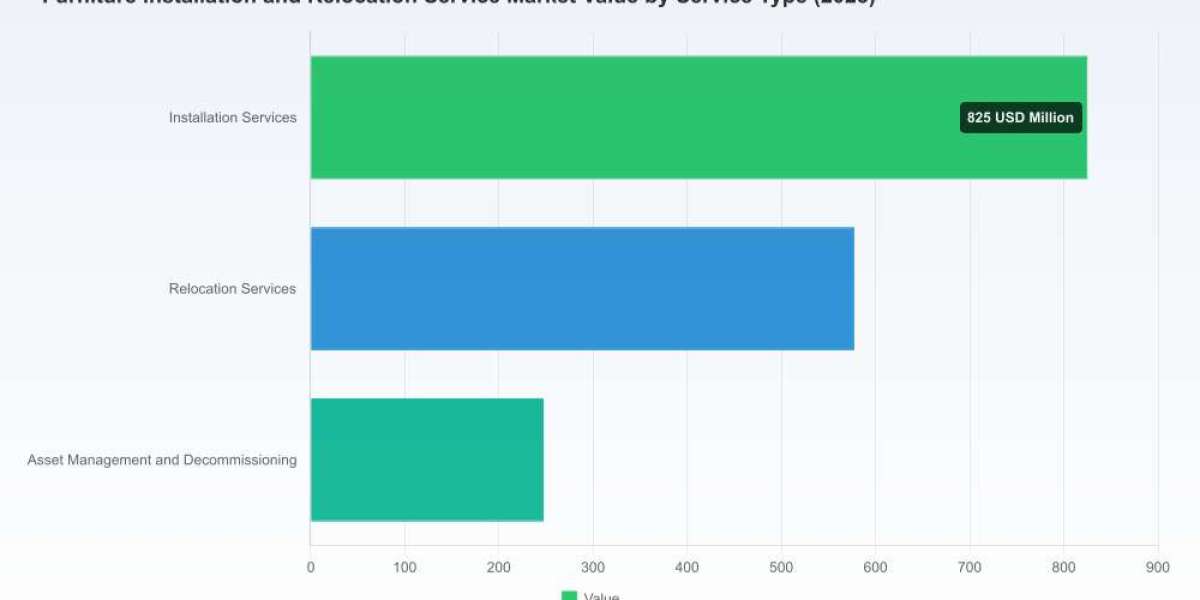
PW Consulting's new market intelligence brief — the Worldwide Furniture Installation and Relocation Service Market Report (base year 2025, historical coverage 2020–2025, forecast 2026–2032) — is designed expressly for senior leaders and transaction teams planning actions in 2026. Anchored in rigorous primary research and financial modeling, the study quantifies a market that we estimate at USD 1,650 Million in 2025 and forecast to grow at a compound annual growth rate (CAGR) of 5.45% through 2032 (reaching a modeled USD 2,400.21 Million by 2032). This release is a concise, practical intelligence package that signals where value will accrue — and where competitive risk is rising — over the next strategic planning cycle.
Worldwide Compact High Pressure Washer Market
Why 2026 Is a Pivotal Year for Providers and Buyers
Momentum and scale: After steady expansion through the early 2020s, the market shows persistent growth into 2026. The near‑term uptick in demand is broad-based — driven by corporate office refits, rental and delivery extension strategies, and continued investment in hospitality and retail rollouts — creating attractive volumes for scale‑oriented operators and platform aggregators.
Edible Fat Replacers MarketOperational cost pressure: Labor cost dynamics are material to margins. For example, US hourly wages for installers and movers averaged approximately USD 18.50 in 2024. Concurrently, automation and improved handling equipment are altering productivity assumptions, as employment growth projections show modest increases relative to other sectors. These two forces — rising labor costs and selective automation — will compress legacy operating models and favor providers that can redeploy capital into tech and training to lift utilization and throughput.
Petroleum-Based Surfactants MarketRegulatory and classification headwinds: Regulation is no longer peripheral. Safety standards (e.g., OSHA handling and storage rules) and worker classification regimes (for example, laws that change gig‑worker status) materially alter cost structures and platform economics. Organizations that build compliance into onboarding, pricing and contractual terms in 2026 will avoid margin erosion and litigation risk.
What the Report Contains — Practical, Transaction‑Ready Intelligence
Executive summary with investment theses tuned for 12–36 month decision horizons.
Market sizing and forecast model (USD, Million) with transparent assumptions for top‑down and bottom‑up scenarios. Base year: 2025; forecast 2026–2032. (Note: this release highlights headline totals and growth rates; detailed subsegment values and regional splits are available in the full dataset.)
Segmentation frameworks (by service type, end‑user and region) and attendant demand drivers — accompanied by sensitivity testing that demonstrates revenue and margin outcomes under different labor, price and capex scenarios.
Cost and pricing benchmarks, including labor rate ladders, productivity norms, equipment amortization schedules and standardized job costing templates to accelerate bids and PI planning.
Competitive landscaping that profiles national platforms, traditional movers, rental & delivery specialists and local aggregators — with capability matrices that map service depth, tech maturity, geographic reach and partnership fit.
Commercial playbooks: go‑to‑market models for platform versus integrated service providers, channel strategies for partnership with retailers and landlords, and contract templates for netting volume guarantees and service level agreements.
M&A and alliance playbook: target screening criteria, valuation multiples guidance, integration milestones and a five‑step synergy capture model tailored to this sector’s unique cost base.
Implementation toolkit: project timelines, vendor selection scorecards, workforce transition checklists and a regulatory compliance roadmap (including applicable safety standards and worker classification risks).
Competitive Landscape — Who to Watch and Why
The market is structurally fragmented: concentration metrics indicate that the largest three firms represent a modest share of total industry revenue and the top five remain well below the levels typical of mature national logistics sectors. That fragmentation creates two strategic outcomes for 2026: (1) continued room for consolidation and bolt‑on acquisitions that meaningfully lift share, and (2) opportunity for niche specialists to defend margins via deep operational craftsmanship.
TaskRabbit (San Francisco, CA) — A platform model that connects users with local Taskers for assembly, installation and relocation work across select markets. Strengths: flexible supply, consumer reach and brand recognition. Constraints: regulatory exposure where gig classification is contested and variable quality control across highly decentralized networks.
Handy (New York, NY) — An on‑demand provider focused on professional installations and moving services in major urban markets. Strengths: streamlined booking flows, urban density economics and integrated payments. Constraints: margin sensitivity to labor cost hikes and challenges in scaling white‑glove enterprise contracts.
Thumbtack (San Francisco, CA) — Marketplace for local professionals, with emphasis on vetting and matching for installation and relocation jobs. Strengths: deep database of pros and a strong search/match experience. Constraints: competitive pressure from large platforms and the need to demonstrate reliability for high‑value commercial clients.
Angi (Denver, CO) — A directory/booking platform that emphasizes vetted contractors. Strengths: brand trust and lead funnels for home service customers; effective for high‑traffic residential channels. Constraints: monetization mix and conversion of directory traffic into repeat commercial relationships.
CORT Furniture Rental & Delivery (Chantilly, VA) — A rental and delivery specialist that bundles installation and relocation services with furniture rental. Strengths: captive rental inventory and B2B relationships with corporate relocations and staging; defensible recurring revenue. Constraints: capital intensity of rental inventory and geographic footprint limits.
Two Men and a Truck (Atlanta, GA) — A national mover with franchise scale, providing disassembly, reassembly and relocation services. Strengths: network density, standardized training and enterprise moving capabilities. Constraints: franchise governance complexity and digital customer experience gap relative to pure‑play platforms.
Bellhop (Nashville, TN) — A tech‑enabled moving service operating in 35+ US cities. Strengths: modern UX, tech for scheduling and tracking, and an urban product-market fit. Constraints: geographic concentration and sensitivity to wage inflation.
Market Dynamics and Risk Factors That Will Drive 2026 Outcomes
Labor and productivity: With installer/mover wages and modest sectoral employment growth, companies that invest in ergonomic tools, modular packaging and digital dispatching will realize 10–20% improvements in effective labor productivity versus peers that do not. This differential is often decisive for win rates on enterprise contracts.
Regulatory impact: Compliance with occupational safety standards and worker classification laws is non‑negotiable. Providers that bake compliance into their cost models early can price confidently and avoid retroactive adjustment risks that otherwise erode earnings.
Platform economics vs. owned capacity: Marketplace models excel at demand aggregation and variable‑cost scalability, while integrated providers control quality and can monetize premium white‑glove services. In 2026, hybrid models that combine a core owned delivery fleet with an on‑demand layer will best reconcile margin and growth.
Fragmentation enabling consolidation: Low concentration among incumbents creates a favorable environment for acquisitive players to build scale rapidly. Expect M&A activity from strategic acquirers and financial buyers seeking roll‑up candidates with clear cost synergies.
Actionable Strategic Recommendations for 2026
Re‑price for compliance: Update standard contracts and job quotes to reflect the true cost of compliance and revised worker classification rules. Build scenario buffers into bids (e.g., labor rate sensitivity and overtime contingencies).
Invest in high‑impact automation: Prioritize investments in lifting equipment, modular packaging and route optimization software that improve first‑mile/last‑mile handling productivity.
Deploy a hybrid supply model: Retain a core in‑house team for premium, recurring B2B clients and integrate a curated on‑demand network for peak capacity and geographically dispersed work.
Pursue targeted consolidation: Use fragmentation to acquire complementary geographic footprints and specialist capabilities (e.g., white‑glove or healthcare settings) to lift average revenue per job and cross‑sell.
Differentiate on reliability and safety: Make OSHA‑aligned safety programs and insurance packages differentiators in enterprise bidding processes.
Leverage partnerships with retailers and landlords: Create bundled service offerings with furniture retailers, multifamily operators and corporate real estate teams to capture downstream installation and relocation flows.
How PW Consulting Translates Research into Executable Outcomes
Our deliverable set is structured to move clients from insight to action rapidly. Alongside the narrative report, PW Consulting provides model deliverables you can operationalize immediately: an Excel forecast model with adjustable assumptions, an M&A screening tool, a vendor selection scorecard, standardized job costing templates, and a 90‑day rollout plan for pricing and compliance updates. For boards and investment committees, we produce a one‑page investment thesis with downside scenarios and expected payback horizons based on deal size and integration intensity.
We intentionally present a high‑fidelity view of market growth rates, headline sizing and structural dynamics while withholding select granular subsegment tables in this public summary. This “trailer” approach establishes the evidence base for strategic discussion while preserving the detailed datasets and competitive intelligence in the full report — which contains the complete regional, service‑type and end‑user splits, supplier financials, and proprietary unit‑economics benchmarks.
For senior leaders preparing budgets, negotiating commercial partnerships, or evaluating acquisition opportunities in 2026, the full PW Consulting report is a tactical asset: it reduces execution risk, accelerates diligence timelines, and supplies the playbooks necessary to convert market growth into durable profit.
To access the complete dataset, modeling files and implementation toolkits behind this summary, please visit our report page and request the Worldwide Furniture Installation and Relocation Service Market Report. PW Consulting’s analysts are available to brief executive teams and investment committees on bespoke scenarios tailored to your strategic priorities for 2026.
For detailed analysis of this topic, please visit the official page:Worldwide Furniture Installation and Relocation Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com