
Worldwide Dienogest Market — Strategic Briefing for 2026 Decision Makers
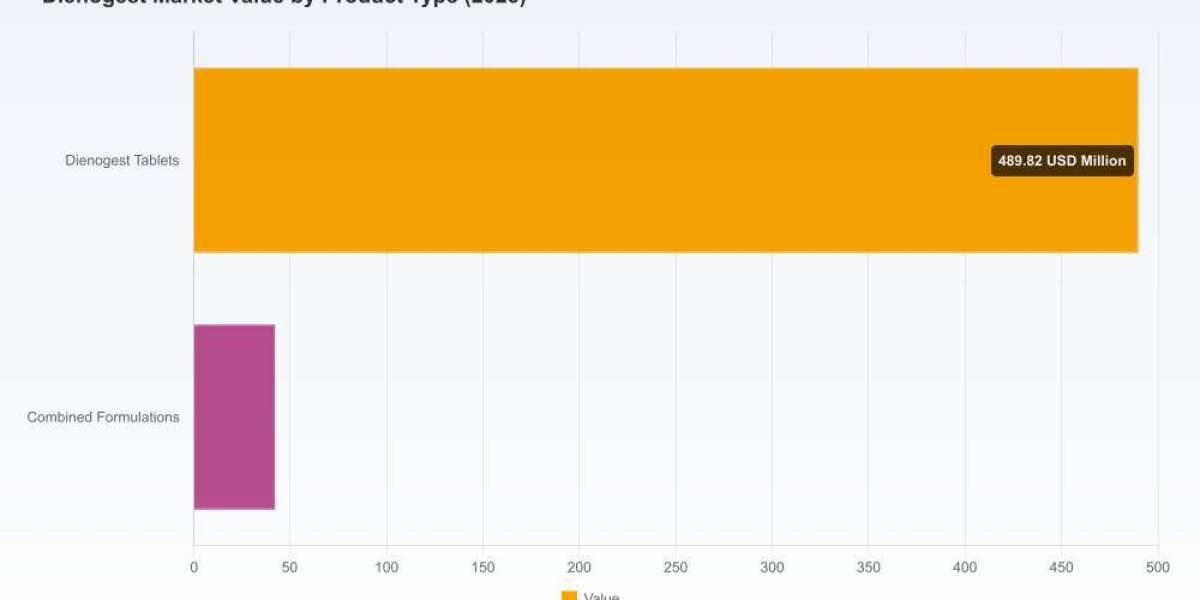
As PW Consulting’s Senior Strategic Advisor, I present a concise intelligence brief distilled from our forthcoming Worldwide Dienogest Market report (base year 2025, historical coverage 2020–2025, forecast 2026–2032). This analysis translates the report’s data and scenario work into immediate implications for commercial, regulatory, and investment choices in 2026. The global market for dienogest has moved from a solid mid-market pharmaceutical niche into a phase of accelerated competitive reconfiguration: revenue rose from USD 385.4 Million in 2020 to USD 532.0 Million in 2025, and our forecast models project expansion to roughly USD 882.6 Million by 2032, reflecting a compound annual growth rate (CAGR) of 7.51% during the forecast window. This trajectory masks important inflection points—patent cliffs, generic entry waves, reimbursement shifts, and supply‑chain centralization—that will materially affect strategy this year.
Flexible Plastic Adhesive Market
Why this report matters for 2026 strategies
- Timing of competitive moves: The market is entering a post-patent phase in many key jurisdictions. First-mover generic launches and regulatory approvals are already reshaping pricing dynamics and share distribution. Companies that align product launches, life‑cycle tactics, and access strategies to this timetable will preserve margin and market presence.
- Concentration and consolidation risk: The market exhibits meaningful concentration among the top players, presenting both barriers and opportunities for new entrants. Our analysis includes concentration metrics and scenario mapping to help prioritize M&A or alliance targets.
- Regulatory arbitrage and access pathways: Variability in label approvals and reimbursement policies across major markets creates differentiated commercial windows. Tactical regulatory investments in certain jurisdictions can yield outsized payoffs relative to development spend.
- Supply-chain leverage: API sourcing geography and supplier footprints are now strategic levers—controlling cost and continuity while managing quality and compliance risks.
Market dynamics shaping 2026 choices
Three structural dynamics dominate the dienogest market in 2026: regulatory pathways, genericization, and market access. First, regulatory status is heterogeneous: while dienogest is approved for endometriosis in many countries, monotherapy approval is absent in the US, creating a persistent commercial exclusion and an adjacent-market strategy challenge. Second, patent expirations in primary markets have catalyzed multiple generic approvals and launches, accelerating price competition and forcing originators to pursue differentiation through service-based offerings, lifecycle extensions, or repositioning. Third, reimbursement regimes in major markets continue to influence formulary placement and patient access—policy shifts or payer negotiations can materially alter uptake curves in a short window.
Worldwide Immunochromatographic Assay Kit Market
Operationally, manufacturers should expect downward pressure on unit prices where multiple generics are active, and relative resilience where branded differentiation, bundled care services, or niche indications maintain clinical preference. Sourcing is concentrated in established contract manufacturing hubs; this centralization reduces manufacturing cost but increases susceptibility to supply disruptions and regulatory audits—two risks that accelerated entrants must manage proactively.
Dancing Video Game Market
Competitive landscape — what the leading players mean for your strategy
The competitive set includes major multinational originators and a cohort of established generic manufacturers. Our report synthesizes company-level qualitative and quantitative assessments, including portfolio fit, go‑to‑market agility, and likely next moves. Key patterns and implications follow:
- Bayer AG: As the originator of branded dienogest therapies for endometriosis outside the US, Bayer remains the tactical benchmark for brand‑level lifecycle management. Post‑patent, Bayer’s strategic choices—defensive pricing, indication expansion, or service integration—will signal the viability of brand preservation in the face of deep genericization.
- Teva Pharmaceutical Industries: Teva’s entry with a generic 2 mg tablet in Germany following patent expiry is emblematic of the rapid generics roll‑out we model. Legacy generics players with established national supply chains are positioned to capture immediate volume, compressing margins for late adopters.
- Viatris (formerly Mylan), Sun Pharma, Dr. Reddy’s, Zydus, Perrigo: These manufacturers form the dependable backbone of global generics supply. Their strengths—scale manufacturing, existing access agreements, and regional commercial teams—mean they will be primary competitors for tender-based and reimbursed volumes. Strategic partners or acquirers should evaluate these firms not only as rivals but as potential collaborators for capacity or market entry.
Recent market events reinforce these dynamics: regulators in major jurisdictions have approved additional generic versions, originator patents have lapsed in key markets, and leading generics manufacturers have expanded supply or launched products in Europe and Southeast Asia. Each event shortens the decision horizon for product strategy and heightens the importance of coordinated commercialization, pricing, and supply policies.
What our report delivers — practical content for executives
The full PW Consulting report is operationally focused. It contains:
- Detailed market sizing and outlook (historical series through 2025, base‑year anchoring, and a granular forecast to 2032), including sensitivity scenarios under alternative pricing, uptake, and regulatory assumptions.
- Competitive intelligence dossiers on originators and leading generics suppliers, with SWOT-style synthesis and likely next-move modeling tailored to 2026 market conditions.
- A decision toolkit for market-entry and life‑cycle management covering pricing simulations, tender strategy templates, and payer negotiation playbooks.
- Supply‑chain and manufacturing risk assessments, including supplier concentration mapping and contingency-plan templates to secure API continuity and regulatory compliance.
- Regulatory pathway maps and market-access checklists for prioritized geographies—highlighting gaps (for example, markets where monotherapy is not approved) and the fastest routes to label expansion or reimbursement inclusion.
- Four executable strategic growth options for 2026: defend (originators), scale fast (generics), partner-and-win (mid-size players), and selectivity (niche/adjacent repositioning), each with investment vs. return profiles and execution milestones.
To preserve the strategic advantage for readers, the report intentionally omits public disclosure of the underlying segment-level tables in this press release. Those segmented models—by region, product formulation, and therapeutic application—are included in the paid report and are the basis for the bespoke scenario outputs and tactical templates described above.
Actionable recommendations for 2026 (executive checklist)
- Prioritize a 90‑day market readiness plan if you are launching a generic: secure API contracts, finalize pricing bands tied to tender cycles, and line up distribution partners in markets where reimbursement pathways are established.
- If you are an originator or branded player, accelerate differentiation strategies: invest in real‑world evidence, integrated patient support services, and targeted indication expansion where label exclusivity remains achievable.
- Evaluate M&A or capacity partnerships with regional generic suppliers to shore up margins and secure supply continuity—particularly where contract manufacturing is concentrated.
- Update payer engagement playbooks: use localized pharmacoeconomic dossiers to defend formulary position and to create access levers in markets with variable reimbursement policies.
- Institute a compliance and quality audit cadence for API and finished‑product suppliers to reduce regulatory risk and to preserve export channels to high‑value markets.
How PW Consulting supports your 2026 execution
The full report combines quantitative forecasts (our baseline points to USD 561.3 Million in 2026 as the near‑term market level, reflecting post‑generic pressures and shifting uptake) with a modular set of advisory offerings: prioritized market-entry roadmaps, bespoke competitor war‑games, and supply‑chain continuity planning. We translate high‑level market numbers into executable tasks—who to call, what contracts to renegotiate, which regulatory filings to sequence—to reduce time‑to‑value in 2026.
Conclusion — the strategic inflection is now
Dienogest is transitioning from a branded specialty product to a contested generic category in many markets. That shift creates both margin erosion risks and scale opportunities. Firms that act decisively in the next 12 months—aligning regulatory, commercial, and supply‑chain moves to the evolving market timetable—will capture disproportionate benefit. Our report provides the detailed, actionable intelligence to make those moves with precision.
To access the full dataset, regional and application-level segmentations, and the step‑by‑step playbooks referenced above, please consult the PW Consulting Worldwide Dienogest Market report available on our website. The full report contains the proprietary tables and models we use to generate the strategic scenarios summarized here.
For detailed analysis of this topic, please visit the official page:Worldwide Dienogest Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com