
Worldwide Yeast Derivatives Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
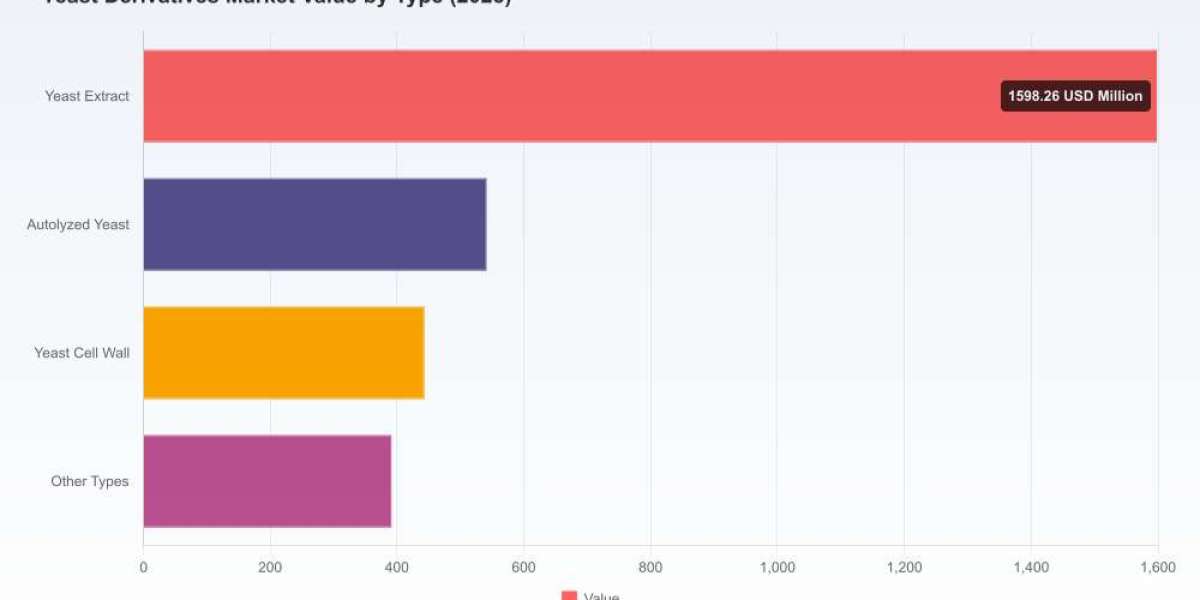
The yeast derivatives marketplace has entered a decisive phase. From a market valued at roughly USD 2.12 billion in 2020, industry-wide revenues expanded to nearly USD 3.0 billion by the 2025 base year and — under the mid-case assumptions modeled in our study — are projected to continue compounding at a 7.0% CAGR through the 2026–2032 forecast window, approaching a multi‑billion‑dollar milestone by 2032. For executives planning capital allocation, commercial prioritization, or inorganic moves in 2026, this report delivers the actionable intelligence required to move from hypotheses to executable strategies.
Sugar-free Snacks Market
Why PW Consulting’s 2026 perspective matters
Timing: Leading indicators in demand (taste-driven reformulation in food & beverage; premiumization in animal nutrition; targeted demand from pharmaceutical and biotech applications) suggest a narrowing window for first-mover advantage on specialty platforms and capacity upgrades. Our report translates these indicators into decision-ready implications for 2026 planning cycles.
Inline Wet Grinder MarketRisk‑aware forecasting: We combine historical trends (2020–2025) with scenariobased modeling to stress-test outcomes across feedstock price shocks, regulatory shifts, and technology adoption curves—enabling executives to quantify downside exposure and upside optionality without overcommitting resources.
Diffractive Optical Elements for Biomedical Equipment MarketCompetitive context: Market concentration remains elevated (CR3 ~42.5%; CR5 ~58.2%), creating both barriers and opportunity pockets. Our competitive diagnostics show where scale, proprietary fermentation know‑how, and application‑focused portfolios create defensible moats and where new entrants can realistically capture share.
What’s inside — practical deliverables for 2026 decision-makers
This report is built as a hands‑on toolkit rather than a descriptive monograph. Highlights include:
Demand engines and scenario canvases — demand drivers mapped to macro trends (clean label, natural flavors, umami-driven savory growth, animal nutrition optimization, and nutraceuticals), with three forecast scenarios that convert thematic momentum into discrete volume and revenue paths.
Value‑chain and margin anatomy — end‑to‑end cost stacks and break‑even analyses for common production routes, including sensitivity matrices that show how feedstock swings and yield improvements drive margin expansion. (Note: feedstock volatility is explicitly modeled; see supply‑risk section.)
Investment and capacity playbooks — practical sequences for brownfield optimization, greenfield sizing, and modular capacity that align CapEx timing with demand inflection points and avoid prolonged underutilization.
Commercial go‑to‑market templates — customer segmentation frameworks, pricing levers, sample contract terms, and partnership models for co‑development with flavor houses, pet food integrators, and biotech B2B buyers.
Regulatory and compliance checklists — jurisdictional compliance paths, risk flags for novel ingredient claims, and mitigation checklists for labeling and safety dossiers in core markets.
M&A landscape and valuation yardstick — a practical multipronged M&A playbook including target archetypes, due‑diligence scorecards, and valuation ranges based on earnings quality and technology defensibility (presented as ranges and scenario outcomes; detailed target‑level financials are available in the full report).
Supplier and feedstock risk matrix — granular supplier scorecards, contract strategies, and a routing plan for feedstock substitution and vertical integration opportunities (note: molasses cost volatility and its production‑cycle impacts are modeled as a primary supply shock in our base and downside scenarios).
Market dynamics that will shape executive decisions in 2026
Demand polarization and premiumization — plain commodity extracts are under margin pressure while specialty flavor variants, functional ingredients (e.g., targeted nucleotides, beta‑glucan concentrates), and pharma‑grade derivatives command structurally higher returns. Firms that can tier offerings and bifurcate channels (commodity vs. specialty) will protect margins while growing volume.
Feedstock exposure — production economics remain tied to sugar‑stream substrates. Price variability and seasonal quality differential materially affect yield and final product composition; our models incorporate realistic molasses price paths and their pass‑through to unit costs.
Regulatory clarity but rising expectations — in major markets yeast extracts enjoy favorable classifications for food use; European frameworks continue to impose stringent oversight that raises compliance costs for ingredient traceability and documentation. Companies must budget for compliance as an ongoing operating expense, not a one‑time cost.
Consolidation and capability aggregation — recent strategic moves illustrate intent: large players are consolidating specialty capabilities through acquisitions and capacity builds, while mid‑sized producers are differentiating through R&D and regional service models. Expect further transaction activity around specialty platforms and regional footprint optimization.
Competitive landscape — positioning and strategic moves
The cohort of industry incumbents combines global reach, fermentation expertise, and application‑level know‑how. Our competitive profiles analyze each firm across four vectors: production footprint and scale, product breadth (commodity vs. specialty), R&D and fermentation IP, and channel strength across food, feed and pharma end‑markets.
Strategic leaders with scale and scope: Firms that integrate broad fermentation capability with global manufacturing are leveraging acquisitions and organic capacity to capture savory and functional growth. Recent notable transactions reflect an intent to consolidate specialty flavor and savory ingredient capabilities and to shore up supply chains.
Innovation‑led challengers: Several producers pursue premiumization by launching flavor variant series and building dedicated specialty production lines. These moves shorten time‑to‑market for customer co‑development and improve margin profiles where technical service matters.
Regional champions: Cost profile advantages and regional channel intimacy continue to let select regional players defend and expand share in local markets and export corridors. Strategic partnerships with global buyers remain a low‑friction route to scale.
Recent strategic actions — implications for 2026
Acquisition activity has accelerated among larger ingredient groups to integrate specialty yeast capabilities and savory platforms; these deals compress the time needed to scale new product lines and can reshape competitive dynamics in targeted channels.
Capacity and product launches from several producers signal that near‑term supply growth will be concentrated in specialty streams—heightening pressure on commodity pricing while creating white‑space for differentiated, application‑specific blends.
These patterns suggest that 2026 will be a pivotal year for locking in strategic supplier relationships, negotiating capacity access, and securing feedstock hedges ahead of demand inflection.
Immediate actions for leaders planning 2026 strategies
Reassess capacity plans against scenario outputs: adopt modular or staged expansion to preserve optionality and match specialty growth without capital overhang.
Hardwire feedstock strategy: pursue diversified sourcing, long‑dated offtake agreements for core molasses or sugar substrates, and evaluate vertical integration where scale economics justify.
Prioritize product tiering and margin pools: define clear product architecture (commodity vs. premium) and align sales incentives and R&D roadmaps to the higher‑return segments.
Prepare M&A playbooks now: develop target criteria, due‑diligence templates, and rapid valuation overlays so acquisition opportunities can be executed within constrained windows.
Invest in compliance and traceability: incremental spend on documentation and quality systems will reduce transaction friction and accelerate market entry for higher‑value applications.
How to use this report in your 2026 planning
The Worldwide Yeast Derivatives Market report is designed as a planning companion: plug its scenario outputs into capital allocation models, use supplier scorecards to prioritize contract talks, and apply our commercial templates to accelerate customer conversions. For C‑suite teams, the report provides a concise set of strategic options and the quantified tradeoffs needed to choose among them. For business unit leaders and M&A teams, it supplies the operational playbooks and valuation frameworks required to move from intent to execution.
Next steps
This release is a strategic preview. To access the full diagnostic suite — including segment‑level demand curves, price and cost models, company scorecards, and executable M&A valuation spreadsheets — visit the PW Consulting portal and download the complete Worldwide Yeast Derivatives Market report. The full package contains the granular inputs and proprietary models that underpin our recommendations and is the only way to obtain the segmental detail and target‑level assessments required for transaction execution and operational planning in 2026.
For detailed analysis of this topic, please visit the official page:Worldwide Yeast Derivatives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com