
PW Consulting: Strategic Brief — Worldwide Laser Type Oil Film Detector Market (2026 Outlook)
Executive snapshot
PW Consulting today publishes an executive briefing of our forthcoming Worldwide Laser Type Oil Film Detector Market report, designed for C-suite executives, corporate strategists, procurement leaders, and environmental compliance teams shaping plans in 2026. Built on a 2025 base year and a historical analysis spanning 2020–2025, the study projects the market forward through 2032. Our core market modelling indicates steady expansion — a projected compound annual growth rate (CAGR) of 6.32% over the 2026–2032 forecast window, with market value rising from an estimated USD 124.5 Million in 2025 to approximately USD 191.2 Million by 2032.
Worldwide Phosphor Screen Market
Why this market matters in 2026
Regulatory pressure and enforcement upgrades — particularly in industrialized markets — are accelerating demand for reliable early-warning systems capable of detecting oil films in drainage, storage and process water systems. Laser-based detection technologies are increasingly relied upon to satisfy evolving compliance thresholds and to reduce environmental and reputational risk.
Worldwide Automotive Alternative Propulsion MarketOperational resilience and cost containment: operators in oil & gas, power generation, marine/offshore operations and industrial wastewater facilities are prioritizing solutions that minimize false alarms, integrate with existing SCADA/asset-management systems, and lower total cost of ownership through reduced maintenance and longer service life.
Individual Quick Frozen Cheese MarketTechnology convergence: advances in laser optics, signal processing and edge analytics are improving sensitivity and discrimination (oil vs. biological or particulate interference), which in turn is expanding viable use cases and enabling new service models.
How our report supports 2026 decision-making
We structured the report as a practical decision-support tool rather than a purely academic exercise. Highlights of the actionable guidance include:
Investment roadmaps that translate market growth forecasts into procurement timelines and capital expenditure windows — enabling CFOs and asset managers to phase purchases and trials to capture the most immediate compliance and operational benefits.
Vendor selection frameworks grounded in performance metrics, deployment-readiness, certification status and lifecycle economics — enabling buyers to compare providers on the dimensions that matter for industrial deployments.
Integration playbooks for combining laser-type detectors with plant control systems, incident response workflows, and digital twins, including data schema recommendations and latency expectations required for real-time alarms.
Scenario-based risk assessments that quantify exposure under regulatory tightening, worst-case spill events and supply-chain disruptions — informing insurance underwriting discussions and contingency planning.
M&A and partnership scouting insights that identify strategic routes to enter or consolidate presence in the market, including manufacturing outsourcing options and complementary technology niches (e.g., fluorescence sensing, maritime remote sensing).
Data integrity and methodology
The report synthesizes primary interviews with OEMs, end users and systems integrators, proprietary shipment and pricing datasets, and regulatory source material. We applied a blended forecasting approach combining historical trend analysis (2020–2025) with bottom-up demand modelling by application and deployment scenario. Sensitivity testing and scenario analysis were used to stress-test assumptions such as adoption rates, regulatory adoption timing, and average selling price trajectories. Base year is 2025; forecast horizon is 2026–2032; all revenue figures are reported in USD (Million).
Competitive landscape: who to watch
The laser-type oil film detector segment displays a mix of specialized OEMs and regionally dominant providers, with moderate market concentration among the top players. Our competitive analysis profiles product families, technical differentiators, certification status and go-to-market approaches for the recognized vendors driving the market.
Asahi Kasei Technosystem (Japan) — A well-known supplier of the Apolarm™M series, including models designed for micron-level film detection and drainage/settling applications. Recent field demonstrations emphasize thin-layer sensitivity and suitability for oil-water separation facilities. Their portfolio positions them as a strong choice for regulated industrial customers seeking proven, field-tested hardware.
HORIBA Ltd. (Japan) — Offers scanning laser solutions with semiconductor laser modules designed for non-contact detection across flowing and still water surfaces. Product developments in extended module life, improved wave resistance and certification to key EMC and safety directives have strengthened HORIBA’s suitability for demanding industrial environmental monitoring applications.
DKK-TOA Corporation (Japan) — Provides a range of laser-based detectors, including flameproof variants for hazardous-area deployments and long-distance models for remote monitoring. Their engineering focus favors ruggedized applications common in heavy industry.
TOKYO KEIKI INC. (Japan) — Supplies non-contact reflection-type laser detectors aimed at municipal and industrial drainage contexts, with emphasis on preventing outflows from pits, manholes and treatment plants.
Laser Diagnostic Instruments AS (LDI) (Estonia) — Develops remote optical watchers leveraging laser-induced fluorescence for real-time, non-contact detection from elevated platforms. Their technology is notable for longer standoff heights and for targeting environmental monitoring and incident response use cases.
Market concentration metrics indicate that a subset of top suppliers accounts for a meaningful share of industry revenue, but the landscape still allows for technology-focused entrants and regional specialists to compete on performance, certifications and system integration capabilities.
Regulatory and product dynamics that shape vendor selection
Regulation: Legislative updates and tighter environmental rules are an important demand driver. In Japan, for example, laser-based detectors have been cited as enablers for compliance with recent revisions to fire and industrial wastewater regulations, increasing urgency among facility operators to adopt detection measures.
Certification: Industrial customers prioritize devices that meet recognized safety and EMC standards. Select models on the market now carry CE marking and comply with directives relevant to EMC and laser safety, which reduces deployment friction in multiple jurisdictions.
Product evolution: Recent product iterations emphasize extended module lifetimes, improved false-alarm resistance (debris and biological matter), longer detection ranges on still water, and options for explosion-proof housings — all of which materially affect lifecycle cost and deployment scope.
Commercial implications and go-to-market plays for suppliers
Value-selling over price-driven competition: As buyers prioritize lifecycle reliability and integration, suppliers that package detection hardware with analytics, service agreements and proven integration templates capture higher-margin contracts.
Channel strategies: Successful entrants often adopt dual strategies — direct engagement with large industrial operators and partnerships with systems integrators serving municipal and offshore markets.
Service / SaaS adjacencies: There’s growing appetite for subscription-based monitoring services and remote diagnostics that extend the vendor relationship beyond the initial sale and create recurring revenue streams.
Use cases and deployment examples
The report distills real-world deployments into transferable use cases: continuous drainage monitoring, stormwater outfall surveillance, secondary containment monitoring at storage facilities, and offshore platform deck/runoff sensing. For each use case we provide a deployment checklist covering siting, power and communications requirements, false-alarm mitigation tactics, maintenance protocols and estimated uptime expectations — invaluable for operations teams planning pilots and rollouts in 2026.
What the report withholds (and why you’ll want the full version)
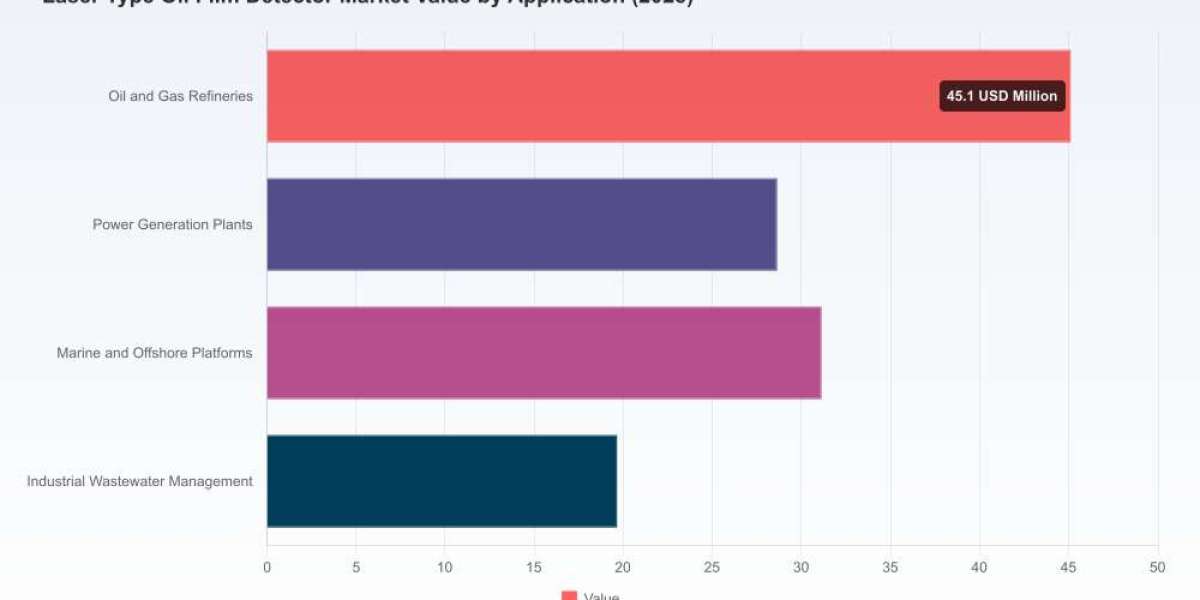
Adhering to a “trailer” approach, this briefing demonstrates the study’s depth but intentionally omits granular proprietary tables and segmented revenue shares by region, type and application that corporate buyers and investors rely upon for transaction-level decision-making. The full report contains detailed segment-level forecasts, vendor share matrices, model-level performance comparisons, and downloadable spreadsheets that support financial modelling and procurement negotiations.
How to use these insights
Procurement and CapEx planning: Use our topline forecasts and adoption scenarios to phase capital investments and schedule pilots in 2026–2027 to align with tightening compliance deadlines and to lock in supply-chain lead times.
Vendor diligence: Apply our comparative framework to screen suppliers quickly, then use the full report’s model-level comparisons during technical evaluation and pilot testing.
M&A and partnership scouting: Leverage our market maps and concentration analysis when assessing buy-side or partnership targets to identify complementary technology stacks or regional strengths.
Next steps
PW Consulting’s complete Worldwide Laser Type Oil Film Detector Market report delivers the full dataset, vendor scorecards, deployment templates and scenario-dependent financial models needed to convert insight into 2026 action. For executives planning procurement cycles, compliance upgrades or strategic investments, the report provides the evidence base and tactical playbooks required to move from assessment to deployment with confidence.
To request the comprehensive study, including model files and vendor appendices, visit our report page or contact PW Consulting’s industry team for a tailored briefing and data extract suited to your organization’s needs.
For detailed analysis of this topic, please visit the official page:Worldwide Laser Type Oil Film Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com