
Worldwide Atmospheric Water Generator Market — Strategic Briefing for 2026 Decisions
PW Consulting’s latest market research on the Worldwide Atmospheric Water Generator (AWG) market synthesizes five years of historical performance (2020–2025) and a seven‑year forecast horizon (2026–2032). The study quantifies a rapidly maturing market that has expanded from a measurable base in 2020 to a robust global industry by 2025, with compounded annual growth projected at 17.15% through 2032. This briefing highlights the report’s strategic value for executives planning capital allocation, product strategy, partnerships, and market entry in 2026 — deliberately showcasing analytical depth while reserving detailed segment-level data for paid subscribers and report purchasers.
Firewall Analysis Tool Market
Why this market matters for 2026 strategic planning
Acceleration and scale: AWG has moved from niche deployments to scalable, commercially viable solutions across residential, commercial, and industrial use cases. Our consolidated market sizing shows the industry expanding from its 2020 base and crossing multiple inflection points through 2025, with further scale expected across 2026–2032 as technology, policy, and financing converge.
Worldwide Government Service Cloud MarketHigh growth posture: A 17.15% CAGR through the forecast period signals that near‑term investments in manufacturing capacity, distribution networks, and service infrastructure are likely to deliver materially higher returns than many adjacent water technologies. For capital planners, that growth rate reframes AWG from an experimental line item into a growth engine worthy of a dedicated strategy.
Sunscreen AVB MarketConcentration indicators: The market is moderately concentrated — the top three and top five players account for a meaningful share of industry revenue, reflecting both strong incumbents with proprietary approaches and room for specialized challengers. These concentration ratios create both barriers and opportunities: incumbent scale advantages coexist with niche demand pockets that reward differentiation.
What PW Consulting’s report delivers — the practical toolkit
We structured the study to be operationally useful to strategy, corporate development, product, and operations teams. Key deliverables include:
Comprehensive market sizing and scenario modeling: granular historical tracking (2020–2025) and probabilistic forecasts (2026–2032) that translate macro growth assumptions into actionable revenue scenarios for portfolio planning and M&A modeling.
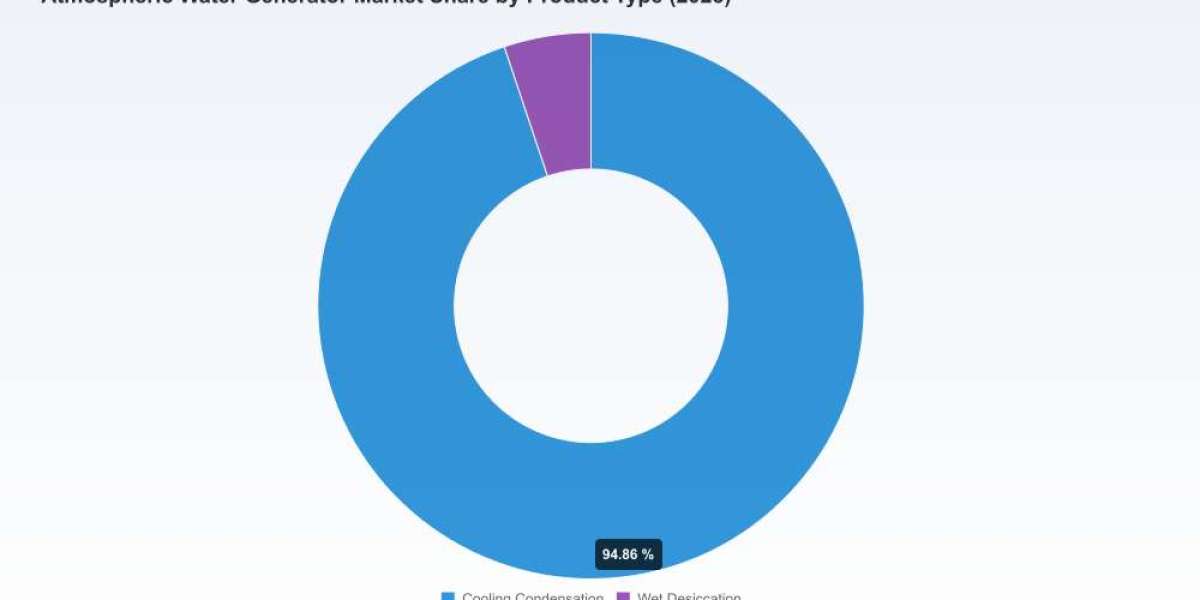
Technology performance matrix: comparative analysis of condensation, desiccant, and solar‑hydropanel approaches against metrics that matter — energy intensity (kWh/L), water quality pathways, maintenance cadence, and suited deployment environments.
Go‑to‑market playbooks: channel economics for residential, commercial, and industrial routes-to-market, including OEM partnerships, B2B distribution, government procurement, and decentralized community deployment models.
Commercial due diligence templates: validated assumptions for revenue waterfall, unit economics, and payback period models to support investment committee decisions and valuation work.
Regulatory and standards compass: mapping of potable water compliance requirements, certification touchpoints, and policy accelerators that influence adoption timelines across priority markets.
To honor the “trailer” design of this briefing, detailed regional, product, and application splits are reserved for the full report — these deliverables provide the precise segmentation depths and models that corporate teams use to set budgets and structure pilots.
Competitive landscape: who matters and how
The AWG competitive field features a mix of technology incumbents, HVAC‑heritage firms, solar innovators, and agile regional specialists. Our assessment of leading and strategically relevant companies is grounded in product breadth, IP and engineering depth, channel reach, and evidence of scaling capability.
Watergen Ltd. (Israel) — A recognized pioneer with patented GENius technology and demonstrated multi‑vertical deployments (residential, commercial, military, vehicle integration). Watergen’s combination of field experience and brand recognition positions it as a benchmark competitor for strategic partnerships and technology licensing.
GENAQ Technologies S.L. (Spain) — Brings an HVAC‑derived engineering pedigree and certified industrial offerings. GENAQ’s design approach is instructive for firms seeking to adapt proven thermal management systems to high‑capacity AWG use cases.
SOURCE Global and solar hydropanels — Demonstrate the viability of solar‑integrated, decentralized potable water generation for off‑grid scenarios. Their path highlights the importance of energy‑water systems integration in project economics and donor/NGO procurement channels.
Regional specialists (India, China, United States, South Africa, Canada) — A diverse set of manufacturers has emerged to serve localized climate, pricing, and regulatory profiles. These firms exemplify competing strategies: low‑cost scale, energy‑efficient high‑end units, and IoT‑enabled service models for uptime assurance.
New entrants and product iterations — Recent product launches and iterations (including compact residential units and scalable Series offerings) show a rapid product innovation cycle where differentiated features — intelligent mineralization, IoT monitoring, and hybrid energy systems — are becoming standard competitive levers.
Our competitive maps stress test incumbent defensibility under scenarios of falling unit costs, tightening energy efficiency targets, and accelerating policy incentives. The result: companies that combine scalable manufacturing, field service networks, and demonstrable water‑quality compliance will capture disproportionate share — but specialized niches will remain open to innovators with targeted performance advantages.
Recent industry movements that will shape 2026 priorities
Policy acceleration: Government incentives and subsidy programs (for example, targeted programs announced in 2025 to promote rural AWG installations) are already shifting procurement calculus for public and non‑profit projects. These incentives materially shorten payback timelines for off‑grid and community deployments.
Productization and scale: The past two years have seen multiple new product introductions — from compact residential units to series modules capable of multi‑thousand‑liter outputs — signaling that suppliers are moving from pilot to productized lines suitable for volume manufacturing.
Cross‑sector partnerships: Integration experiments (for example, in‑vehicle water generation partnerships and joint ventures between AWG specialists and automotive or energy firms) are creating whole‑of‑system propositions that combine mobility, energy, and water needs — a strategic frontier for OEMs and system integrators.
Academic and field validation: Recent installations in academic and resilience‑testing contexts provide objective performance data and reliability baselines that accelerate institutional procurement and donor confidence.
Strategic implications and recommended actions for 2026
Manufacturers and product teams: Prioritize energy efficiency improvements and modular designs that enable factory scaling. Invest in water‑quality instrumentation and remote serviceability to reduce total cost of ownership — proven differentiators in tender processes. Consider hybrid energy options (solar + grid) to widen addressable geographies.
Private equity and corporate development: Use the report’s scenario models to stress test valuations under alternative efficiency curves and policy regimes. Look for tuck‑in opportunities in IoT-enabled maintenance, localized manufacturing, and certified filtration add‑ons that improve margins and recurring revenue potential.
Infrastructure and utilities: Treat AWG as a complementary, decentralized water resource in resilience planning. Pilot deployments should be structured as outcome‑based contracts tied to uptime and water quality SLAs to align incentives and de‑risk scale adoption.
Public sector and donors: Design procurement frameworks that balance unit cost with lifecycle energy consumption and serviceability. Subsidy programs that link to local manufacturing and training will accelerate socio‑economic benefits while improving long‑term sustainability.
What we intentionally withhold here — and why
This briefing surfaces the strategic contours and the key data points that shape decision‑making in 2026 — including aggregate market size and the 17.15% forecast CAGR — while omitting the granular regional, product type, and application monetary breakdowns. Those page‑one segmentation details are core competitive intelligence used by market entrants and incumbents to size opportunities and tailor go‑to‑market tactics; they are provided exclusively in the full PW Consulting report to preserve the integrity of subscription value and ensure readers access validated, model‑backed segment tables.
Next steps — how to use this analysis
Download the full report for detailed segmentation tables, supplier scorecards, and our proprietary market model that allows you to generate custom scenarios by region, product technology, and application.
Engage PW Consulting for a tailored workshop: we apply the report’s scenario engine to your organization’s cost structures and strategic objectives, producing a prioritized roadmap for pilot locations, capex phasing, and partnership targets for 2026.
Request a competitive DD addendum if you are evaluating an acquisition or strategic partnership; we provide supplier diligence, manufacturing cost benchmarks, and integration risk assessments.
Closing perspective
AWG is transitioning from a technology curiosity into an investable, scalable segment of the water‑technology landscape. The market’s trajectory through 2025 and the projected expansion across the 2026–2032 forecast reflect a confluence of improved unit economics, policy tailwinds, and real‑world deployments. For leaders planning 2026 strategy, the imperative is clear: move beyond proof‑of‑concept and shape a practical, financed path to scale. PW Consulting’s full report equips decision‑makers with the quantitative models, competitive insights, and operational playbooks required to act — while this briefing delivers the strategic orientation needed to prioritize investments and next‑step actions.
For detailed analysis of this topic, please visit the official page:Worldwide Atmospheric Water Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com