
Worldwide Reformer Unit Market — Strategic Preview for 2026: Navigating Decarbonization, Modularization and Supply-Chain Realities
Executive summary
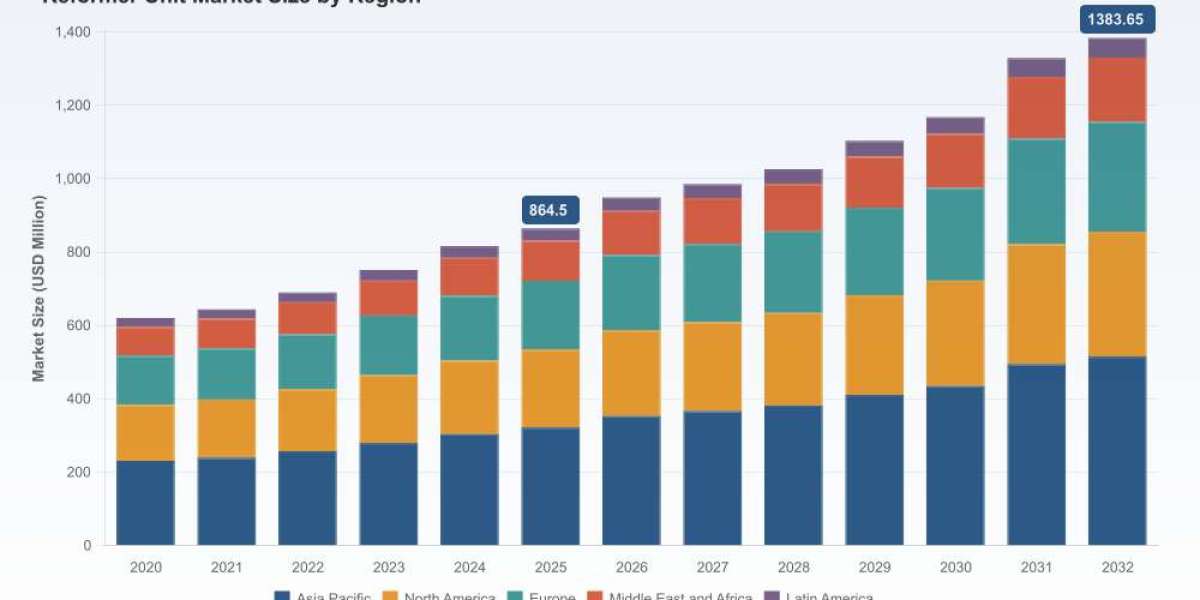
PW Consulting's new Worldwide Reformer Unit Market report equips executives and project sponsors with the strategic context they need to make high‑stakes decisions in 2026. The market for reformer units is at an inflection point: traditional demand drivers from refining and petrochemicals persist, while hydrogen economy initiatives, low‑carbon ammonia projects and stricter greenhouse‑gas frameworks are shifting technology choices and procurement timelines. Our analysis projects the global market to grow from an estimated USD 864.5 million in the report base year (2025) to a materially larger market by 2032, tracking a compound annual growth rate (CAGR) of 6.95% through the 2026–2032 forecast window. This preview explains why that trajectory matters for capital allocation, technology selection and partner strategies in 2026—without revealing the granular segment and regional splits found only in the full report.
5G mmWave RF Shielded Cabinet Market
Why 2026 is a watershed year for reformer decisions
Policy acceleration: Governments and regulatory bodies are sharpening efficiency mandates and pricing carbon in more jurisdictions. Those shifts materially change the NPV of conventional fuel‑fired reformers versus electrified designs or reformers paired with carbon capture.
Automatic Hydraulic Plate Rolling Machine MarketTechnology divergence: Electrified steam reformers (e‑REFORMER) and autothermal reformers are moving from pilot projects to commercial selection in greenfield and retrofit cases. New process variants claim step‑change reductions in direct CO2 emissions and incremental efficiency gains—reshaping CO2 abatement cost curves.
Worldwide Synthetic Hyaluronidase MarketSupply‑chain timing: Raw material cycles—most notably steel—are at a cyclical low entering 2026, with modeling in the report showing procurement timing and alloy selection can shift total installed cost and lifetime maintenance schedules significantly.
Market trajectory and what it means for investors and operators
PW Consulting’s topline sizing establishes a clear, investable trend. The market expands steadily from the report base year and accelerates as hydrogen and low‑carbon ammonia projects scale. The 6.95% CAGR across the 2026–2032 forecast period captures both replacement demand in legacy refineries and incremental installations for low‑carbon production pathways.
For decision‑makers, the near‑term implication is threefold: first, capital planning must incorporate scenario flexibility (conventional, electrified, CCS‑enabled); second, procurement windows offer a narrow advantage where material prices are subdued; third, vendor selection should weigh not only unit cost but the supplier’s roadmap for decarbonization compatibility and long‑term serviceability.
Dynamics shaping demand and technology selection
Decarbonization mandates and carbon pricing: Stricter GHG rules increase the economic attractiveness of electrified reformers and of retrofits that enable carbon capture and storage. Applied‑energy research indicates electrified reformers can reduce flue‑gas CO2 emissions by an order of magnitude in retrofit scenarios and deliver thermal efficiency improvements sufficient to alter lifecycle cost comparisons.
Evolution of the hydrogen economy: Policy targets and announced hydrogen projects continue to provide a volume growth engine for advanced steam and autothermal reformers. The report maps plausible adoption curves for hydrogen for mobility, industry feedstock and low‑carbon ammonia synthesis and quantifies the timing sensitivity of investments.
Materials and fabrication: The cost and availability of high‑performance alloys for reformer tubes and manifolds remain a critical operational constraint. Steel prices are near the bottom of their cycle in early 2026 with a subdued recovery expected across 2026 and a more meaningful upturn from 2027—an input that should inform procurement cadence and inventory strategies.
Modularization and on‑site small‑scale solutions: An increasing number of buyers prefer modular, skid‑mounted or containerized reformers to shorten time‑to‑first‑hydrogen and to reduce project execution risk. Our segmentation of project types suggests modular solutions will capture a rising share of new wins, particularly for distributed and industrial on‑site supply.
Competitive landscape — strengths, gaps and partnership plays
The market remains moderately concentrated, with several large engineering and technology providers commanding significant competitive positions while a broader tier of suppliers captures specialized and local project roles. The report provides granular vendor benchmarking and strategic positioning; the following is a synthesis of observable strengths and decision implications for 2026:
Linde Engineering: Established leader in steam reforming with a global delivery footprint and a growing portfolio of small on‑site hydrogen solutions. Linde’s modular HYDROPRIME® offerings and experience with a range of feedstocks make it a frequent choice for projects that prioritize rapid deployment and integration with industrial gas supply chains.
Honeywell UOP and Axens: Both firms retain strong market positions on the catalytic reforming side, focused on refinery products (high‑octane gasoline, aromatics) and CCR technology licensing. Their value proposition is technology depth and catalyst integration for refinery clients that need yield optimization and uptime guarantees.
KBR and Technip Energies: These engineering and licensor players are prominent in hydrogen and syngas projects, offering steam methane and autothermal reforming technologies aligned to large‑scale industrial clients and projects where EPC scope and integration with downstream synthesis units is strategic.
Johnson Matthey: A critical supplier of reforming catalysts. Catalyst life, performance in variable feedstock conditions and aftermarket support are non‑trivial factors in total operating cost—areas where catalyst licensors continue to differentiate.
MetalTek and Kubota: Specialist manufacturers of reformer tubes and high‑temperature components. Their metallurgical expertise and supply reliability influence maintenance cycles and unit life; decisions on alloy selection will be central to project O&M risk management.
Wood plc and Larsen & Toubro: Engineering and construction firms that bridge local market access and EPC execution capability. For buyers that prioritize local content, schedule certainty and turnkey delivery, these firms are often central to shortlists.
Market concentration metrics in the report indicate a moderate share held by the top global licensors and engineering providers, alongside an active mid‑tier that competes on modular solutions, components and localized EPC offerings. Recent industry developments—such as high‑visibility electrification presentations by technology vendors, and record regional on‑site project wins reported by major licensors—underscore the competitive push toward decarbonization‑ready offerings.
What the PW Consulting report delivers (operationally actionable)
Validated topline forecast model with disclosed methodology, sensitivity runs and scenario outputs for conventional, electrified and CCS‑integrated deployment pathways.
Procurement playbook: RFP templates, techno‑economic checklists, vendor capability matrices and recommended contract structures for 2026 RFQ processes.
Vendor benchmarking and deal intelligence: opaque and public win‑loss analysis, technology roadmaps, and service capability scoring for the leading licensers, catalyst suppliers, tube manufacturers and EPCs.
Cost modelling and materials sensitivity: CAPEX/OPEX breakdowns, alloy selection impacts, and a steel‑price sensitivity module to model procurement timing decisions.
Regulatory and policy mapping: country‑level decarbonization levers, carbon‑pricing scenarios and compliance pathways that materially affect levelized cost calculations.
Operational decision frameworks: retrofit vs. greenfield decision trees, modularization threshold analyses, and lifecycle maintenance schedules tied to alloy and catalyst choices.
Executive summary dashboards and board‑level briefings: condensed slides and annexes designed to accelerate board approvals and capital allocation cycles in 2026.
Strategic recommendations for 2026 decision‑makers
Adopt a dual‑track procurement strategy: short‑list suppliers that can deliver conventional performance while demonstrating credible transition pathways to electrification and CCS compatibility. Contractual flexibility and upgrade options reduce stranded‑asset risk.
Time material purchases: where feasible, accelerate procurement of long‑lead alloy components during the current trough in steel prices, but hedge exposure through staged orders linked to policy milestones.
Prioritize modular pilots: for distributed hydrogen or on‑site ammonia applications, begin modular deployment pilots in 2026 to capture first‑mover operational learning and shorten commercial timelines.
Embed lifecycle assessments: move beyond CAPEX‑only comparisons. Include catalyst replacement schedules, tube creep life, and carbon compliance costs in all project NPV assessments.
Secure alliance partners: the era of integrated, low‑carbon value chains favors consortia where licensors, catalyst suppliers and fabricators commit to retrofit roadmaps and long‑term service agreements.
How to use this preview and next steps
This release is a strategic preview intended to orient 2026 planning. The full PW Consulting Worldwide Reformer Unit Market report contains the detailed regional and application splits, the vendor scorecards, and the proprietary forecasting workbook necessary to execute procurement, investment or M&A decisions. We intentionally withhold those granular tables here to preserve the value of the primary intelligence and to direct practitioners to the full dataset and interactive models available from PW Consulting.
For capital planners, technology officers and procurement leads preparing 2026 budgets and RFPs, the next step is to obtain the full report and dataset to calibrate zone‑specific demand, simulate project economics under your carbon‑pricing assumptions, and build a vendor shortlist tethered to your retrofit/greenfield roadmap.
About PW Consulting
PW Consulting is a strategy and industry analysis firm specializing in energy transition technologies and industrial process markets. Our Worldwide Reformer Unit Market report combines primary interviews, proprietary cost models and rigorous scenario analysis to support high‑stakes decisions across procurement, project finance and technology selection.
To access the full report, detailed tables and the interactive forecast model, please visit the report page on our website or contact PW Consulting’s industry practice for an executive briefing and data license.
For detailed analysis of this topic, please visit the official page:Worldwide Reformer Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com