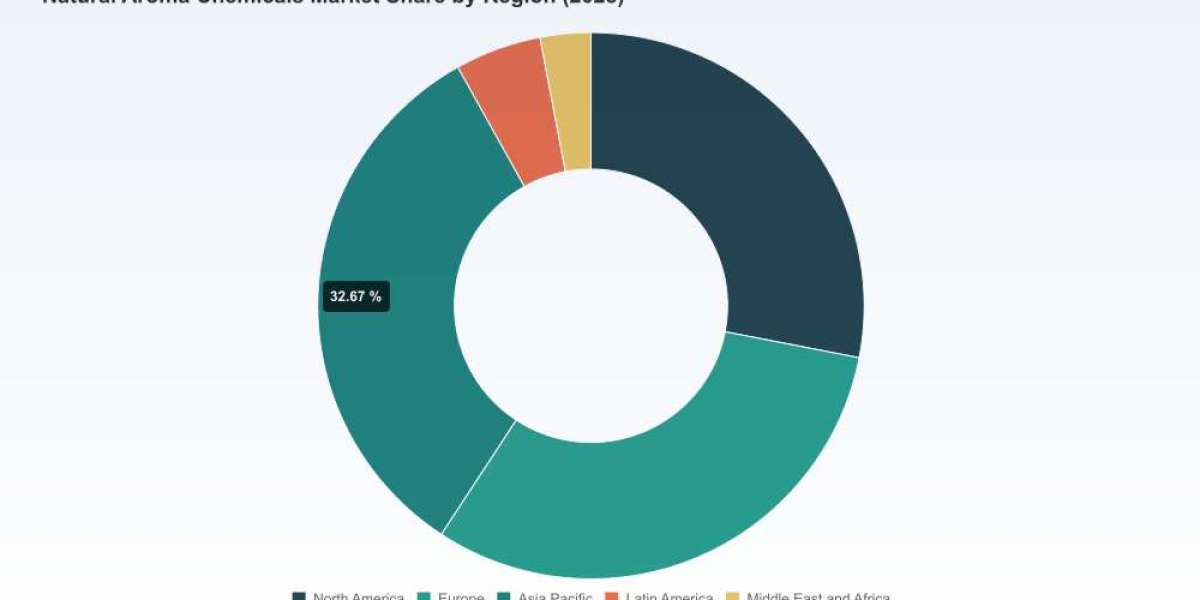

Worldwide Natural Aroma Chemicals Market — Strategic Imperatives for 2026
PW Consulting’s new market study on the Worldwide Natural Aroma Chemicals Market (base year 2025, historical window 2020–2025, forecast 2026–2032) delivers a pragmatic, executive-ready intelligence package designed to influence decisions in 2026 and beyond. The market has expanded materially over the past half decade — rising from a clearly defined low‑baseline in 2020 to an estimated USD 2,504.12 Million in 2025 — and our forecast models project continued expansion to approximately USD 3,968.75 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 horizon. This brief synthesizes the report’s strategic value while deliberately preserving the underlying segmented data to encourage access to the full study for transaction‑level and product‑level intelligence.
Worldwide Dishwasher Salt Market
Why this report matters to corporate leaders in 2026
Accelerating commercialization of biotechnological production routes: Precision fermentation and other biotech methods are shifting cost and sustainability equations for higher‑purity natural aroma molecules. Leading suppliers’ investments in fermentation‑derived solutions are not academic experiments — they are reshaping product roadmaps and go‑to‑market strategies.
Worldwide Soccer Socks MarketSustainability is moving from differentiator to hygiene factor: Reduced product carbon footprint (rPCF) credentials and robust traceability are increasingly essential for premium customers and large CPG buyers. Early movers are converting sustainability claims into pricing power and exclusive offtake relationships.
Cable and Wire Lugs MarketRegulatory tightness and trade policy volatility are strategic supply‑chain factors: Ongoing IFRA/REACH dynamics and new reciprocal tariff frameworks introduced in 2025 require proactive regulatory scenario planning; failure to act can severely erode margin and shelf availability.
Market structure offers both consolidation and niche opportunity: Market concentration metrics indicate a market where the top tier exerts influence but does not fully foreclose opportunity — strategic M&A, alliances, and focused capability plays remain effective routes to scale or margin expansion.
What the PW Consulting report delivers (practical, action‑oriented content)
Quantified market sizing and robust forecasting: Annualized historic and forecast time series (2020–2032) with base year 2025 anchoring. High‑frequency scenario and sensitivity analyses allow executives to stress‑test portfolios against commodity swings, regulatory shocks, and adoption curves for biotech routes.
Segmentation and demand mapping: Multi‑dimensional segmentation by geography, product family, and application—each driven by primary interviews and bottom‑up shipment models. (Note: headline macro totals are presented here; per our “trailer” approach, detailed cell‑level splits are reserved for the full report.)
Supply‑side intelligence and raw materials analytics: Feedstock supply maps, cost‑curve benchmarking, and an integrated view of the essential oils market (the 2025 global essential oils market provides an important feedstock context) together underpin procurement playbooks and supplier selection decisions.
Competitive benchmarking and capability heatmaps: Detailed profiles and strategic positioning analyses of global and regional players — including leaders in biotech, fermentation, sustainable sourcing, and high‑purity chemistry — with actionable implications for partnership, sourcing, and M&A strategies.
Regulatory and policy scenario engine: Forward scenarios for IFRA/REACH developments, tariff regimes introduced in 2025, and likely national policy moves that affect cross‑border trade in botanical derivatives and aroma precursors.
Commercial playbooks and integration templates: Go‑to‑market guides for licensing, co‑development, direct supply, and private‑label manufacturing; pricing strategies; and route‑to‑market checks for entrants and incumbents alike.
Capital allocation and M&A roadmaps: Deal screens, valuation primers for specialty ingredient assets, and integration checklists that reduce execution risk and accelerate realization of synergies.
Competitive landscape — what we observe and what you should watch
Our cross‑reference of primary intelligence and corporate disclosures identifies a cohort of established flavor & fragrance houses and specialty producers actively shaping the natural aroma chemicals landscape. Leading global players are doubling down on sustainability and biotech: firms with integrated R&D, fermentation platforms and botanical sourcing networks are positioning to capture premium value. Examples of strategic signaling include the acceleration of rPCF‑labelled ingredients and the launch of fermentation‑derived specialty molecules by major suppliers; investments in dedicated production facilities for bio‑sourced or biodegradable molecules also illustrate industry direction.
Key names featured in the report include global leaders and specialist suppliers who collectively set innovation and sourcing norms. These firms’ public commitments and recent product initiatives make clear where technology and commercial priorities lie, and the report provides a comparative lens across capabilities such as high‑purity extraction, fermentation scale‑up, traceability systems, and commercial reach.
Recent high‑signal developments we examine in the report include product launches that tie sustainability claims directly to aroma product portfolios and the opening of advanced bio‑based ingredient production facilities — concrete moves that shorten the path from lab to market for new natural aromas and raise the bar for entrants and customers demanding lower‑carbon solutions.
Five strategic moves for executives to prioritize in 2026
Invest in or partner for biotech scale-up now. Precision fermentation is moving past pilots; partnerships that secure IP or capacity will materially influence long‑term COGS and sustainability positioning.
Build an rPCF and traceability roadmap. Work with suppliers to obtain verified footprints, and use traceability as a commercial lever in negotiations with large personal care and premium food buyers.
Diversify feedstock exposure and create hedging protocols. Volatility in vegetable oil and essential‑oil inputs and 2025 tariff changes argue for multi‑sourcing, index‑linked contracts, and strategic inventory buffers tied to cash conversion analyses.
Use targeted M&A and JV structures to buy capability, not just revenue. Look for assets that deliver fermentation scale, regulatory dossiers, or proprietary botanical sourcing relationships to accelerate time‑to‑market.
Operationalize regulatory stress‑testing. Make IFRA/REACH change scenarios part of product development sprints to avoid costly reformulation windows and to seize first‑mover advantages where reformulated “clean” ingredients clear the market.
How senior leaders should operationalize the report
C‑suite decision‑makers will find the report useful as an inputs library for three common 2026 decision cycles: (1) annual capital allocation and R&D prioritization, where tradeoffs between biotech investments and botanical sourcing are quantified; (2) procurement and supply chain strategy reviews, where price‑volatility mitigation and tariff exposure are modeled; and (3) commercial portfolio and route‑to‑market planning, where premiumization and clean‑label positioning translate into differentiated pricing power.
Functional teams can extract immediate value: procurement teams can adopt our supplier risk heatmaps; R&D leaders can use the formulation substitution matrices and regulatory‑safe lists; M&A teams get a prioritized target list and valuation frameworks; sustainability teams get an operational LCA approach to generating rPCF claims that withstand auditor scrutiny.
Data integrity, methods and where to get the full intelligence
The study combines bottom‑up shipment and production models with primary interviews across the value chain, supplier financials, trade flows, and a proprietary price and cost database for key botanical feedstocks. We apply multi‑scenario forecasting and Monte‑Carlo sensitivity testing to provide resilient decision outputs, and we triangulate regulatory impact using policy scenario engines. For executives seeking transaction‑level tables (regional and application splits, product‑level volumes, supplier shares, and deal‑by‑deal M&A valuation benchmarks), the full report delivers downloadable datasets and appendices.
PW Consulting’s “trailer” approach intentionally showcases strategic conclusions and implications while withholding the granular cell‑level segmentation that competitors or counterparties might use. For companies preparing bid books, procurement negotiations, or M&A diligence, the complete data package is essential — and available through our report access channels.
Closing perspective
Natural aroma chemicals are no longer a niche technical input. By 2026, they are a strategic lever for brand differentiation, margin management, and supply‑chain resilience. Companies that align investment, procurement and regulatory strategies to the structural shifts we identify — notably biotech scale‑up, verified low‑carbon ingredients, and trade‑aware sourcing — will convert market growth into durable competitive advantage. PW Consulting’s Worldwide Natural Aroma Chemicals Market study turns market momentum into executable strategy; for the full forecast matrices, regional and application level breakdowns, and the supplier‑by‑supplier dossiers that underpin these recommendations, consult the complete report.
For detailed analysis of this topic, please visit the official page:Worldwide Natural Aroma Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com