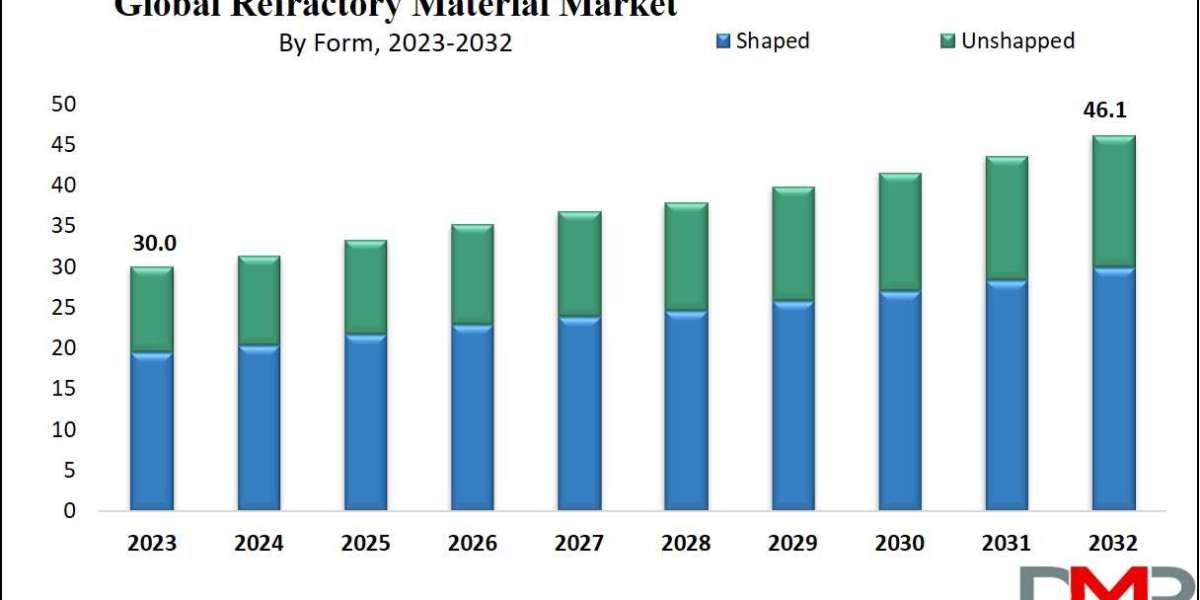

The Refractory Material Market is an important part of modern industrial manufacturing, supporting operations that require resistance to extremely high temperatures, chemical corrosion, mechanical stress, and thermal shock. Refractory materials are widely used to protect furnaces, kilns, reactors, vessels, and other high-temperature equipment across industries such as iron and steel, cement, glass, non-ferrous metals, petrochemicals, and power generation.
According to Dimension Market Research, the Global Refractory Material Market is expected to increase from USD 30.0 billion in 2023 to USD 46.1 billion by 2033, registering a 4.9% CAGR during 2024–2033. The market is supported by industrial expansion, infrastructure development, increasing steel production, and demand for durable thermal protection solutions.
Refractory materials are designed to maintain structural integrity under severe operating conditions. Their ability to withstand high temperatures and corrosive environments makes them essential for industries where production equipment is exposed to continuous thermal and chemical stress.
Refractory Material Market Size and Growth Outlook
The Refractory Material Market is projected to reach approximately USD 46.1 billion by 2033, compared with USD 30.0 billion in 2023. The market is forecast to expand at a 4.9% CAGR during the forecast period.
The growth of steel manufacturing remains one of the most important factors supporting refractory demand. Refractory products are used in furnaces, converters, ladles, reactors, and other equipment involved in metal production. As steel production expands alongside infrastructure, construction, automotive manufacturing, and industrial development, consumption of refractory products also increases.
Cement and glass manufacturing provide additional demand opportunities. Both industries rely on high-temperature furnaces and kilns that require materials capable of maintaining thermal stability and resisting chemical attack.
Key Market Indicators
- Market Size, 2023: USD 30.0 Billion
- Forecast Market Size, 2033: USD 46.1 Billion
- CAGR: 4.9%
- Asia-Pacific Share, 2023: 82.3%
- Leading End User: Iron & Steel
- Leading Form: Shaped Refractories
- Leading Product: Clay Refractories
- Leading Alkalinity: Basic Refractories
Complimentary Sample Report
Businesses, manufacturers, investors, procurement teams, and industry professionals can explore detailed market insights through the complimentary sample report.
https://dimensionmarketresearch.com/request-sample/refractory-material-market/
Key Factors Driving the Market
Expansion of the Iron and Steel Industry
The iron and steel industry is one of the largest consumers of refractory materials. Furnaces, ladles, converters, and reactors operate at extremely high temperatures and require protective linings to maintain equipment performance.
Growing steel demand from construction, automotive manufacturing, infrastructure development, machinery, and transportation is therefore supporting demand for refractory products.
Steel manufacturers also need refractory linings that can provide thermal insulation, mechanical durability, and resistance to molten metal and slag. Regular replacement requirements further contribute to recurring demand.
Growth in Cement and Construction Activities
Construction activity is another important contributor to refractory consumption. Cement manufacturing requires rotary kilns, clinker coolers, and other high-temperature processing equipment.
As developing economies invest in residential buildings, commercial structures, transportation infrastructure, industrial facilities, and urban development, cement production can increase. This creates additional requirements for refractory materials capable of handling continuous exposure to high temperatures.
Increasing Glass Production
Glass manufacturing depends on specialized furnaces capable of maintaining extremely high and stable temperatures. Refractory materials protect these furnaces from thermal shock and chemical corrosion.
Materials such as alumina-zirconia-silica are used in specific glass furnace applications because of their resistance to interaction with molten glass. The expansion of glass manufacturing for construction, automotive, packaging, and consumer applications can therefore create additional demand.
Industrial and Petrochemical Development
Petrochemical and chemical facilities operate reactors, incinerators, refining units, and other equipment under demanding thermal conditions.
Refractory materials provide insulation and protection in these environments while helping equipment withstand high temperatures and corrosive substances. Industrial development in emerging economies is expected to create further opportunities for advanced refractory products.
Major Market Trends
Shift Toward Sustainable Refractories
Sustainability is becoming increasingly relevant across the refractory industry. Manufacturers are developing products with improved service life, lower environmental impact, and greater recyclability.
The use of recycled refractory materials can reduce raw material requirements and support more efficient resource utilization. DMR reports that more than 90% of refractory materials are recycled or reused, highlighting the importance of circular approaches within the industry.
Digital Monitoring and Predictive Maintenance
Digital technologies are increasingly being integrated into refractory applications. Sensors and monitoring systems can help track thermal conditions, wear, and equipment performance.
Predictive maintenance can help industrial operators identify potential refractory failures before they result in unexpected shutdowns. This can support improved equipment availability and more efficient maintenance planning.
Lightweight Refractory Solutions
Energy-intensive industries are increasingly interested in lightweight refractory materials that can provide thermal insulation while reducing material requirements.
Lightweight solutions can contribute to improved energy efficiency and lower thermal losses, particularly in furnaces, kilns, and industrial heating equipment.
Advanced Material Development
Nanotechnology, improved formulations, and advanced manufacturing techniques are opening new possibilities for refractory products.
Manufacturers can develop specialized materials with enhanced heat resistance, durability, corrosion resistance, and thermal performance for specific industrial environments.
Market Segmentation
The Refractory Material Market is segmented by form, product, alkalinity, and end-user.
By Form
The market includes:
- Shaped
- Unshaped
Shaped refractories represent the leading segment. These products can be manufactured into specific geometries for use in furnaces, kilns, reactors, and other industrial structures.
Their ability to provide customized thermal protection makes shaped refractory products important across steel, cement, and glass manufacturing.
By Product
The market is divided into:
- Clay
- Non-Clay
Clay refractories account for a significant market position because of their relatively lower cost and availability of raw materials.
Fireclay bricks and related products are widely used in industrial furnaces and steel manufacturing environments. Non-clay refractories, meanwhile, can provide specialized characteristics such as improved corrosion resistance and thermal performance.
By Alkalinity
The market is segmented into:
- Basic
- Acidic & Neutral
Basic refractories hold a leading position in the market. They are suitable for environments where alkaline slags and operating conditions require materials with appropriate chemical stability.
These products are used across furnaces, kilns, incinerators, chemical facilities, and metal processing operations.
By End User
Major end-user industries include:
- Iron & Steel
- Non-Ferrous Metals
- Glass
- Cement
- Others
The iron and steel industry represents the leading end-user segment because refractory materials are required throughout multiple stages of steel production.
Role of Refractory Materials in Major Industries
Iron and Steel
Steel manufacturing remains a core application area. Refractories protect furnaces and processing equipment from molten metal, slag, thermal stress, and mechanical wear.
Cement
Cement plants use refractory materials in rotary kilns, preheaters, clinker coolers, and related high-temperature equipment.
Glass
Glass furnaces require refractory materials with excellent thermal stability and resistance to chemical interaction with molten glass.
Non-Ferrous Metals
Aluminum, copper, zinc, and other non-ferrous metal processing operations require specialized refractory linings capable of handling high temperatures and corrosive materials.
Petrochemicals and Chemicals
Refining and chemical processing facilities use refractories in reactors, incinerators, heaters, and other high-temperature units.
Power Generation
Refractories are also used in boilers, gasifiers, incinerators, and waste-to-energy facilities where equipment is exposed to high temperatures and demanding operating conditions.
Regional Outlook
Asia-Pacific
Asia-Pacific represents the largest regional market, accounting for approximately 82.3% of global market share in 2023.
The region benefits from large-scale steel production, cement manufacturing, infrastructure development, automotive production, industrialization, and expanding energy projects.
China and India are particularly important markets because of their substantial industrial and construction activity. Japan and South Korea also contribute to regional demand through advanced manufacturing and metal-processing industries.
North America
North America is supported by demand from steel, glass, construction, industrial manufacturing, and energy-related applications.
Investment in manufacturing infrastructure and modernization of industrial facilities can create opportunities for refractory suppliers offering durable and efficient products.
Europe
Europe is expected to maintain steady demand supported by steel, glass, automotive, cement, and industrial applications.
The region's emphasis on energy efficiency and environmental performance is also encouraging manufacturers to develop lower-impact refractory solutions.
Latin America
Latin America's steel, mining, cement, construction, and industrial sectors create opportunities for refractory materials.
Brazil and Mexico are important markets due to their industrial production and infrastructure activities.
Middle East and Africa
The Middle East and Africa offer opportunities through investments in steel, cement, petrochemicals, energy, and industrial infrastructure.
Growing industrial capacity in emerging markets can increase demand for advanced thermal-resistant materials.
Artificial Intelligence and Refractory Materials
Artificial intelligence is emerging as a supporting technology in refractory applications.
AI-enabled systems can analyze operational data and identify patterns associated with refractory wear, thermal stress, and potential failures.
Key applications include:
- Predictive maintenance and failure analysis
- Furnace and kiln process optimization
- Advanced refractory material design
- Automated quality inspection
- Raw material and inventory management
These technologies can help industrial operators improve equipment reliability and reduce unplanned downtime.
Market Opportunities
Emerging Industrial Economies
Rapid industrialization across Asia-Pacific and the Middle East is creating new opportunities for refractory suppliers.
Expansion of steel plants, cement facilities, petrochemical operations, and industrial infrastructure can generate sustained demand.
Renewable Energy
The development of solar, wind, hydrogen, and other energy technologies can create new applications for advanced refractory products.
Manufacturing processes associated with energy-transition technologies may require materials capable of handling high temperatures and demanding chemical environments.
Recycling and Circular Economy
Improved recycling technologies provide an opportunity to reduce raw material consumption and support more sustainable refractory production.
Manufacturers capable of recovering and reusing refractory materials can improve resource efficiency while addressing environmental requirements.
Advanced Manufacturing
Nanotechnology, digital monitoring, automated production, and advanced material engineering can support the development of higher-performance refractory products.
Market Challenges
The industry also faces several challenges.
Raw material price volatility can affect production costs. High-purity alumina, silica, magnesia, and other raw materials can be exposed to supply-chain disruptions, energy costs, and geopolitical factors.
Energy-intensive manufacturing is another challenge. Refractory production requires significant heat, making manufacturers sensitive to energy prices and emissions regulations.
Environmental requirements are also becoming increasingly important. Producers must address emissions, resource consumption, waste management, and the environmental impact associated with certain raw materials.
Smaller manufacturers may face additional pressure because maintaining consistent quality while controlling production costs can require significant investment in technology and process control.
Competitive Landscape
The global Refractory Material Market includes established manufacturers competing through product development, technical expertise, sustainability initiatives, production capabilities, and customized solutions.
Prominent companies identified by Dimension Market Research include Imerys, Saint-Gobain, RHI Magnesita, KAEFER SE & Co. KG, Alsey Refractories Co., Magnezit Group, Harbison Walker International, Dalmia Bharat Refractory, Morgan Advanced Materials, Lanexis, and Vitcas.
Companies are increasingly focusing on sustainable products, recycling technologies, advanced manufacturing, digital monitoring, and application-specific refractory solutions.
Recent Industry Developments
Recent developments demonstrate continued investment in capacity expansion, sustainability, and technology.
RHI Magnesita launched its 4PRO contract model in November 2024, focusing on refractory solutions for industries including cement, steel, and glass.
Vesuvius commissioned new alumina-silica and monolithic refractory plants in Visakhapatnam, India, in November 2024, expanding local production capacity.
Calderys announced investment in a greenfield refractory plant in Odisha, India, in October 2024.
RHI Magnesita also introduced automated sorting equipment for refractory recycling at its Mitterdorf facility in November 2024. In January 2025, the company completed its acquisition of Resco Group, expanding its U.S. business and alumina-based refractory capabilities.
Purchase the Complete Refractory Material Market Report
Businesses seeking detailed market sizing, segmentation, regional analysis, competitive intelligence, market dynamics, and forecasts can access the complete report:
https://dimensionmarketresearch.com/checkout/refractory-material-market/
Future Outlook
The Refractory Material Market is expected to maintain steady growth as industries continue to require materials capable of operating under extreme thermal and chemical conditions.
The expansion of steel, cement, glass, non-ferrous metals, petrochemicals, and power generation will remain important demand drivers. Asia-Pacific is expected to continue playing a central role because of its large industrial base and substantial steel and cement production.
At the same time, sustainability will influence product development. Recyclable refractories, longer-lasting formulations, lightweight materials, energy-efficient manufacturing, and advanced recycling technologies can become increasingly important.
Digital technologies and artificial intelligence can further improve refractory performance by enabling predictive maintenance, process optimization, quality control, and material development.
Overall, the market is projected to grow from USD 30.0 billion in 2023 to USD 46.1 billion by 2033, at a 4.9% CAGR.
Frequently Asked Questions
1. What is the Refractory Material Market size?
The global Refractory Material Market was valued at approximately USD 30.0 billion in 2023 and is projected to reach USD 46.1 billion by 2033.
2. What is the expected CAGR of the market?
The market is projected to grow at a 4.9% CAGR during the forecast period.
3. Which region dominates the Refractory Material Market?
Asia-Pacific accounted for approximately 82.3% of global market share in 2023.
4. Which industry is the largest end user?
The iron and steel industry represents the leading end-user segment because refractory materials are extensively used in furnaces, reactors, ladles, and other steelmaking equipment.
5. What are the major refractory material segments?
The market is segmented by form, product, alkalinity, and end-user, including shaped and unshaped materials, clay and non-clay products, basic and acidic or neutral refractories, and industries such as steel, non-ferrous metals, glass, and cement.
Conclusion
The Refractory Material Market plays a critical role in high-temperature industrial operations by protecting equipment and maintaining reliable production conditions. Strong demand from steel, cement, glass, non-ferrous metals, petrochemicals, and power generation is supporting continued market development.
Technological advances are creating opportunities for more durable, lightweight, recyclable, and energy-efficient refractory products. Digital monitoring and AI-based predictive maintenance can further improve operational reliability and reduce downtime.
With the market projected to reach USD 46.1 billion by 2033, manufacturers that focus on advanced materials, sustainable production, recycling, digital technologies, and application-specific solutions can address the changing requirements of high-temperature industries.
For complete market analysis:
https://dimensionmarketresearch.com/report/refractory-material-market/