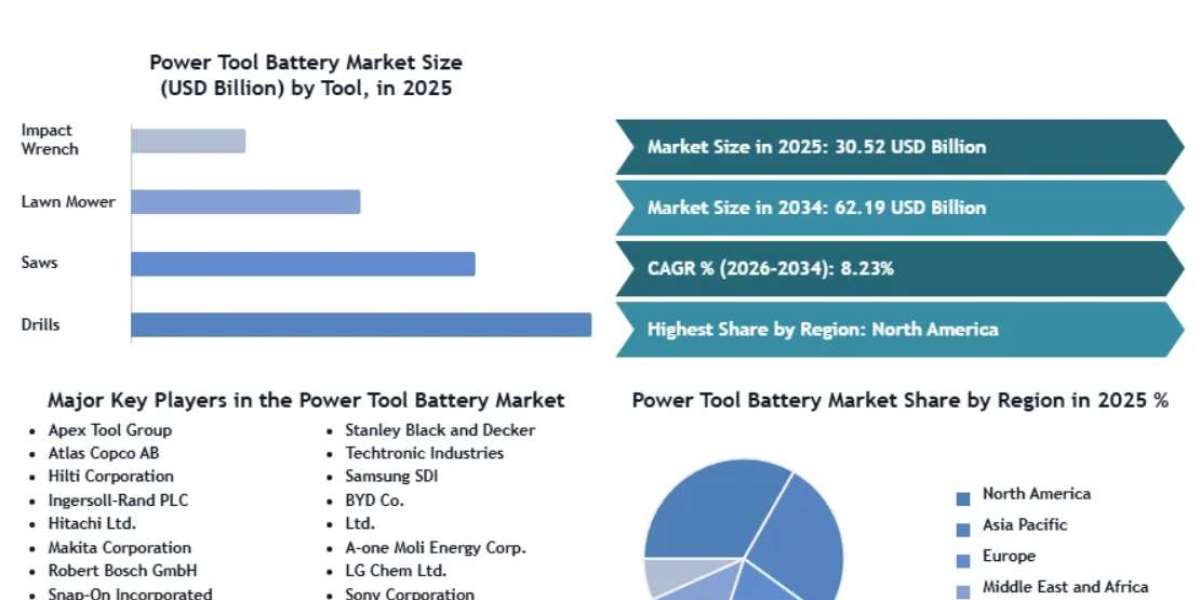

The global Power Tool Battery Market is experiencing an unprecedented structural transformation, scaling up rapidly to reach an estimated USD 16.1 billion by 2030. Growing at a compound annual growth rate (CAGR) of 10.2% from a base year valuation of USD 9.1 billion, the market's expansion is fundamentally anchored on the massive global shift toward cordless industrial utility, cross-brand platform interoperability, and high-density energy storage solutions.
The traditional paradigm of tethered, corded industrial equipment is undergoing a definitive phase-out. Modern construction, automotive repair, aerospace manufacturing, and professional landscaping sectors are heavily prioritizing site mobility, operator safety, and ergonomics. This macro-shift has transformed power tool batteries from simple consumer accessories into high-margin, mission-critical energy assets.
Key Findings from the Report
Market Valuation & Growth: Valued at USD 9.1 billion in the base year, the market is projected to surge to USD 16.1 billion by the end of the forecast period, securing a solid 10.2% CAGR.
Dominant Technology Segment: Lithium-ion (Li-ion) batteries command a dominant market share of approximately 87%, heavily favored for their superior energy-to-weight ratio, minimal self-discharge, and absence of memory effect.
Leading Application Category: Commercial and professional-grade industrial applications capture the lion's share of revenue, propelled by heavy-duty infrastructure projects and high-frequency daily tool utilization.
Regional Frontrunner: North America stands as the leading geographic market, backed by a mature DIY culture, high professional tool penetration, and aggressive municipal electrification mandates across major U.S. metropolitan centers.
Fastest-Growing Region: Asia-Pacific represents the fastest-growing volume market, catalyzed by massive urbanization waves, expanding middle-class demographics, and heavy infrastructural investments in China, India, and Southeast Asia.
Investment Relevance: Venture capital and strategic OEM investments are increasingly funneling into modular design concepts, rapid-charging thermal management systems, and eco-friendly recycling infrastructure to counter raw material price volatility.
Supply-Demand Dynamics: A pronounced shift toward localized regional manufacturing supply chains is mitigating cross-border logistical vulnerabilities, ensuring steady tier-1 component fulfillment for major tool brands.
For further information, click the following link:https://www.stellarmr.com/report/req_sample/Power-Tool-Battery-Market/168
Market Drivers and Restraints
Drivers
Accelerating Adoption of Cordless Industrial Tools: The persistent demand for enhanced job-site mobility, reduction of trip-hazard liabilities, and setup-time efficiency continues to drive mass migration from corded to battery-operated fleets.
Proliferation of Cross-Compatible Battery Platforms: Manufacturers offering unified multi-tool battery platforms are successfully lowering total cost of ownership for end-users, stimulating repeat ecosystem purchases.
Rapid Advancements in Energy Density and Fast-Charging: Breakthroughs in cell chemistry and intelligent Battery Management Systems (BMS) allow tools to operate under extreme industrial loads while recharging in under 30 minutes.
Restraints
High Capital Expenditure and Replacement Costs: Premium lithium-ion battery packs carry high initial price tags, and replacement costs can occasionally rival the price of the tool body itself, straining budget-conscious consumer segments.
Supply Chain Vulnerability for Critical Minerals: Ongoing price volatility and geopolitical dependencies surrounding core raw materials—specifically lithium, cobalt, and nickel—pose persistent cost pressures on tier-2 and tier-3 OEMs.
Technology, Regulation, and Sustainability Trends
The power tool battery landscape is increasingly dictated by stringent environmental mandates and circular economy frameworks. In Europe and North America, incoming regulatory frameworks regarding battery passports and mandatory recycling thresholds are compelling manufacturers to move away from disposable, glued-pack designs.
Technologically, the integration of smart IoT-enabled BMS chips allows predictive health monitoring, preventing thermal runaway and maximizing cell lifecycle performance. Concurrently, sustainability initiatives are taking center stage; leading OEMs are incorporating recycled plastics into battery housings and establishing closed-loop recovery channels to reclaim high-grade lithium and cobalt, directly aligning with corporate Environmental, Social, and Governance (ESG) mandates.
Regional Insights
North America: Retains its crown as the dominant regional market. Growth is heavily anchored by widespread adoption among commercial contractors in the United States and Canada, where high labor costs make operational speed and tool efficiency paramount.
Europe: Acts as the regulatory trendsetter. Driven by stringent European Union circular economy directives and net-zero construction frameworks, the region is seeing rapid adoption of modular, easily recyclable battery packs.
Asia-Pacific: Emerges as the high-velocity volume engine. Rapid industrialization, expansive residential and commercial real estate projects across India and China, and rising consumer disposable incomes are generating unprecedented baseline demand.
Latin America, Middle East & Africa (LAMEA): Shows a bifurcated outlook. While urban centers in the Middle East and Latin America are accelerating adoption through government-backed infrastructure and housing developments, price sensitivity remains a temporary barrier in lower-income rural zones.
Recent Industry Developments
Stanley Black & Decker (2025): Launched an advanced high-capacity pouch-cell battery platform designed to deliver up to 50% more power and double the lifespan for heavy-duty construction applications, expanding its professional market footprint.
Techtronic Industries - TTI (2025): Expanded its regional manufacturing footprint with a multi-million-dollar capital injection into automated battery pack assembly lines, mitigating supply chain bottlenecks and increasing regional delivery speed by 35%.
Bosch Power Tools (2024): Formed a strategic cross-industry partnership to advance modular, interchangeable thermal-managed battery architectures, boosting operational safety standards across European professional job sites.
Makita (2024): Unveiled an expanded high-voltage multi-battery system tailored for landscaping and heavy forestry applications, directly displacing gas-powered commercial outdoor equipment and boosting zero-emission portfolio revenue by 18%.
Milwaukee Tool (2023): Introduced next-generation intelligent BMS firmware updates across its flagship battery line, improving over-discharge protection and extending average field lifecycle durability by 25%.
Competitive Landscape
The global power tool battery market is consolidated among tier-1 industrial conglomerates that leverage aggressive brand equity, robust distribution channels, and proprietary battery technology. Key market players include Stanley Black & Decker, Techtronic Industries (TTI), Bosch, Makita, Milwaukee Tool, Hilti, Panasonic, and Hitachi Koki (Hikoki).
Leading strategies center on continuous R&D investment in solid-state capabilities, aggressive patent filings for quick-charge management systems, and exclusive cross-brand compatibility ecosystems designed to lock customers into proprietary brand architectures.
Analyst Commentary
"The power tool battery sector has officially transitioned from an accessory market into a core driver of industrial productivity," said a Senior Research Analyst at Stellar Market Research. "As professional contractors demand total job-site cord independence, the competitive edge no longer belongs merely to the tool manufacturer, but to the innovator who masters energy density, user safety, and circular lifecycle compliance. Companies that successfully navigate raw material volatility through platform standardization will capture outsized market value through 2030."
Future Outlook
Through the remainder of the forecast period, the power tool battery market is poised for accelerated convergence with smart-factory automation and IoT ecosystems. Demand will increasingly pivot toward ultra-fast charging architectures and early-stage solid-state commercial prototypes, driving step-changes in safety and energy density post-2027. Regulatory pressures will weed out non-compliant, low-quality imports, while consolidation among top-tier OEMs will reinforce market stability. Ultimately, sustainability-driven design and modular recycling will dictate long-term brand dominance.
For further information, click the following link:https://www.stellarmr.com/report/req_sample/Power-Tool-Battery-Market/168
About Stellar Market Research
Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Address
Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041
Email
sales@stellarmr.com
Mobile
+91 9607365656