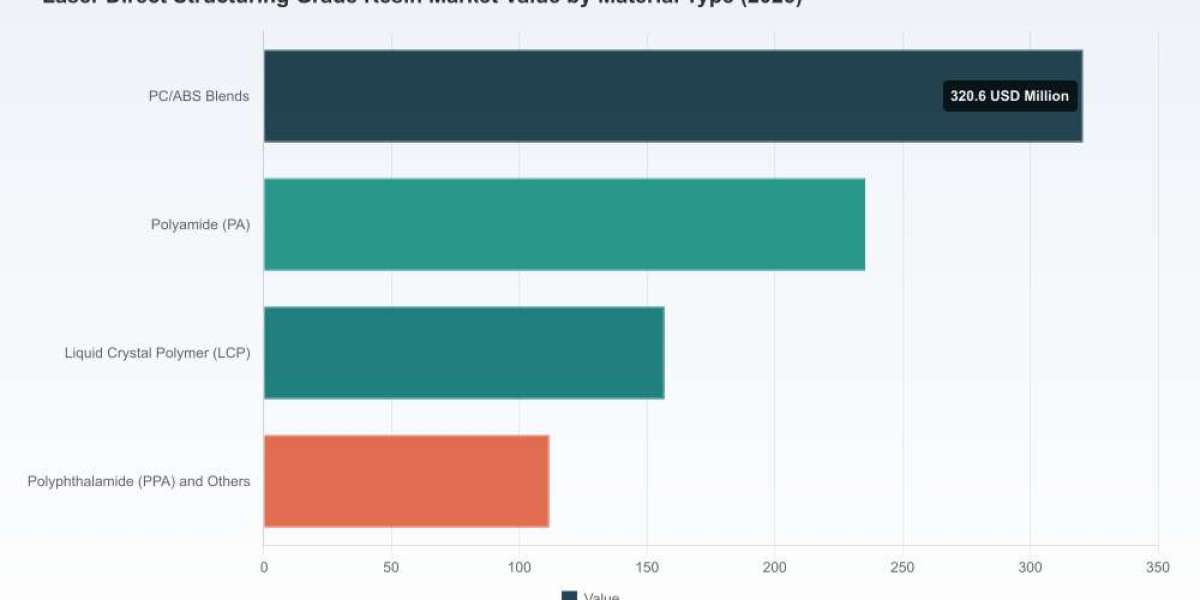

Worldwide Laser Direct Structuring Grade Resin Market — Strategic Insights for 2026 Decision-Making
As enterprises prepare strategic plans for 2026, the Laser Direct Structuring (LDS) grade resin market has reached an inflection point that demands executive-level attention. Our new PW Consulting market brief — derived from a comprehensive 2020–2025 historical analysis and a 2026–2032 forecast model — shows sustained, above-market growth driven by accelerated adoption of molded interconnect device (MID) technologies across consumer electronics, automotive electronics, and industrial sensing. The global LDS-grade resin market, measured at a 2025 base, is projected to continue expanding at a compound annual growth rate (CAGR) of 8.21% through 2032. This briefing outlines why 2026 will be a pivotal planning year, what decision-makers must prioritize, and how our full report converts market intelligence into executable actions.
Worldwide Motor Joint Bearing Market
Why 2026 Matters: The Strategic Inflection
Multiple structural forces are converging in 2026. Miniaturization and the push to integrate 3D circuitry are expanding LDS demand beyond niche applications into high-volume consumer antenna modules and advanced automotive sensors. At the same time, material and process qualifications — particularly approvals tied to laser activation and electroless metallization standards — are reshaping supplier selection and product roadmaps.
Snail Rice Noodles Market
- Scale and Speed: The market’s trajectory from 2023 through 2032 shows a clear ramp in absolute value, underscoring that suppliers and OEMs who secure material qualifications and manufacturing capacity in 2026 will capture disproportionate share as volume ramps.
- Qualification as a Barrier: LPKF qualification and equivalent approvals remain gating factors for adoption in regulated applications such as automotive sensors and medical devices. Recent approvals have broadened the material palette, but they also raise the bar for validation and supply continuity.
- Concentration and Competitive Tension: The market exhibits a moderate-to-high concentration among leading polymer and compound suppliers. This creates both risks (supply tightness, price pressure) and opportunities (strategic partnerships, co-development).
Data-Driven Market Trajectory (Preview)
Using 2025 as the analytical base year, our model integrates demand-side adoption curves and supply-side capacity developments to produce a forward view through 2032. The model incorporates component-level manufacturing forecasts, adoption rates for MID-enabled designs, and qualification timelines for advanced thermoplastics. The headline takeaway: the market is on a multi-year growth path consistent with double-digit expansion in several sub-segments, translating into robust revenue growth at the overall level driven by both unit growth and price/mix improvements tied to higher-performance resins.
Worldwide Cold Formed Blister Foil Market
What the PW Consulting Report Delivers (Operationally Focused)
Our full report is structured to convert insight into action for procurement, product, and corporate strategy teams. Key deliverables include:
- Market sizing and demand modeling calibrated to 2025 base-year activity, with scenario analysis for alternative adoption curves across 2026–2032.
- Material and process qualification timelines, including the impact of LPKF approvals and the practical steps required for qualification in high-reliability sectors.
- Supply chain stress-testing: vendor capacity, lead-time sensitivity, and raw material dependency mapping for organometallic additives and engineering thermoplastic feedstocks.
- Commercial posture guidance: recommended pricing strategies, contractual frameworks (long-term offtakes vs. spot buying), and inventory hedging for mid-to-long cycle stability.
- Go-to-market playbooks: product positioning for OEMs, co-development models with compounders, and entry/expansion frameworks for regional producers.
- Investment and M&A decision frameworks: value drivers for bolt-on acquisitions, capacity expansions, and technology licensing.
Note: This preview intentionally omits detailed segment-level shares and dollar estimates for regions, material types, and end-use applications — these are presented in full within the report to verified subscribers.
Segment & Technology Dynamics (Executive Summary)
LDS-grade resins are engineered thermoplastics compounded with organometallic additives to enable laser activation and subsequent metallization. The practical material set includes, but is not limited to, polycarbonate blends, polyamides, liquid crystal polymers, polyphthalamides, PEEK, PPS, and other high-performance polymers. Recent technical developments — notably the qualification of new PPS grades and PEEK-based compounds by laser-system providers — are expanding the usable material toolkit for demanding MID applications.
- Material Evolution: Advances in additive chemistry have improved laser activation consistency and metallization adhesion, allowing broader substitution across performance and cost points.
- Qualification Landscape: LPKF and similar vendors remain the de facto gatekeepers for LDS process qualification. Approval pathways can materially affect time-to-market and commercial viability for new material entrants.
- Application Pull: High-volume consumer electronics (antenna modules), automotive electronics (sensor housings and integrated interconnects), and select medical/industrial uses are driving differentiated material requirements — from colorability and flame retardancy to thermal/chemical resistance.
Competitive Landscape: Capabilities and Strategic Moves (Preview)
The competitive set comprises global specialty polymer producers, compounders, and engineering-plastics divisions of diversified chemical companies. The market exhibits meaningful concentration among top suppliers, creating a landscape where tier-one compounders and polymer manufacturers exert pricing influence while nimble regional players compete on customization and speed.
- Key Global Players: Major suppliers have established LDS-grade portfolios spanning PC/ABS blends, LCP, PEEK-qualified compounds, and PA/PPS variants. Their strategic strengths include longstanding relationships with MID integrators, co-development capabilities, and vertical integration across polymer synthesis and compounding.
- Recent Industry Moves: Several firms introduced specialized LDS resin lines aimed at automotive and high-volume manufacturing in late 2025 and early 2026, while targeted LPKF approvals expanded the number of qualified materials for automotive sensing applications. These events are accelerating product roadmaps and opening more supplier options for OEMs.
- Consolidation Signals: Market concentration metrics indicate that leading suppliers hold a meaningful share of the market, yet the field remains open to new entrants with differentiated additives or qualification partnerships.
For strategic buyers and investors, the report provides vendor scorecards, capability matrices, and a risk-weighted supplier short-list to support sourcing and partnership decisions.
Actionable Strategic Recommendations for 2026
Based on our analysis, PW Consulting advises executives to undertake the following actions in 2026 to secure competitive advantage:
- Fast-track qualification pipelines: Prioritize early engagement with LPKF-qualified material vendors, and budget for concurrent validation activities (e.g., thermal cycling, chemical exposure) to compress time-to-production.
- Lock in multi-source agreements: Structure supply contracts that balance guaranteed volumes with flexibility to switch materials as new LPKF approvals broaden options—this reduces single-supplier risk while preserving agility.
- Invest in co-development: Select a small number of compounders for co-development agreements aimed at tailoring additives for your product mix (e.g., flame retardant PC/ABS for consumer devices vs. PEEK/PPS for sensor housings).
- Supply chain resilience: Map critical feedstocks (including organometallic additives) and create inventory and supplier diversification strategies for 12–18 month cycles aligned with product ramp schedules.
- Evaluate CAPEX vs. outsource: For OEMs considering in-house MID manufacturing, perform a detailed TCO that includes qualification costs, yield ramps, and capital for laser processing versus partnering with contract manufacturers.
- Monitor regulation and sustainability: Track changes in material restrictions and end-of-life requirements; incorporate recyclability and chemical compliance into material selection criteria.
M&A and Investment Considerations
2026 will likely be an active year for strategic investments in LDS materials and adjacent process technologies. Targets that combine validated material portfolios with qualification certificates and established MID customer relationships will command premium valuations. Our report offers a deal-screening framework that quantifies synergy potential across product development, shortened qualification timelines, and access to regional manufacturing footprints.
How the Full Report Supports Board-Level Decisions
Boards and C-suite teams require concise, risk-adjusted inputs to set capital allocation and partnership strategies for the coming three years. The full PW Consulting report translates market dynamics into executive templates: scenario-based forecasts aligned to product portfolios, supplier risk heat maps, recommended contracting language for strategic offtakes, and prioritized investment options ranked by expected ROI and strategic fit.
Next Steps — Accessing the Full Intelligence
This article is a strategic preview designed to surface the most consequential dynamics shaping the LDS-grade resin market in 2026. For decision-makers seeking executable detail — including regional and application-level demand breakdowns, supplier market shares by segment, and a granular view of material performance trade-offs — the complete Worldwide Laser Direct Structuring Grade Resin Market report contains the full datasets, vendor scorecards, and playbooks required to act decisively.
Contact PW Consulting to obtain the full report and a tailored briefing for your executive team. Our analysts are available to workshop implications for procurement, product development, and M&A strategies on a confidential basis.
For detailed analysis of this topic, please visit the official page:Worldwide Laser Direct Structuring Grade Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com