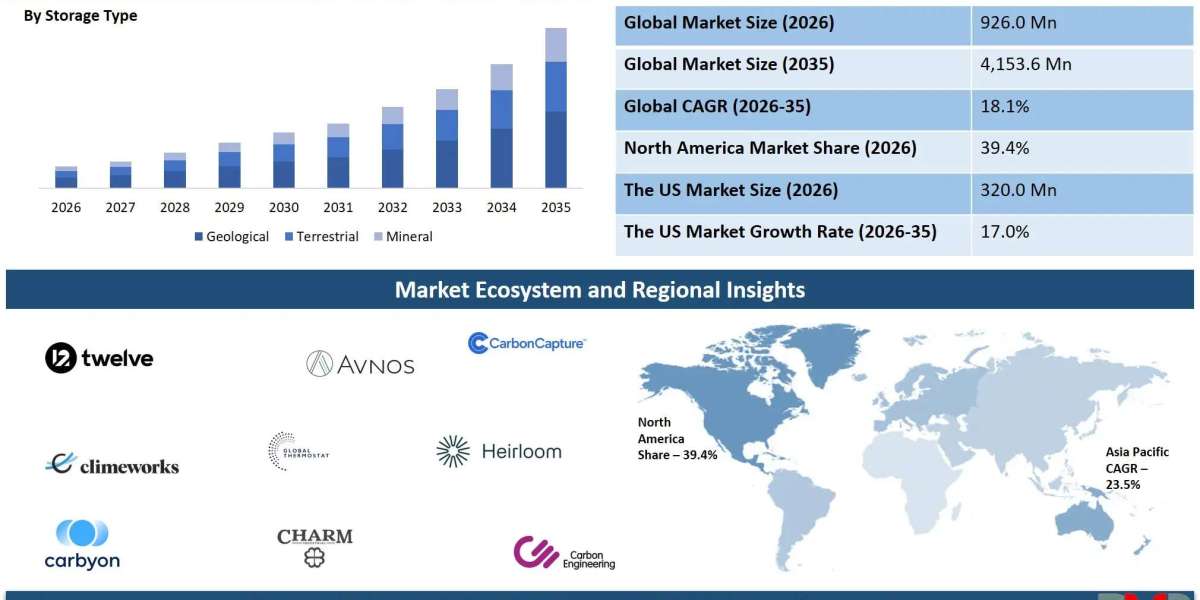

According to Dimension Market Research, the Carbon Dioxide Removal Market is expected to grow from USD 926.0 million in 2026 to USD 4,153.6 million by 2035, registering a strong 18.1% CAGR during the forecast period. Growing climate commitments, corporate net-zero targets, carbon-credit demand, technological advances, and government support are creating a rapidly expanding market for carbon removal technologies and services.
Carbon dioxide removal, commonly referred to as CDR, includes technologies and nature-based approaches designed to remove carbon dioxide from the atmosphere and store it for long periods. The market encompasses Direct Air Capture, Bioenergy with Carbon Capture and Storage, afforestation and reforestation, soil carbon sequestration, ocean-based carbon removal, enhanced weathering, and carbon mineralization.
The market is developing as governments, industries, and corporations look beyond emissions reduction toward strategies that can address residual emissions. Improvements in measurement, monitoring, verification, storage, renewable-energy integration, and digital technologies are helping move carbon removal from early-stage projects toward larger commercial opportunities.
Net-Zero Targets Create Strong Market Momentum
The global push toward net-zero emissions is one of the most important factors supporting carbon dioxide removal.
Many industries face emissions that are difficult to eliminate completely, particularly in sectors such as cement, steel, chemicals, aviation, and other heavy industries.
Carbon removal can complement emissions-reduction strategies by addressing residual carbon dioxide emissions.
As governments and corporations strengthen long-term climate commitments, demand for measurable and durable carbon removal solutions is expected to increase.
Carbon Removal Complements Emissions Reduction
Carbon dioxide removal is not a substitute for reducing greenhouse-gas emissions.
Instead, it can complement decarbonization by addressing emissions that remain after other reduction measures are implemented.
This distinction is increasingly important for companies developing credible net-zero strategies.
CDR technologies and nature-based approaches can provide additional tools for managing difficult-to-abate emissions while supporting broader climate objectives.
Direct Air Capture Leads Technology Demand
Direct Air Capture is expected to remain the leading technology segment.
According to Dimension Market Research, Direct Air Capture is projected to account for approximately 34.2% of market share in 2026.
DAC systems directly capture carbon dioxide from ambient air.
The technology is attracting investment because it can potentially be deployed in locations with suitable energy and storage resources.
Improvements in sorbents, energy efficiency, process design, and system scale are supporting the development of DAC projects.
Solid Sorbents and Liquid Solvents Support DAC Innovation
Direct Air Capture includes different technological approaches.
Solid sorbent systems and liquid solvent systems can capture carbon dioxide using different chemical processes.
Research is focused on improving capture performance while reducing the energy and material requirements of the process.
Lower-cost sorbents, improved regeneration methods, and better system integration can influence the future economics of DAC.
Renewable Energy Integration Supports Carbon Removal
Carbon removal technologies can require significant amounts of energy, making energy sourcing an important consideration.
The integration of solar, wind, and other renewable resources can help reduce the emissions associated with energy-intensive carbon removal operations.
According to DMR, the growing integration of renewable energy with carbon removal technologies is an important market trend.
This creates opportunities for projects located near abundant renewable-energy resources.
Energy and Power Sector Creates Demand
The energy and power sector is expected to account for approximately 29.5% of market share in 2026, according to DMR.
Power generation remains an important source of carbon emissions, creating a significant need for decarbonization technologies.
Carbon capture and removal systems can be integrated with selected power-generation applications to support lower-emission operations.
The expansion of renewable energy can also provide electricity for carbon-removal facilities.
Industrial Decarbonization Expands the Addressable Market
Heavy industries such as cement, steel, and chemicals face technical challenges in eliminating all emissions.
Carbon removal and carbon-management technologies can support their broader decarbonization strategies.
The DMR report identifies industrial decarbonization as the fastest-growing application segment.
As industries face increasingly stringent emissions objectives, demand for scalable carbon-management solutions is expected to expand.
Carbon Credits Create a Financial Incentive
Carbon credits and offsets are another important component of the market.
DMR projects the carbon credits and offsets segment to account for approximately 38.7% of market revenue in 2026, making it the leading application segment.
Companies can purchase credits associated with qualifying carbon-removal projects to support climate strategies.
The expansion of voluntary and compliance carbon markets is increasing interest in durable and measurable removal projects.
Measurement and Verification Become Essential
The credibility of carbon removal depends heavily on accurate measurement.
Monitoring, reporting, and verification systems can help establish how much carbon is actually removed and how long it remains stored.
MRV services are therefore becoming increasingly important.
According to DMR, MRV is the fastest-growing service-type segment, reflecting rising demand for reliable carbon accounting and verification.
Geological Storage Leads Storage Types
Geological storage is expected to remain the leading storage segment.
DMR projects geological storage at approximately 41.3% market share in 2026.
Carbon dioxide can potentially be stored in geological formations such as saline aquifers and depleted oil and gas reservoirs.
The ability to store large quantities of carbon for extended periods makes geological storage particularly relevant to large-scale removal projects.
Mineral Storage Gains Attention
Mineral storage is emerging as another important carbon-removal pathway.
Carbon dioxide can react with certain minerals to form stable carbonate materials.
This approach can provide durable carbon storage and reduce concerns associated with long-term gas containment.
According to DMR, mineral storage is among the fastest-growing storage types as carbon-mineralization technologies develop.
Bioenergy With Carbon Capture and Storage
BECCS combines biomass energy production with carbon capture and storage.
Plants absorb carbon dioxide during growth, and selected biomass can subsequently be converted into energy while capturing associated emissions.
The captured carbon can then be stored.
BECCS is therefore being explored as a pathway with potential net carbon-removal benefits when its full lifecycle emissions and sustainability requirements are appropriately managed.
Afforestation Supports Nature-Based Removal
Afforestation and reforestation use natural biological processes to increase carbon storage in forests.
Trees and vegetation absorb carbon dioxide as they grow.
These approaches can provide climate benefits while also supporting ecosystems when projects are appropriately designed.
However, permanence, land availability, fire risk, measurement, and biodiversity considerations remain important factors.
Soil Carbon Sequestration Expands
Agricultural practices can increase the amount of carbon stored in soils.
Regenerative agriculture, improved land management, and biochar are among the approaches associated with soil carbon sequestration.
DMR identifies agriculture as the fastest-growing end-user segment, supported by increased interest in sustainable agricultural practices and soil-carbon management.
Biochar Creates Additional Opportunities
Biochar can be produced from biomass and incorporated into soil.
Under appropriate conditions, it can contribute to long-term carbon storage while also supporting soil-management objectives.
Growing interest in agricultural sustainability is increasing attention toward biochar-based carbon removal.
The commercial potential of this approach depends on feedstock availability, production economics, measurement standards, and project verification.
Ocean-Based Carbon Removal Develops
Ocean-based approaches represent another area of technology development.
Ocean alkalinity enhancement and seaweed cultivation are among the approaches covered in the DMR market scope.
Interest in these technologies is increasing as researchers and companies investigate the potential of oceans to absorb and store additional carbon.
Ocean-based CDR remains an emerging field requiring continued research, environmental assessment, and monitoring.
Enhanced Weathering Offers a Mineral Pathway
Enhanced weathering involves accelerating natural mineral-weathering processes that can remove carbon dioxide.
Certain minerals react with carbon dioxide and can ultimately store carbon in stable forms.
The technology is attracting interest because mineral resources are potentially available at significant scale.
However, transport, material handling, energy use, and verification requirements influence project economics.
Carbon Mineralization Supports Durable Storage
Carbon mineralization can convert carbon dioxide into stable mineral forms.
This durability is attractive because it can reduce concerns about carbon returning to the atmosphere.
Research continues to focus on improving reaction rates, reducing processing costs, identifying suitable mineral resources, and developing scalable systems.
AI Improves Carbon Removal Operations
Artificial intelligence is becoming increasingly relevant to carbon-removal technologies.
AI models can evaluate environmental and operational data to identify more efficient operating conditions.
According to DMR, AI can help optimize carbon-capture operations and reduce energy use.
Machine learning can also support predictive maintenance and process optimization.
AI Supports Monitoring and Verification
Carbon removal requires accurate measurement of captured and stored carbon.
AI can help process large datasets from sensors, environmental measurements, storage systems, and operational platforms.
This can improve monitoring and verification workflows.
As projects scale, automated data analysis can become increasingly important for maintaining measurement consistency and transparency.
Digitalization Improves Carbon Accounting
Digital platforms are changing how carbon-removal projects are monitored.
Cloud-based systems can combine project information, sensor data, storage records, carbon accounting, and verification documentation.
These capabilities can improve transparency for project developers, investors, corporate buyers, and regulators.
Digital MRV systems are expected to become increasingly important as carbon-credit markets develop.
Capture and Storage Services Lead
Capture and storage services are expected to represent approximately 44.6% of market revenue in 2026, making them the largest service segment.
These services cover multiple stages of the carbon-removal value chain, including capture, transportation, and storage.
Infrastructure development is particularly important because carbon removal cannot scale without appropriate transportation and permanent-storage capacity.
Carbon Transport Infrastructure Is Critical
Captured carbon dioxide must reach an appropriate storage location.
Transportation can involve dedicated pipelines, shipping, or other systems depending on geography and project design.
The availability of transportation infrastructure can determine whether capture projects can move forward at commercial scale.
Developing carbon networks and shared infrastructure can therefore improve project economics.
Government Incentives Support Commercialization
Policy support is an important driver of the market.
Governments can encourage carbon-removal investment through incentives, tax benefits, grants, subsidies, financing programs, and carbon-market frameworks.
DMR identifies government incentives and policy support as major opportunities for the market.
Policy stability can also improve investor confidence in long-duration carbon-removal projects.
Corporate Net-Zero Commitments Create Demand
Large corporations are increasingly developing emissions-reduction and net-zero strategies.
Companies in sectors with difficult-to-abate emissions may use high-quality carbon removals as part of their long-term climate strategies.
This is increasing demand for removal projects that offer measurable and durable carbon storage.
The expansion of corporate climate commitments can therefore create additional market opportunities.
Carbon Markets Encourage Project Development
Voluntary and compliance carbon markets can provide financial incentives for carbon-removal projects.
Project developers can potentially generate credits from qualifying removal activities.
However, market participants increasingly require transparent methodologies, credible verification, and evidence of durability.
As standards improve, high-quality removal projects may become more attractive to corporate buyers.
High Capital Costs Remain a Major Barrier
Carbon-removal infrastructure can require significant upfront investment.
DAC plants, storage systems, transportation infrastructure, renewable-energy integration, and monitoring systems can all increase capital requirements.
High costs can make early-stage projects difficult to finance without government support, long-term contracts, or premium carbon-removal purchases.
Cost reduction will therefore remain a central objective for technology developers.
Energy Requirements Affect Economics
Some carbon-removal technologies require substantial energy.
DAC in particular can require significant heat and electricity depending on the system design.
If that energy comes from carbon-intensive sources, the overall climate benefit may be reduced.
Integrating low-carbon or renewable energy is therefore important for improving lifecycle performance.
Infrastructure and Storage Limit Scalability
Limited storage capacity and transportation infrastructure remain significant challenges.
DMR identifies insufficient carbon transportation and sequestration infrastructure as a major market restraint.
Projects may be technically feasible but delayed because suitable storage or transportation networks are unavailable.
Shared infrastructure and regional carbon hubs can help address this challenge.
Carbon Removal Requires Long-Term Monitoring
Permanent carbon storage requires long-term monitoring.
Storage operators need to verify that captured carbon remains contained and that project outcomes meet established requirements.
This creates continuing demand for MRV services, sensors, analytics, and verification systems.
Long-term monitoring can also increase project costs but remains essential for market credibility.
North America Leads the Market
North America is expected to hold approximately 39.4% of market share in 2026, making it the leading regional market.
The region benefits from government incentives, research capabilities, private investment, energy infrastructure, and growing interest in direct air capture and other carbon-removal technologies.
The United States is projected to reach USD 320.0 million in 2026, with a 17.0% CAGR over the forecast period.
Europe Strengthens Carbon Removal Investment
Europe's carbon dioxide removal market is estimated at USD 277.8 million in 2026, with a projected 17.6% CAGR.
Strong climate policies, sustainability objectives, and investment in advanced carbon-removal approaches are supporting regional development.
The European market is also benefiting from increasing coordination between governments and private organizations for pilot and commercial projects.
Asia Pacific Offers Fast Growth Potential
Asia Pacific is identified as the fastest-growing regional market.
Rapid industrialization, high emissions from energy-intensive sectors, and increasing government efforts toward climate mitigation are supporting regional demand.
China, Japan, and India are investing in carbon-capture and removal technologies while developing strategies to meet long-term climate objectives.
The region's large industrial base creates substantial potential for future deployment.
Japan Develops Carbon Removal Capabilities
Japan's Carbon Dioxide Removal Market is projected to reach USD 37.0 million in 2026, with an 18.5% CAGR over the forecast period.
Government programs focused on carbon neutrality and industrial decarbonization are supporting market development.
Japan's technological expertise provides opportunities for advanced carbon-capture and removal solutions, although geographical constraints and cost considerations remain challenges.
Competitive Landscape
The Carbon Dioxide Removal Market is highly innovation-driven.
Key companies identified by Dimension Market Research include Climeworks, Carbon Engineering, Global Thermostat, Heirloom, Charm Industrial, CarbonCapture Inc., Carbyon, Mission Zero Technologies, AirCapture, Avnos, LanzaTech, Twelve, CarbonCure Technologies, Blue Planet Systems, CarbiCrete, CarbonFree, Carbfix, Neustark, and Cella Mineral Storage, among others.
Competition focuses on technology efficiency, scalability, cost reduction, permanent storage, project development, MRV, partnerships, and access to financing.
Recent Industry Developments
Policy and corporate activity are also influencing market development.
In February 2026, the European Commission adopted the first methodologies under the Carbon Removal Certification Framework to establish certification rules for permanent carbon-removal activities. The framework covers approaches including direct air capture with storage, biogenic carbon capture, and biochar-based removal.
In September 2025, Google announced an agreement with Vaulted Deep to remove 50,000 tonnes of CO₂ by 2030, reflecting growing corporate interest in emerging carbon-removal solutions.
In June 2025, Norway and Switzerland announced the first cross-border durable carbon-removal deal under Paris Agreement Article 6.2, supporting carbon transport, storage, and credit-transfer mechanisms.
Future Outlook
The Carbon Dioxide Removal Market is forecast to grow from USD 926.0 million in 2026 to USD 4,153.6 million by 2035, representing an 18.1% CAGR.
Direct Air Capture is expected to remain the leading technology, while ocean-based carbon removal is identified as a rapidly developing area.
Carbon credits and offsets should continue to represent a major commercial application as voluntary and compliance markets mature.
The energy and power sector is expected to remain a major end-user category, while agriculture offers strong growth potential through soil carbon sequestration and regenerative practices.
Geological storage will remain important for large-scale permanent carbon removal, while mineral storage can provide additional opportunities for durable sequestration.
AI, digital MRV, remote monitoring, and automated carbon accounting are expected to improve project efficiency and transparency.
Government incentives, corporate procurement, and long-term carbon-removal agreements will remain important for moving projects from demonstration to commercial scale.
Checkout / Buy Report URL: https://dimensionmarketresearch.com/checkout/carbon-dioxide-removal-market/
Conclusion
The Carbon Dioxide Removal Market is moving from an emerging climate-technology sector toward a broader ecosystem of technologies, infrastructure, services, and carbon markets.
Direct Air Capture, BECCS, soil carbon sequestration, afforestation, ocean-based approaches, enhanced weathering, and carbon mineralization provide different pathways for removing and storing carbon.
The market's rapid growth is being supported by net-zero commitments, government incentives, corporate climate strategies, carbon-credit demand, and technological innovation.
Digitalization is becoming particularly important. AI can optimize capture operations and energy use, while digital MRV systems can improve carbon measurement, reporting, verification, and transparency.
At the same time, high capital requirements, energy consumption, limited transportation infrastructure, storage availability, and the need for long-term verification remain important challenges.
North America currently leads the market, while Europe continues to strengthen policy and investment support. Asia Pacific offers significant long-term growth potential due to its industrial base, energy demand, and increasing climate initiatives.
The commercial success of carbon removal will increasingly depend on lowering technology costs, expanding permanent-storage infrastructure, improving measurement standards, and creating credible carbon markets.
With the market projected to reach USD 4.15 billion by 2035, carbon dioxide removal is expected to become an increasingly important component of long-term climate strategies and industrial decarbonization efforts.